Morning Market Briefing · Basic Edition · Tuesday, November 17, 2026 · South Florida · Filed 05:05 ET
“We simply attempt to be fearful when others are greedy and to be greedy only when others are fearful.” — Warren Buffett
- Nvidia’s board is not considering a Huang return, Reuters reports
- SemiAnalysis cuts the 2028 buildout by 28%
- Washington tightens the rental route on chips
The Degenerates Journal is published for research and education purposes only — not financial advice.
Futures
Futures as of 05:05 ET · VIX early · 10-year at Monday’s 5.12% close · risk 96, Risk-Off regime · Lens board as of Monday’s close.
The Story
Monday’s break was a forecast cut, not a data print. SemiAnalysis used the weekend to cut its 2028 AI accelerator spending forecast by 28% — to $758 billion from $1.054 trillion — with Nvidia carrying two-thirds of the silicon reduction, and a new Commerce Department rule required licences for Chinese firms’ remote access to advanced U.S. chips through data centres in five overseas markets. Reuters then reported that Nvidia’s board is not considering bringing Jensen Huang back. The Philadelphia Semiconductor Index fell 5.28%, its worst day since November 5; the S&P 500 lost 1.92% to 7,416.59 in a third straight decline, the Nasdaq Composite fell 2.49% to 24,509.76 and into correction at 10.9% below its October 6 high, and the Dow fell 1.41% — all while the 10-year yield eased to 5.12%, which is to say the selling was never about rates. Nvidia itself fell 4.12% to $156.14 on volume running 1.84 times its average, four brokers cut their price targets on the name in one session while leaving their ratings in place, and the quarter that decides the argument prints tonight after the close: $108.0 billion of guided revenue, a $125 billion question behind it, and an interim chief executive presenting both.
What matters most today — the forecast cut meets its first company print: retail sales at 08:30 ET, three Fed voices, and Nvidia near 16:20 ET
Monday printed the break in full: the semiconductor index down 5.28%, the Engine List down 3.9% to 8.6%, Nvidia down 4.12% to $156.14, the Nasdaq into correction, and Degen Risk at 96, Risk-Off — on a forecast cut and an export rule, with yields easing while it happened. Tuesday’s premarket is a pause, not a verdict: futures down about a third of a percent, the complex down 0.7% to 2.1%, and Asia down a second day (Nikkei −1.34%, Kospi −2.59% to a nine-month low, Taiex −2.31%). A guide that meets the benchmark is a market repricing from fact; a guide that confirms the forecast is a market that has only finished its first leg.
Pre-Market / Overnight Standout
NVDA — NVIDIA −0.3% · Earnings day at Nvidia — the board closes the return door, the targets come down, and tonight the guide is the print.
Nvidia changed hands near $155.60 in the after-hours prints tracked overnight, about 0.3% under Monday’s $156.14 close, on the morning its succession question got its answer. Reuters reported Tuesday, citing three people familiar with the matter, that the board is not considering bringing Jensen Huang back as chief executive and is focused on its independent investigation — led by Wachtell Lipton, Rosen & Katz — into whether his conduct compromised national security or company secrets. The petition to restore him passed 180,200 signatures; President Trump said Monday he “would not mind” a reinstatement; Treasury Secretary Bessent, on Sunday, demanded the opposite — an outside chief executive and a “dramatic shakeup.” As of this morning the contest has a petition, a presidential preference and a Treasury demand on one side, and a board decision on the other: the search the board began selecting a firm for on Friday goes outward, and Colette Kress remains interim chief executive.
Monday’s tape had already voted before the board’s answer printed. Nvidia fell 4.12% to $156.14 on volume running 1.84 times its 30-session average, in a semiconductor index down 5.28% — its worst day since November 5 — after SemiAnalysis cut its 2028 AI spending forecast by 28% over the weekend and the Commerce Department restricted Chinese firms’ remote access to advanced U.S. chips through five Asian and Latin American data-centre markets. Four brokers cut Nvidia targets in the session — UBS to $240 from $300, Mizuho to $220 from $250, TD Cowen to $200 from $275, CLSA to $255 — and every one left its rating unchanged, while Bank of America defended the name at roughly 11 times forward earnings. The cuts repriced the out-years; none of them repriced the franchise.
Tonight the argument gets its first company-issued numbers since the cut. Nvidia reports its fiscal third quarter — the quarter ended October 25, before the resignation — near 16:20 ET, with management presenting at 17:00 ET under interim chief executive Colette Kress. The guide of record is $108.0 billion of revenue plus or minus 2% at a 74.0% gross margin, assuming no China Data Center compute revenue; consensus sits at $108.84 billion and $2.47 a share (28 analysts, SentiSense), with Data Center consensus near $101.8 billion and the estimates running from $107.86 billion to $112.35 billion. The quarter itself is the smaller question: the next quarter’s guide carries a $125.0 billion analyst benchmark, the China wording now sits under both a Treasury compliance clock and Monday’s remote-access rule, and options price roughly a 7% to 10% move on the print depending on the expiry and method.
The map from here runs through Monday’s levels. The close at $156.14 sits between daily support at $153.03 and daily resistance at $161.22 on the board’s record, with weekly support at $147.79 — the level that held the week of November 9 — and weekly resistance at $178.91. The Lens still ranks the name first of sixteen at a 75.0 trio average — Inflection 85 and Position 96 against a Swing score of 44 — while the per-name Meter reads −85.6, Strong Bearish. The business of record and the price of record still point opposite ways; tonight one of them gets a filing to stand on.
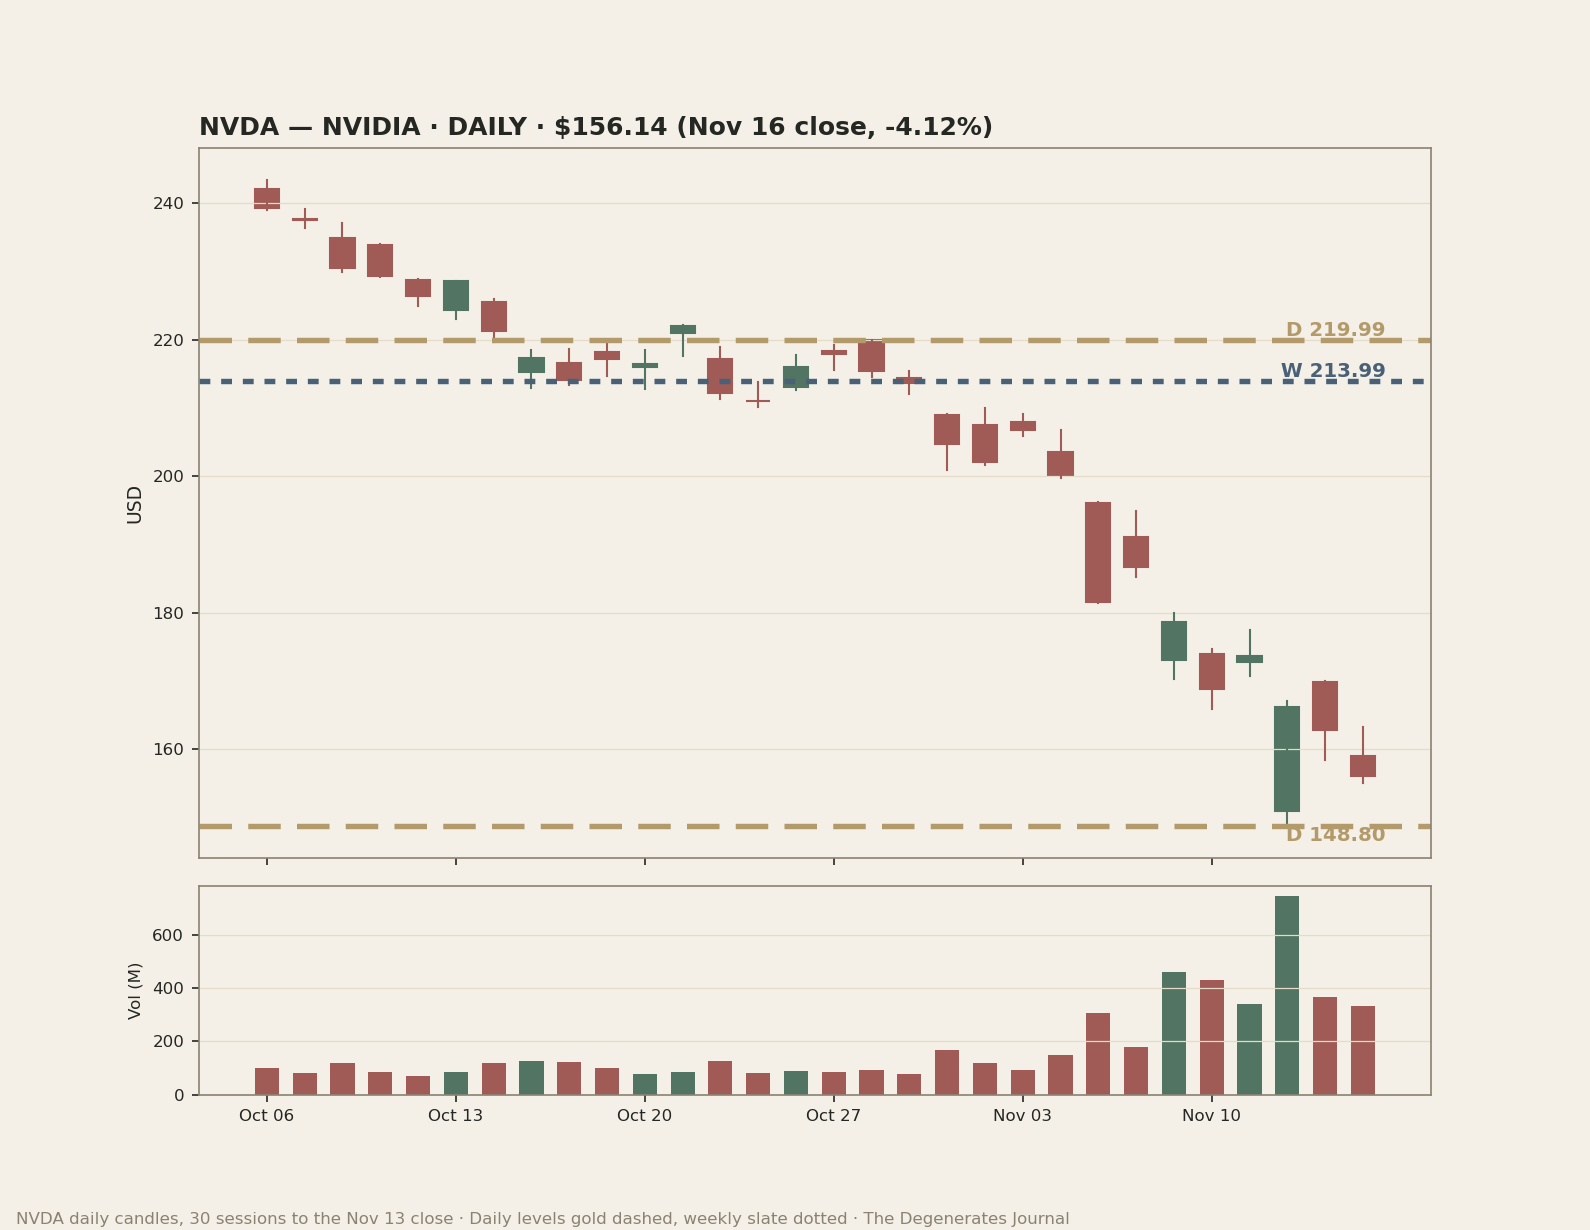
FIG. 1 — NVDA · Daily candles with the key levels · Data through Monday’s close.
The Engine List
Today’s Engine List — six names the desk’s screens carried into Tuesday, ranked lowest to highest by forward multiple where a multiple is on file, with Monday’s closes. The full board, the levels and the Lens reads are Pro.
| Symbol | Company | Last | Change | The take |
|---|---|---|---|---|
| SNDK | SanDisk | $809.11 | −8.6% | SanDisk closed Monday at $809.11 (−8.6%), 43.1% below its 50−day average at 4.8x forward earnings. |
| NVDA | NVIDIA | $156.14 | −4.1% | NVIDIA closed Monday at $156.14 (−4.1%), 26.8% below its 50−day average at 11.4x forward earnings. |
| AVGO | Broadcom | $333.40 | −3.9% | Broadcom closed Monday at $333.40 (−3.9%), 3.3% below its 50−day average at 19.2x forward earnings. |
| AMD | Advanced Micro Devices | $504.28 | −5.6% | Advanced Micro Devices closed Monday at $504.28 (−5.6%), 9.2% below its 50−day average. |
| DELL | Dell Technologies | $320.55 | −7.0% | Dell Technologies closed Monday at $320.55 (−7.0%), 34.5% below its 50−day average. |
| ANET | Arista Networks | $187.02 | −5.2% | Arista Networks closed Monday at $187.02 (−5.2%), 3.0% below its 50−day average. |
Market Health
Degen Risk 96 of 100, Risk-Off regime — computed on Monday’s close from the v2 meter, up 7 points from Friday’s 89: the fear gauge closed at 22.91, the index settled 3.2% under its 50-day average (7,416.59 against a 7,661.42 average), and the credit leg is the loudest of the three — high-yield sits about 5.5% below its 252-session high. Unlike Friday’s concentrated unwind, Monday’s stress was broad: nine of eleven sectors fell, and the meter printed the regime change the tape had been approaching for three sessions.
Breadth and the day's shape — none of the six Engine List names closed above its 50-day average; nine of eleven sectors fell and the tape's count ran the same way
Breadth on the Engine List: none of the 6 Engine List names closed Monday above its own 50-day average — Broadcom came closest at 3.3% below its line, Arista 3.0% below, while SanDisk closed 43.1% below its average and Dell 34.5% below after the week’s round trip completed. Across the market the count ran the same way (one coverage universe counted 962 advancers against 3,167 decliners), and the only sectors that rose were the two that rise when growth is the question: consumer staples, +0.34%, and utilities, +0.12%.
The week’s shape is now a pincer. On one side sits a forecast: SemiAnalysis’s cut says the 2028 buildout is smaller than the complex’s prices assumed, and four target cuts at Nvidia on Monday translated that into the centre’s multiple. On the other side sits a calendar: retail sales this morning, Nvidia’s print tonight, the Fed’s October minutes tomorrow. A forecast can be argued with; the next three releases cannot — they print, and the complex reprices from fact instead of from a model update.
Futures Levels
YM — Sitting on the week-of-Nov 2 weekly swing low at 50,891 (1.0% away).
ES — Sitting on the week-of-Jul 27 weekly swing low at 7,324 (1.2% away).
NQ — Mid-swing between weekly support 26,366 (week of Nov 2) and resistance 30,343 (week of Aug 17).
The Look Ahead
Today 08:30 ET — Retail sales and trade prices (Oct) — The week’s consumer print: retail sales consensus +0.2% in the month after September’s +0.8%, with sales excluding autos at +0.4% (survey consensus); import prices are expected +0.7% after +1.1%, export prices +0.3% after +2.2%. Industrial production follows at 09:15 ET (consensus +0.1%) and the NAHB housing index at 10:00 ET (consensus 29, level with October). Waller speaks at 09:10 ET, Hammack at 09:30 ET and Williams at 14:25 ET.
The rest of the week — Fed meeting minutes Wednesday, claims Thursday with a split consensus, Michigan sentiment Friday, and the December Fed meeting
Today, after the closing bell — Nvidia reports — Nvidia’s fiscal third quarter lands near 16:20 ET against $108.0B of revenue guidance plus or minus 2% at a 74.0% gross margin — consensus $108.84B and $2.47 a share, Data Center consensus near $101.8B, and the next quarter’s guide carrying a $125.0B analyst benchmark. Home Depot and Walt Disney report before the open.
Wed Nov 18 — Fed meeting minutes, housing data, Anthropic prices — The October Fed meeting minutes publish at 14:00 ET — the meeting that held at 3.75–4.00% by 10–2 with Cook and Hammack dissenting for a hike — with housing starts (consensus 1.27M) and pending home sales (consensus −2.3%) the same day, the U.K. inflation print at 02:00 ET, and Anthropic’s initial public offering pricing in the evening at a $70–$78 range.
Thu Nov 19 — claims, Philadelphia Fed, Japan’s inflation print — Weekly claims print Thursday morning with the consensus split between 199,000 and 196,000 by carrier — the edition prints the split, not a blend — after 200,000 the prior week, with the Philadelphia Fed survey (consensus 19.2 after 20.9) beside it and Japan’s October inflation print overnight.
Tue–Wed Dec 8–9 — the December Fed meeting — The meeting the October minutes will be read against: decision Wednesday December 9 at 14:00 ET with the dot plot (Federal Reserve calendar). No consumer or producer price print lands before the committee sits — the next gross domestic product and personal consumption prints arrive November 25 — so the minutes and the claims run carry the whole data argument into December.
Earnings Today
Before the open
- Home Depot (HD)
- Walt Disney (DIS)
- Viking Holdings (VIK)
- JD.com (JD)
- Elbit Systems (ESLT)
- Amer Sports (AS)
After the close
- NVIDIA (NVDA)
- ZTO Express (ZTO)
- Sociedad Química y Minera (SQM)
- Dolby Laboratories (DLB)
- Corporación América Airports (CAAP)
Recent Basic Editions
Education builds conviction
Pro Degenerate — $7.99/mo, no free trial: every edition complete as it publishes, the Pro shelf with the Lens board, the Engine List dossiers and the scorecards. Ultimate Degen — $14.99/mo: everything in Pro, plus Discord — Discord is an Ultimate Degen benefit, not part of Pro.
The GEX LEVELS linked from this journal's Lens plates come from FlowState's Trade Desk — the gamma exposure levels behind the names and the index, published by FlowStateOfMind at flowstateofmind.io.
The Degenerates Journal is published for research and education purposes only — not financial advice.
In this edition
- Yesterday's Tape
- Market Movers
- While You Slept
- Pre-Market / Overnight Standout
- Futures Read
- Market Health
- Economic Calendar
- Earnings Today
- Engine List
- Market News
- The Question into the Close
- Education builds conviction — membership