THE DEGENERATES JOURNAL
Nvidia beats on every line — $115.8B past a $108.0B guide
Engine List SNDK, NVDA, AVGO, AMD, ANET, DELL
Headlines
S&P 500 -1.03% to 7,340.53 — fourth straight loss.
Nvidia $115.8B — past its $108.0B guide.
Retail sales +0.2% — the control group rose 0.6%.
VIX 25.46 — fear gauge up 11.1% to a sequence high.
May contain typos. Prices may be delayed depending on when the data was collected.
© 2026 The Degenerates Journal. All rights reserved.
Degen Risk 96/100 · Risk-Off · this morning's reading — as filed in this morning's Basic: basis November 16 equity and credit closes, live volatility at 05:05 ET · Tape as of 16:05 ET · Futures strip as of 16:35 ET: ES 7,379.00 -60.00 (-0.81%) · NQ 27,216.75 -67.50 (-0.25%) · YM 50,852.00 -818.00 (-1.58%)
1 · The Daily Question, Answered
The Daily Question, Answered
“Does tonight’s Nvidia print — the guide against a $125 billion benchmark, the China wording under a new export rule, any word on the search — steady a complex down three straight sessions, or does the forecast cut get its second leg?”
Into the close — Split by the clock — and the session's half is the graded half. In the cash session the forecast cut got its second leg in full: a fourth straight lower close (S&P 500 -1.03% to 7,340.53), all eleven sector funds lower, financials weakest, the Dow down 1.64% and the VIX up 11.13% to 25.46 — the print steadied nothing that traded between 09:30 and 16:00. Then the print landed at about 16:20 ET and beat the question's own terms: revenue of $115.8 billion against the $108.0 billion guide, data-centre revenue of $107.6 billion, and a fourth-quarter guide near $130 billion against the $125 billion benchmark the question named — with the China answer carried inside the guide, which assumes no data-centre compute revenue from China. The shares rose about 2.5% after hours. Because the question grades on the session it prices, and the session leg completed, it grades Contradicted — with the beat recorded here in full, because Wednesday's session now grades the print instead.
2 · The Story
Nvidia reported fiscal third-quarter earnings after the close that topped Wall Street forecasts: earnings of $2.68 a share against $2.47 expected, revenue of $115.8 billion against estimates of $108.8 billion, and data-centre revenue of $107.6 billion against $101.9 billion expected, CoinDesk reported. The company guided fourth-quarter revenue to a range of $127.4 billion to $132.6 billion, above a $125.3 billion consensus, and added $150 billion to its buyback authorisation. The results are the first announced since Jensen Huang resigned as chief executive; the shares rose 2.4% in after-hours trade on the release.
Source: CoinDesk
Retail sales meet the headline and beat inside — control group up 0.6%. October retail sales rose 0.2% after increasing 0.8% in September, beating expectations for a 0.1% rise in the survey KPMG cited, with sales at $748.2 billion and up 6.8% on a year ago, the U.S. Census Bureau reported. The split under the headline ran stronger than the total: excluding autos, sales increased 0.6%, and the control group — the reading that feeds the government's spending calculation — firmed 0.6% after rising 0.5% in September, while motor vehicle and parts dealers fell 1.6% as the average new-vehicle transaction price topped $51,000. Consumers enter the holiday period with momentum, KPMG wrote — a reading the tape, fixed on the evening's print, declined to pay for.
Source: U.S. Census Bureau
Industrial production falls 0.4% — utilities mask a second factory gain. Industrial production decreased 0.4% in October after increasing 0.7% in September, against a consensus gain of 0.1%: manufacturing output rose 0.3% for a second straight month while mining output fell 0.8% and the utilities index fell 4.3% after spiking the month before, the Federal Reserve reported in its G.17 release. Total production stood 2.1% above its year-earlier level, and capacity use dropped to 76.4%, three points under its long-run average. The headline missed; the factory line inside it — the part that touches the complex's order books — rose again.
Source: Federal Reserve
A fourth straight down day — the Dow falls 846 points into the print. It was another down day on Wall Street as the market sold off across the board ahead of Nvidia's results: the Dow Jones Industrial Average fell 846 points, or 1.64%, and was down more than 1,000 points at one stage, while the S&P 500 declined 1.02% and the Nasdaq Composite slipped 0.74%, TipRanks reported from CNBC data. The selling spread across most sectors. Midday, the National Security Agency said it had experienced temporary degradation during scheduled routine maintenance, after reports of an outage on its internal classified communications network crossed the wires and the Dow's fall deepened. It was the fourth down day for equities.
Source: TipRanks
Disney beats and raises the dividend — revenue up 16% to $25.9 billion. Walt Disney exceeded Wall Street expectations for quarterly revenue and earnings on Tuesday, as higher theme park attendance and strong football viewership lifted results: adjusted earnings of $1.77 a share against $1.67 expected on LSEG estimates, and total revenue up 16% to $25.9 billion, Reuters reported. The experiences division posted record revenue of $10.1 billion, sports revenue rose 16% to $4.6 billion on record viewing, and the board raised the annual dividend by 33% to $2.00 a share. The quarter carried a 53rd week, which the company estimated added about $1.6 billion of revenue and $0.18 of earnings — the beat survives the adjustment, smaller. Disney's shares still closed 1.48% lower at $116.94 on the day's board-wide tape.
Source: Reuters
Home Depot beats on sales, narrows the year — and falls 2.45%. Home Depot's third-quarter adjusted earnings rose 3.2% to $3.86 a share, meeting estimates, while sales grew 4.9% to $43.4 billion and beat the $42.72 billion consensus, Zacks reported. Comparable sales rose 2.2% on a 3% increase in the average ticket even as customer transactions fell 0.5%, and the gross margin contracted about 60 points to 32.8%. Management updated the fiscal 2026 outlook to about 4.5% total sales growth and 1.4% comparable growth. The shares opened lower and closed down 2.45% at $339.01 — the market took the narrowed guide and the margin, not the beat, on a day when housing-linked demand is the consumer's softest leg.
Source: Zacks
Tomorrow: the minutes of the Fed's October meeting at 14:00 ET and housing starts in the morning; Thursday brings Walmart before the open and Anthropic's first session as a public company.
After the close today — Nvidia reported its fiscal third quarter: revenue of $115.8 billion against $108.0 billion of company guidance, earnings of $2.68 a share, and a fourth-quarter guide near $130 billion (CoinDesk; the company's filing). The shares traded up about 2.5% in early after-hours trade, at $159.40 at 16:35 ET.
3 · Data Check — October retail sales — the headline met, the internals beat
| Year ago | Prior | Expected | Printed | |
|---|---|---|---|---|
| Headline sales | — | +0.8% | +0.2% | +0.2% |
| Excluding autos | — | +0.9% | +0.4% | +0.6% |
| Control group | — | +0.5% | +0.1% | +0.6% |
| Motor vehicle and parts dealers | — | -0.2% | — | -1.6% |
| Online retailers | — | — | — | +1.2% |
| Restaurants and bars | — | +0.9% | — | +0.2% |
Advance Monthly Retail Trade Survey for October 2026, reported Tuesday, November 17 at 08:30 ET by the U.S. Census Bureau: total sales $748.2 billion, up 6.8% on a year ago. Expected figures are the consensus carried in this morning's edition (headline +0.2% on the Helious calendar; a second carrier printed 0.0% — the split was printed this morning, not blended). The control group's September reading is the revised +0.5%. The bureau attaches a margin of plus or minus 0.4 points to the monthly headline, and its own note says the 90% confidence band includes zero — the level of sales is a fact; the monthly change is an estimate with a wide band, and the edition reads it that way.
Degenerates Journal's take. The print's two halves point at two different consumers, and both halves are true. The spending half is firm: the control group — the categories that feed the government's consumption calculation — rose 0.6%, twice its recent pace, online sales rose 1.2%, and the year-on-year total is +6.8% into the holiday season. Nothing here says the consumer rolled over, and it rhymes with the morning's company evidence: Disney's parks and Home Depot's ticket both grew. The soft half is where the money is dear: auto dealers fell 1.6% with the average new-vehicle price above $51,000, furniture fell in the federation's parallel count, and Home Depot's transactions fell even as its ticket rose — households are spending, and financing the big items more slowly. Why the tape ignored a firm print is the day's real information: with a December rate increase nearly fully priced, firm spending reads as permission for the central bank, not relief for equities — good data raised the discount rate's shadow on the same morning it proved the demand. What would change the read: the November advance print on December 16, and whether the control group holds above trend through the holiday weeks it is supposed to predict.
4 · What Changed Since the Morning
| Market | The Turn |
|---|---|
| S&P 500 (SPY) | Futures pointed -0.34% lower at 05:05 ET; the fund fell -1.01% as the morning's firm data could not bid the tape and the board sold into the evening's print |
| Nasdaq-100 (QQQ) | The morning's -0.31% future became the least-bad major: the fund fell -0.73% as the chips held — the semiconductor fund down only 0.39% — and the selling rotated into the rest of the board |
| Dow (DIA) | The morning's -0.48% future became the worst major: the fund fell -1.62% and the cash Dow lost 848.75 points, with financials the weakest sector fund and a midday intelligence-network outage headline deepening the fall |
| VIX | Priced 23.82 early, the fear gauge rose to 25.46 (+11.13% on the day) — the highest close of this sequence, set hours before the print it was pricing |
Monday's complex-led selloff broadened into a whole-board one: zero of eleven sector funds higher, financials weakest, and the day's only strength of size sat inside the complex itself — Broadcom +2.46% on the eve of the print that then beat.
5 · Today's Standout
The Day's Standout and Why
NVDA
Nvidia (NVDA) - the print: $115.8 billion of revenue against a $108.0 billion guide, after a fourth straight lower close
$155.46 ▼ -0.44%
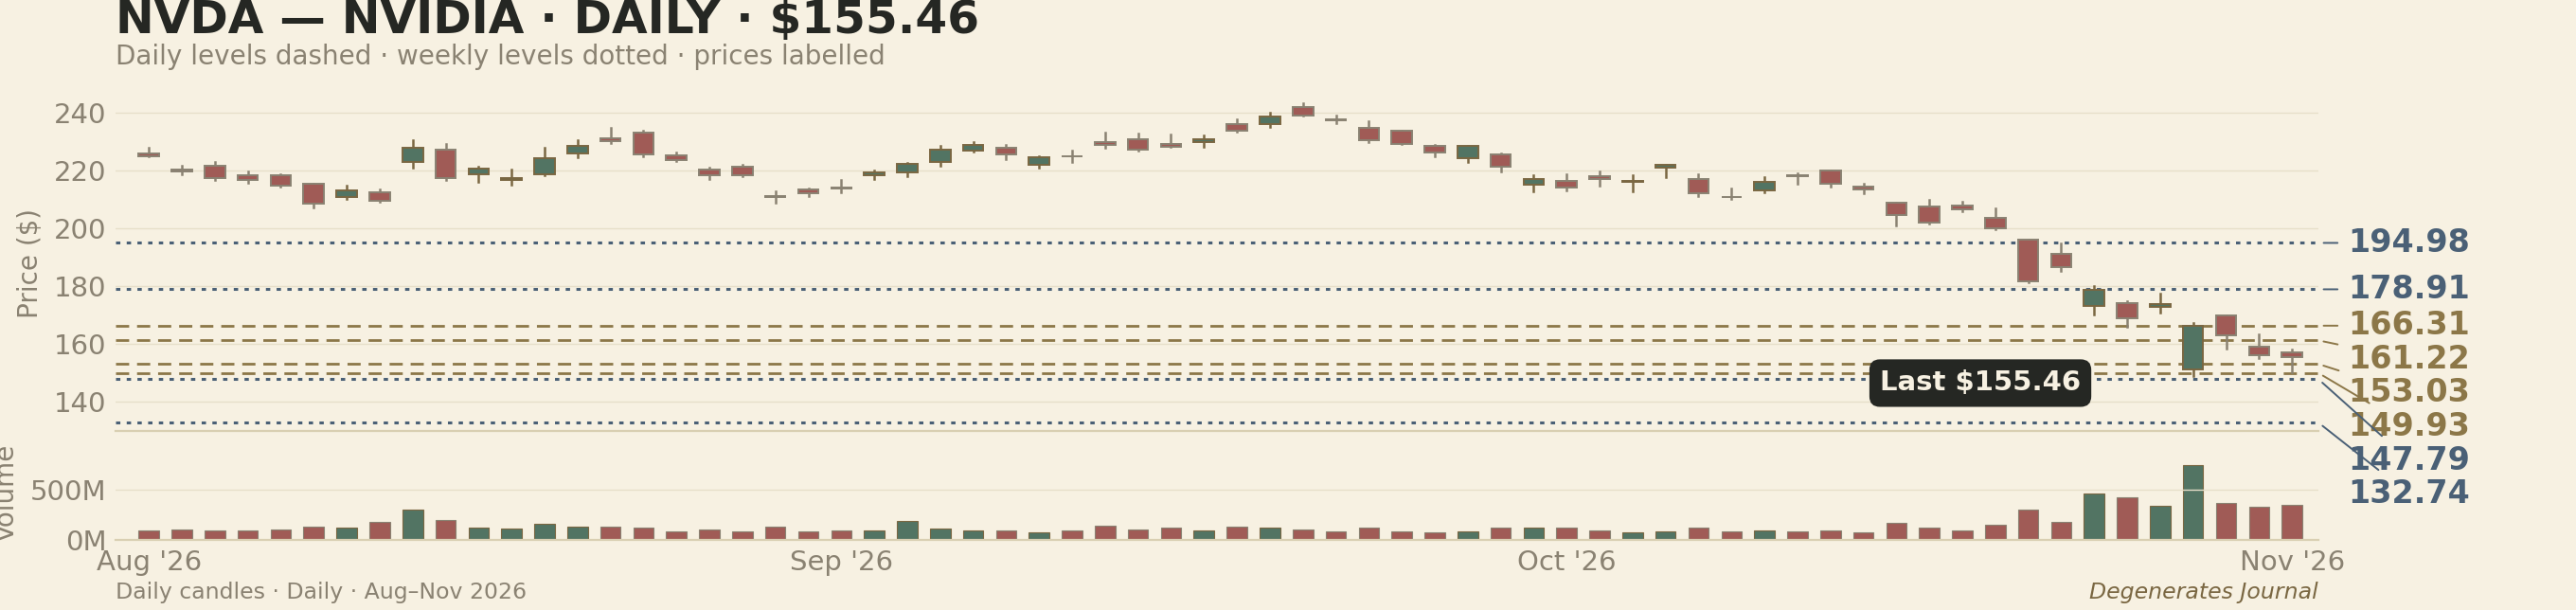
Degen Lens Alpha
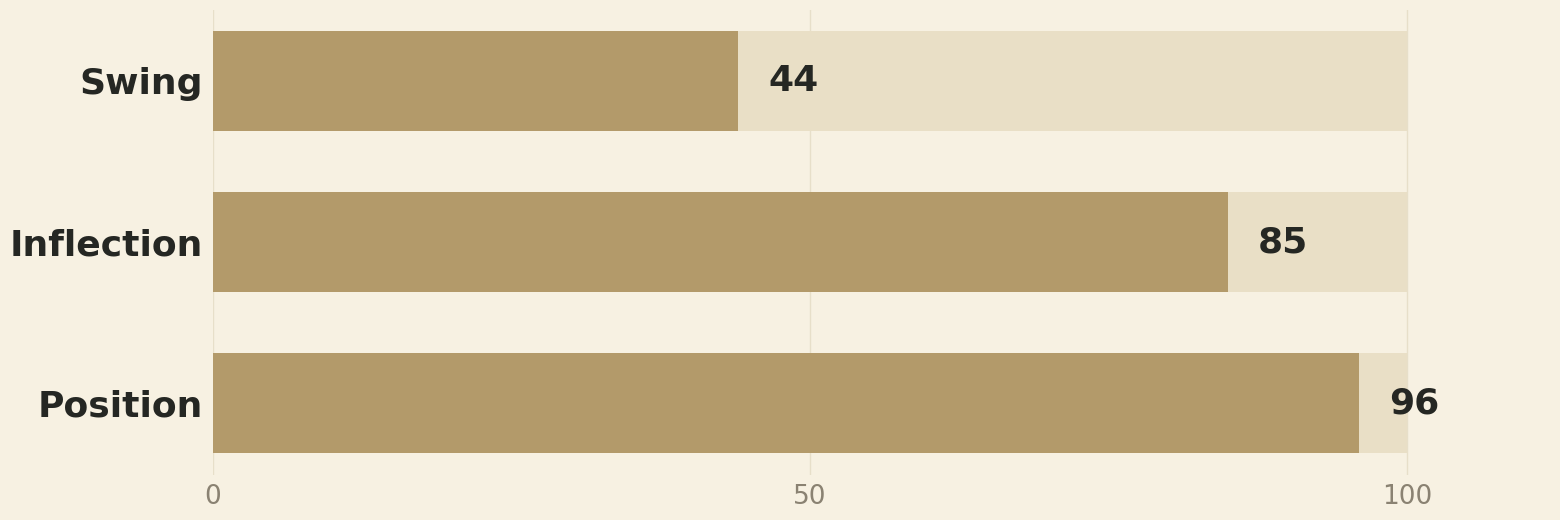
Swing 44 · Inflection 85 · Position 96
Degen Meter
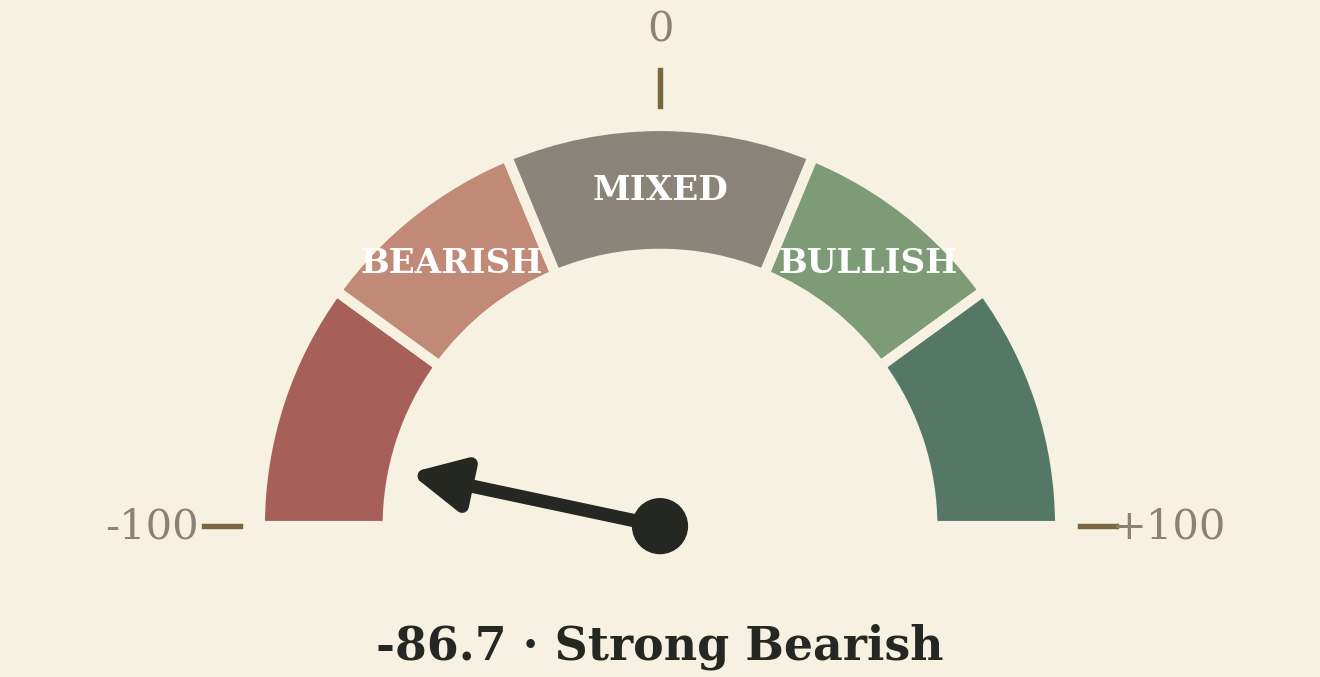
Score -86.7 of ±100 · Label Strong Bearish
Regime: Below its 200-day average · Stretch flag: Washed out
Daily bars through the Tue Nov 17, 2026 close.
Lens scores are the board of record (engine 0.3), scored on the Mon Nov 16 session: Swing 44, Inflection 85 and Position 96 print — a trio average of 75.0, first of sixteen on the board. The LEAPS module prints 96. The chart and the Meter run through today's close.
Why Nvidia stands out. Nvidia (NVDA) closed 0.44% lower at $155.46 on Tuesday — the smallest down day of its four-session slide, on 345.4 million shares, about 1.91 times its recent average volume — and then, twenty minutes after the close, it printed the quarter the whole complex had spent four sessions selling into: revenue of $115.8 billion against the company's own $108.0 billion guide and a consensus near $108.8 billion, earnings of $2.68 a share against $2.47 expected, data-centre revenue of $107.6 billion against $101.9 billion expected, and a fourth-quarter revenue guide of about $130 billion against a $125 billion benchmark (CoinDesk; the company's filing). The shares traded at $159.40 at 16:35 ET, up about 2.5% after hours. No other name carries both halves of the day — the session's weight and the evening's answer — so the standout is the print itself.
What happened. The session swung before it settled. Nvidia opened at $156.91, traded as high as $158.19, then slid with the board to a $150.33 low as a reported outage on a U.S. intelligence network crossed the wires midday and the Dow's fall deepened past 700 points, before recovering into the close at $155.46. The complex split for the first time in four sessions: Broadcom rose 2.46% to $341.60 and the semiconductor fund fell only 0.39% while the S&P 500 lost 1.03% — the selling had rotated out of the chips and into everything else, financials weakest at -1.91%, with all eleven sector funds lower. The day's data argued the other way and was ignored in daylight: retail sales met the headline and beat inside, and Disney and Home Depot both beat before the open. The tape was waiting on one release, and it waited by selling the rest of the board.
The bigger picture. The chart's shape did not change on the day the news did. The close at $155.46 is down 7.95% over five sessions and 28.18% over twenty, and sits 26.59% below the 50-day average of $211.76 and 23.74% below the 200-day average of $203.87. The Degen Meter, run through today's close, reads -86.7 in the Strong Bearish band, below its 200-day average, with the Washed out flag set — deeper than Monday's -85.6. On the Classic levels off Monday's session, the close finished between the first daily support at $153.03 and the daily pivot at $158.12; the day's $150.33 low held the second support at $149.93, and the after-hours print at $159.40 sits above the pivot and under the first resistance at $161.22 — the two lines Wednesday's cash session grades first.
The business. The release is the strongest business evidence of the sequence. Revenue of $115.8 billion is up 103% on a year ago (the company's filing), net income was $65.3 billion, and the data-centre line — $107.6 billion of the total — beat its consensus by more than the entire guide beat. The guide carries the China answer inside it: the fourth-quarter outlook of about $130 billion assumes no data-centre compute revenue from China, so the new export-licensing rule is priced into the company's own numbers rather than left as a risk paragraph. The company also added $150 billion to its buyback authorisation (CoinDesk). Set against the weekend's forecast cut — a 28% reduction to 2028 accelerator spending — the print does not refute the forecast; it shows the current quarter running $7.8 billion above the guide the forecast was measured against, which is a different claim, and the edition keeps the two separate.
How to read it — and the outlook. Read the evening move at its true size. The options market had priced a move near 8.8% for this print; the first after-hours read is about 2.5%, on evening volume, in a name whose cash sessions have swung $8 in a day twice this week. A beat this size against a guide this public usually earns more than that — the discount is the succession question, which no revenue line can answer, and the four sessions of selling that already charged the print's risk. The honest split: the numbers half of the morning's question is answered, in full, in the company's favour; the trust half — who leads the company, and what the board's search produces — is untouched by the release and still open. Wednesday's cash close, not tonight's evening trade, is the grade. On the evidence printed in this edition, the near-term lean on the name stays cautious until the cash market confirms what the release claimed — the same discipline the Meter and the level structure have imposed all week, now with a genuine fundamental offset on the other side of the ledger. What would change the lean: a Wednesday cash close held above the daily pivot at $158.12 and then the first resistance at $161.22, with the Meter climbing out of the Strong Bearish band, followed by the board naming a permanent chief executive. What would extend the slide: the after-hours gain handed back in the cash session, a close under the first daily support at $153.03, and the forecast-cut argument reasserting itself against a guide the company has now set $22 billion above the quarter just printed. A description of the printed evidence, for education only - not a recommendation.
6 · The Index Move
The Close
SPY -1.01% · S&P 500 7,340.53 · QQQ -0.73% · DIA -1.62% · IWM -1.43% · VIX +11.13% to 25.46 at the close. Percentage changes are versus Monday's close; the S&P 500 and VIX are closing levels.
| Index | Last | Change |
|---|---|---|
| S&P 500 | 7,340.53 | ▼ -76.06 (-1.03%) |
| NASDAQ | 24,328.38 | ▼ -181.38 (-0.74%) |
| DOW JONES | 50,759.42 | ▼ -848.75 (-1.64%) |
VIX 25.46 (+11.13%) - breadth broke lower again: 0 of 11 sector funds closed higher, energy the least-bad at -0.52% and financials the weakest at -1.91%; on the Engine List two of 6 names finished higher, and none of the 6 closed above its 50-day average.
10Y yield 5.10%, -1.8 bp vs Monday's close — under Monday's 5.12% print at the bell, after trading toward 5.15% in the morning · 30Y yield 5.46%, -0.9 bp vs Monday's close · WTI crude $85.72, +0.00% vs Monday's close — flat on the day in the futures bar of record · Gold $3,855.70, +0.07% vs Monday's close · Bitcoin $64,533, -0.50% vs the prior completed bar (Nov 16)
Sectors into the close: none of the eleven sector funds finished higher — energy fell least, down 0.52% — while financials fell 1.91% at the back of a board that sold everything it owned. Tape as of 16:05 ET.
7 · Morning Thesis Scorecard
Morning edition (05:05 ET) graded against this afternoon's tape. Tape as of 16:05 ET.
| Morning Statement | Evidence | Verdict |
|---|---|---|
| Does tonight’s Nvidia print — the guide against a $125 billion benchmark, the China wording under a new export rule, any word on the search — steady a complex down three straight sessions, or does the forecast cut get its second leg? | In the cash session the second leg arrived: the complex fell for a fourth straight session — the S&P 500 down 1.03% to 7,340.53, the Dow down 1.64%, all eleven sector funds lower and the VIX up 11.13% to 25.46 — so the print did not steady the complex in the session the question prices. The print itself landed after the bell and beat on every line (revenue $115.8 billion against $108.0 billion guided; data-centre revenue $107.6 billion; a fourth-quarter guide near $130 billion), with the shares up about 2.5% in early after-hours trade — the steadying evidence, if it holds, belongs to Wednesday's session. Because the session leg the question offered as the alternative completed in full, the question grades Contradicted. | Contradicted |
| Morning stance — Dow futures: Sitting on support. | Tested, pierced and lost: Dow futures ranged 50,628 to 51,526 in the cash session — the low 263 points under the 50,891 weekly swing low of the week of Nov 2 — and finished near 50,838, below the support, as the cash Dow fell 1.64%. | Contradicted |
| Morning stance — S&P futures: Sitting on support. | Tested, pierced and recovered: S&P futures fell to 7,308.00 in the cash session — 16.00 points under the 7,324 weekly swing low of the week of Jul 27 — and finished near 7,366.75, back above the support, as the cash index fell 1.03% to 7,340.53. | Confirmed |
| Morning stance — Nasdaq futures: Middle of the swing. | Never tested: Nasdaq futures ranged 26,658.50 to 27,351.00 in the cash session — the low still 292.50 points above the 26,366.50 weekly swing low of the week of Nov 2 and the high far under the 30,343 resistance — and finished near 27,153.25 as the Nasdaq Composite fell 0.74%. | Confirmed |
| The S&P 500 closes today above Monday’s close of 7,416.59. | The S&P 500 settled Tuesday at 7,340.53, below Monday's close of 7,416.59 by 76.06 points (-1.03%), a fourth straight lower close. | Contradicted |
| Nvidia closes today above Monday’s close of $156.14. | Nvidia settled Tuesday at $155.46, down $0.68 (-0.44%) from Monday's close of $156.14, on 345.4 million shares — about 1.91 times its recent average volume — after opening at $156.91, trading as high as $158.19 and as low as $150.33 in its fourth session under an interim chief executive, hours before its print. | Contradicted |
Verdicts describe what the tape did against the morning's own words. They are not calls and not advice. Two confirmed, four contradicted, no unresolved — the morning is graded in the open, line by line.
8 · Movers — Top Gainers
BILL ▲ +12.58% · ACM ▲ +11.08% · RYTM ▲ +8.49% · MNSO ▲ +8.36%
8 · Movers — Top Losers
NXT ▼ -12.13% · IDYA ▼ -9.75% · SMMT ▼ -9.73% · CRM ▼ -9.45%
Movers as of 16:05 ET.
9 · The Engine List
Engine List Closes
Engine List closes as of 16:05 ET
| Symbol | Company | Last | Change |
|---|---|---|---|
| SNDK | SanDisk | $797.24 | ▼ -1.47% |
| NVDA | NVIDIA | $155.46 | ▼ -0.44% |
| AVGO | Broadcom | $341.60 | ▲ +2.46% |
| AMD | Advanced Micro Devices | $503.41 | ▼ -0.17% |
| ANET | Arista Networks | $186.42 | ▼ -0.32% |
| DELL | Dell Technologies | $322.79 | ▲ +0.70% |
Two of the six Engine List names closed higher — Broadcom +2.46% and Dell +0.70% — and all six closed under their 50-day average, Broadcom closest at $341.60 against a 50-day average of $344.35.
10 · Engine List Scorecard
How this morning's Engine List names traded against their levels of record - the board's daily and weekly swing levels printed in this morning's Pro:
SNDK: 33.3% broke, 66.7% not reached. · NVDA: 0.0% broke, 100.0% not reached. · AVGO: 33.3% broke, 66.7% not reached. · AMD: 0.0% broke, 25.0% held, 75.0% not reached. · ANET: 0.0% broke, 75.0% held, 25.0% not reached. · DELL: 0.0% broke, 33.3% held, 66.7% not reached.
11 · Where the Day's Moves Came From
Sectors, Levels & Breadth
The day's sector funds, Tuesday's close versus Monday's:
| Sector Fund | Today |
|---|---|
| Energy (XLE) | ▼ -0.52% |
| Industrials (XLI) | ▼ -0.55% |
| Consumer discretionary (XLY) | ▼ -0.89% |
| Technology (XLK) | ▼ -0.91% |
| Materials (XLB) | ▼ -1.22% |
| Consumer staples (XLP) | ▼ -1.23% |
| Health care (XLV) | ▼ -1.41% |
| Communication services (XLC) | ▼ -1.46% |
| Real estate (XLRE) | ▼ -1.49% |
| Utilities (XLU) | ▼ -1.59% |
| Financials (XLF) | ▼ -1.91% |
0 of the 11 sector funds closed higher. Tuesday inverted Monday's shape: the complex that carried the selling for three sessions was the day's firmest ground — energy -0.52%, industrials -0.55% and technology -0.91% fell least — while the board around it fell further, financials -1.91%, utilities -1.59% and real estate -1.49% at the back. A selloff that rotates away from its origin into the whole list is broadening, and breadth is the day's bearish fact; the offset is that it broadened on positioning into a single evening print, not on new evidence against the complex.
12 · Levels Scoreboard. Across 6 names and 20 graded morning levels: 10.0% broke, 25.0% held and 65.0% were not reached. SanDisk broke its daily swing low at $803.97 and closed under it at $797.24. Broadcom broke the other way — through its daily swing high at $335.74 to close at $341.60. Three touches held on the close: Advanced Micro Devices at its $502.60 daily swing low (a $480.50 intraday low recovered), Arista Networks at all three of its graded levels, and Dell at its $315.00 daily swing low. Nvidia reached none of its graded swing levels: the day's $150.33 low held above the $149.93 second daily support on the board's Classic levels and never reached the $148.80 daily swing low.
13 · Breadth and Volume. On the Engine List, 2 of 6 names closed higher — Broadcom +2.46% and Dell +0.70% — breaking the three-session all-lower streak, and 0 of 6 closed above their 50-day average, Broadcom closest at $341.60 against a 50-day average of $344.35. Regular-session index volume: SPY 1.52 times, QQQ 1.08 times, DIA 1.03 times, IWM 1.13 times their prior 30-session average — a heavy session in the name carrying the week's news, led by Nvidia's 345.4 million shares.
14 · After-Hours Earnings. After the close today — Nvidia reported its fiscal third quarter (release at about 16:20 ET): revenue of $115.8 billion against $108.0 billion of company guidance and a consensus near $108.8 billion, earnings of $2.68 a share against $2.47 expected, data-centre revenue of $107.6 billion against $101.9 billion expected, a fourth-quarter revenue guide of about $130 billion and a $150 billion addition to the buyback authorisation (CoinDesk; the company's filing). The shares traded at $159.40 at 16:35 ET, up about 2.5% from the $155.46 close. ZTO Express, Sociedad Química y Minera, Dolby Laboratories and Corporación América Airports were the evening's other scheduled reporters from this morning's calendar; no print from them had been verified in full as this edition was built.
15 · Setup for Tomorrow. SETUP FOR TOMORROW — Wednesday, November 18: the Federal Reserve publishes the minutes of its October 27–28 meeting at 14:00 ET (Federal Reserve) — the meeting that held the target range at 3.75%–4.00% by 10–2, with two members dissenting for an increase — with housing starts (consensus 1.27M) and building permits in the morning, and Anthropic pricing its public offering in the evening ahead of a Thursday debut. Nvidia's after-hours gain is graded by Wednesday's cash session: the name closed at $155.46 against a daily pivot at $158.12 and first resistance at $161.22 on the board's Classic levels. Thursday, November 19: Walmart reports before the open (company announcement), weekly jobless claims and the Philadelphia Fed survey print in the morning. The December Fed meeting sits on December 8–9 (Federal Reserve), with a December increase nearly fully priced in the futures market (via Reuters).
The Final Word
Four sessions, four shapes of the same trade. Thursday redistributed, Friday handed back, Monday extended into the complex, and Tuesday broadened into the whole board — zero of eleven sector funds higher, the Dow the worst major, financials at the back — on a day whose hard evidence ran the other way: a control-group beat in retail sales, a second straight factory gain inside a soft production headline, and two consumer bellwethers beating before the open. The tape was not pricing the economy on Tuesday. It was pricing one company's first print without its founder, and it charged the whole list for the wait.
The print, when it came, answered the half of the question that carries numbers. Revenue of $115.8 billion against a $108.0 billion guide; a fourth-quarter guide near $130 billion that assumes no data-centre revenue from China and still clears the $125 billion benchmark; a buyback enlarged by $150 billion. The weekend's forecast cut now meets a company guide set above the line it was measured against — which does not settle the 2028 argument, and the edition does not pretend it does, but it moves the burden of proof. The day's graded record moved the same way the month has: two confirmed against four contradicted, and November stands level at 20 confirmed, 20 contradicted and 4 unresolved across 9 graded sessions — an even record for a month that has genuinely argued both sides.
What remains open is everything the release could not print. The board's search for a permanent chief executive is the standing fact of the interim regime; the after-hours gain of about 2.5% — against a priced move near 8.8% — is an evening read, not a verdict, and Wednesday's cash session grades it against the pivot at $158.12. The Fed's October minutes land Wednesday afternoon, Walmart and Anthropic's debut close the week's evidence on Thursday, and the December meeting sits three weeks out with an increase nearly fully priced. The complex has now been sold for four sessions against a print that beat. Whether that was the price of the wait or the start of the repricing is the question the rest of the week is for.
What remains unresolved. 1. Does the give-back become a full hand-back — or does Monday's rally stand into the December meeting?
The Journal Pages
Recent Final Hour Editions
Every Basic edition is free to read — this Final Hour is the page you are on
Advertisement
Education builds conviction
Everything the Journal makes — the free editions, the Pro shelf, the podcast, and the company we keep — gathered on one page. The Pro shelf is the members' shelf on calculateddegens.com — the home of Pro Degenerate at $7.99 a month: the latest edition, the board, the library, scorecards.
The full Pro editions — every weekday morning and the Sunday Pro edition; a full page for every name: charts, levels and the complete read; Fundy's Pick with the full valuation case; Degen Lens scores and LEAPS; delivered on the Pro shelf.
Everything in Pro Degenerate, plus the Discord community — Discord is an Ultimate Degen benefit, not part of Pro — and every edition, complete, as it publishes.
The GEX LEVELS linked from this journal's Lens plates come from FlowState's Trade Desk — the gamma exposure levels behind the names and the index, published by FlowStateOfMind at flowstateofmind.io.
Inside the Pro Edition
Charts, key levels, and fundamentals on every Engine List name, plus the Company Research Comparison names we keep an eye on. PRO DEGENERATE, $7.99/month. New to these terms? Learn the market, plain English.
15 · LEAPS — Pro-Degenerate Only
The LEAPS read rides in the Pro edition. This Final Hour also prints as a PDF — the full edition, page for page. Read the PDF →
The Degenerates Journal is published for research and education purposes only — not financial advice.
In this edition
- The Daily Question, Answered
- The Story
- Data Check
- What Changed Since the Morning
- Today's Standout
- The Index Move
- Morning Thesis Scorecard
- Engine List Scorecard
- Where the Day's Moves Came From
- Levels Scoreboard
- Breadth and Volume
- After-Hours Earnings
- Setup for Tomorrow
- The Final Word
- What Remains Unresolved
- LEAPS
- Education builds conviction — membership