THE DEGENERATES JOURNAL
The Rally That Didn't Need Its Leader
Engine List MU, SNDK, UBER, MSFT, AMZN, AAPL, ENB
Headlines
S&P 500 +2.35% to 7,549.94 — best day since April.
Nvidia -4.27% to $178.67, against the rally.
All 11 sectors higher; VIX falls to 19.92.
Tuesday's CPI, 08:30 ET, is the week's verdict.
May contain typos. Prices may be delayed depending on when the data was collected.
© 2026 The Degenerates Journal. All rights reserved.
Degen Risk 96/100 · Risk-Off · this morning's reading — as filed in this morning's Basic: basis November 6 equity and credit closes, live volatility at 05:19 ET · Tape as of 16:05 ET · Futures strip as of 16:31 ET: ES 7,575.25 +173.25 (+2.34%) · NQ 28,006.25 +921.00 (+3.40%) · YM 52,522.00 +1,137.00 (+2.21%)
1 · The Daily Question, Answered
The Daily Question, Answered
“Does the S&P 500 make it two gains in a row today after Thursday's rout — and hold the bounce into Tuesday's inflation print?”
Into the close — Half of it, decisively. Monday made it two gains in a row — the S&P 500 rose 2.35% to 7,549.94, well above Friday's 7,376.86 close, in the index's best session since April, with all eleven sector funds higher and the VIX back under 20. The second half of the question — whether the bounce holds into Tuesday's inflation print — cannot settle until Tuesday's session trades, so the question stays open on the record and grades in full tomorrow.
2 · The Story
US stocks rallied on Monday as a drop in oil prices tempered inflation fears and helped the S&P 500 bounce off its biggest weekly drop since April 2025, Reuters reported. Each of the eleven major sector indexes rose, with industrials and consumer discretionary among the top performers, and the S&P 500 was on track for its biggest daily percentage gain since April 8. Oil extended recent losses after President Donald Trump said he is unlikely to order fresh attacks on Iran. The rally came a day before the Labor Department releases the October consumer price index on Tuesday.
Source: Reuters
Into Tuesday: the October consumer price report at 08:30 ET is the last inflation reading before the December Fed meeting — the open question is whether a one-day oil-led rally survives it.
After the close today — Occidental Petroleum, Rocket Lab, AST SpaceMobile, The Trade Desk, Take-Two Interactive and Hims & Hers Health headline a heavy after-hours calendar; no major print had landed by the time this edition was built (16:30 ET).
3 · Data Check — September wholesale inventories — the quiet print under the rally
| Jul | Aug | Sep (adv) | Sep (final) | |
|---|---|---|---|---|
| Wholesale inventories | — | +0.6% | +0.6% | +0.7% |
| Wholesale sales | — | +2.0% | — | +2.8% |
| Inventories/sales ratio | — | 1.23 | — | 1.21 |
U.S. Census Bureau, wholesale inventories (final), released Monday Nov 9 at 10:00 AM ET. August revised in today's release; the September advance reading was +0.6%. Inventories rose 7.6% from a year earlier.
Degenerates Journal's take. The day's only scheduled US release was a small one, and it cut in the economy's favour. September inventories were revised a tick higher — +0.7% against the +0.6% advance reading — while wholesaler sales jumped 2.8%, so the stock on shelves fell to 1.21 months of sales from 1.23: restocking that is being sold through, not a glut building. The detail ties the print to the week's main story — electrical goods stocks surged 2.5%, which Reuters linked to the artificial-intelligence buildout — the same buildout whose leadership name, Nvidia, spent the day falling on a governance headline while the rest of the market rallied. Tomorrow's consumer price report is the print that matters for December's Fed pricing; today's says the goods pipeline behind it is moving, not clogging.
4 · What Changed Since the Morning
| Market | The Turn |
|---|---|
| S&P 500 (SPY) | Futures pointed +0.41% higher overnight; the cash session far outran it, +2.37% on the fund and +2.35% on the index |
| Nasdaq-100 (QQQ) | The morning's softest future (+0.18%) became the day's leader: the fund rose +3.54% even as Nvidia fell |
| Dow (DIA) | The morning's leading future stayed strong: the fund rose +2.17% and the cash Dow added 1,104.02 points |
| VIX | Friday's fear gauge unwound hard: 25.64 to 19.92, down 22.31%, the first close under 20 since the selloff |
The recovery broadened on every measure the morning lacked: all eleven sector funds higher, all seven Engine List names higher, and fear back under 20 — with Nvidia the single large exception.
5 · Today's Standout
The Day's Standout and Why
NVDA
NVIDIA (NVDA) - the one big name that fell on the market's best day since April
$178.67 ▼ -4.27%
Degen Lens Alpha
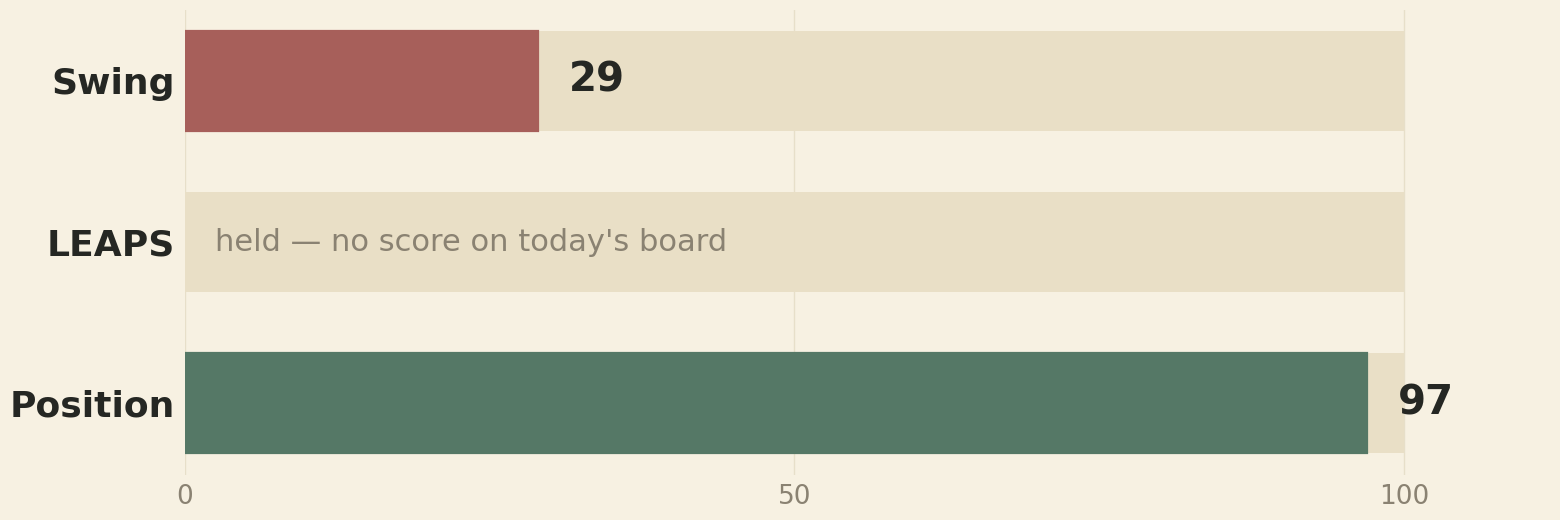
Swing 29 · LEAPS — (no score on today's board) · Position 97
Degen Meter
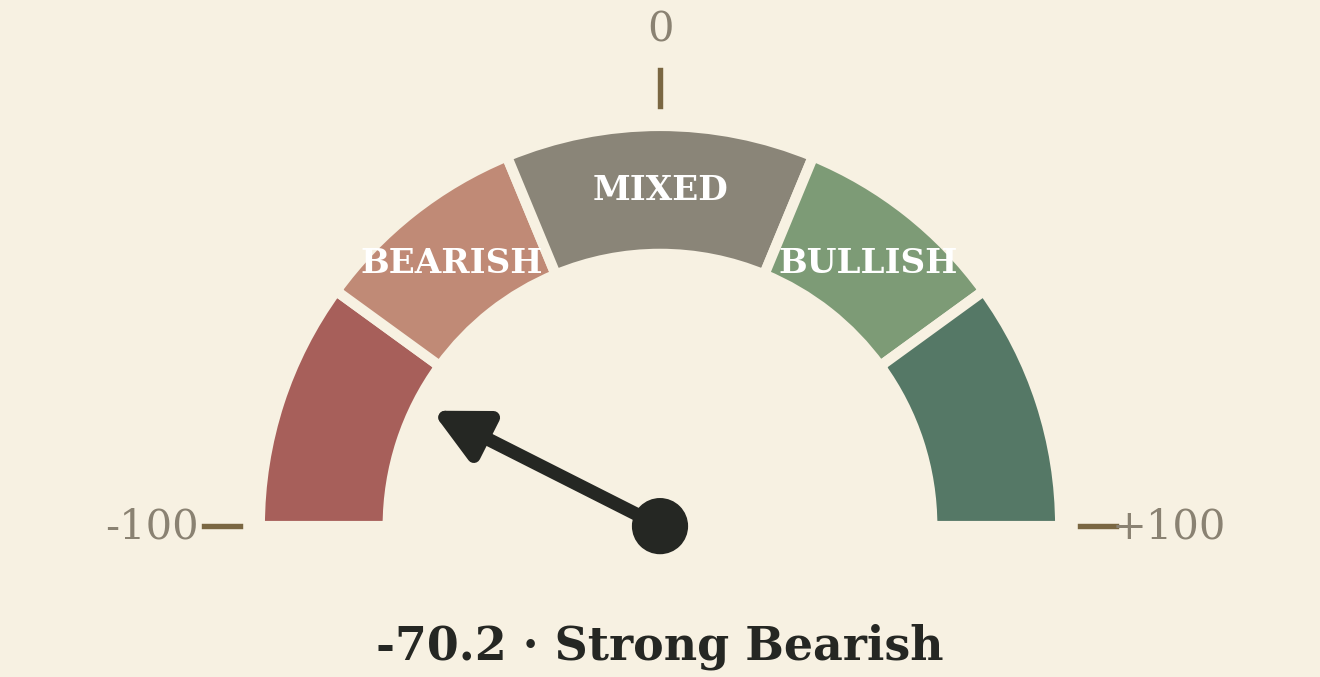
Score -70.2 of ±100 · Label Strong Bearish
Regime: Below its 200-day average · Stretch flag: Washed out
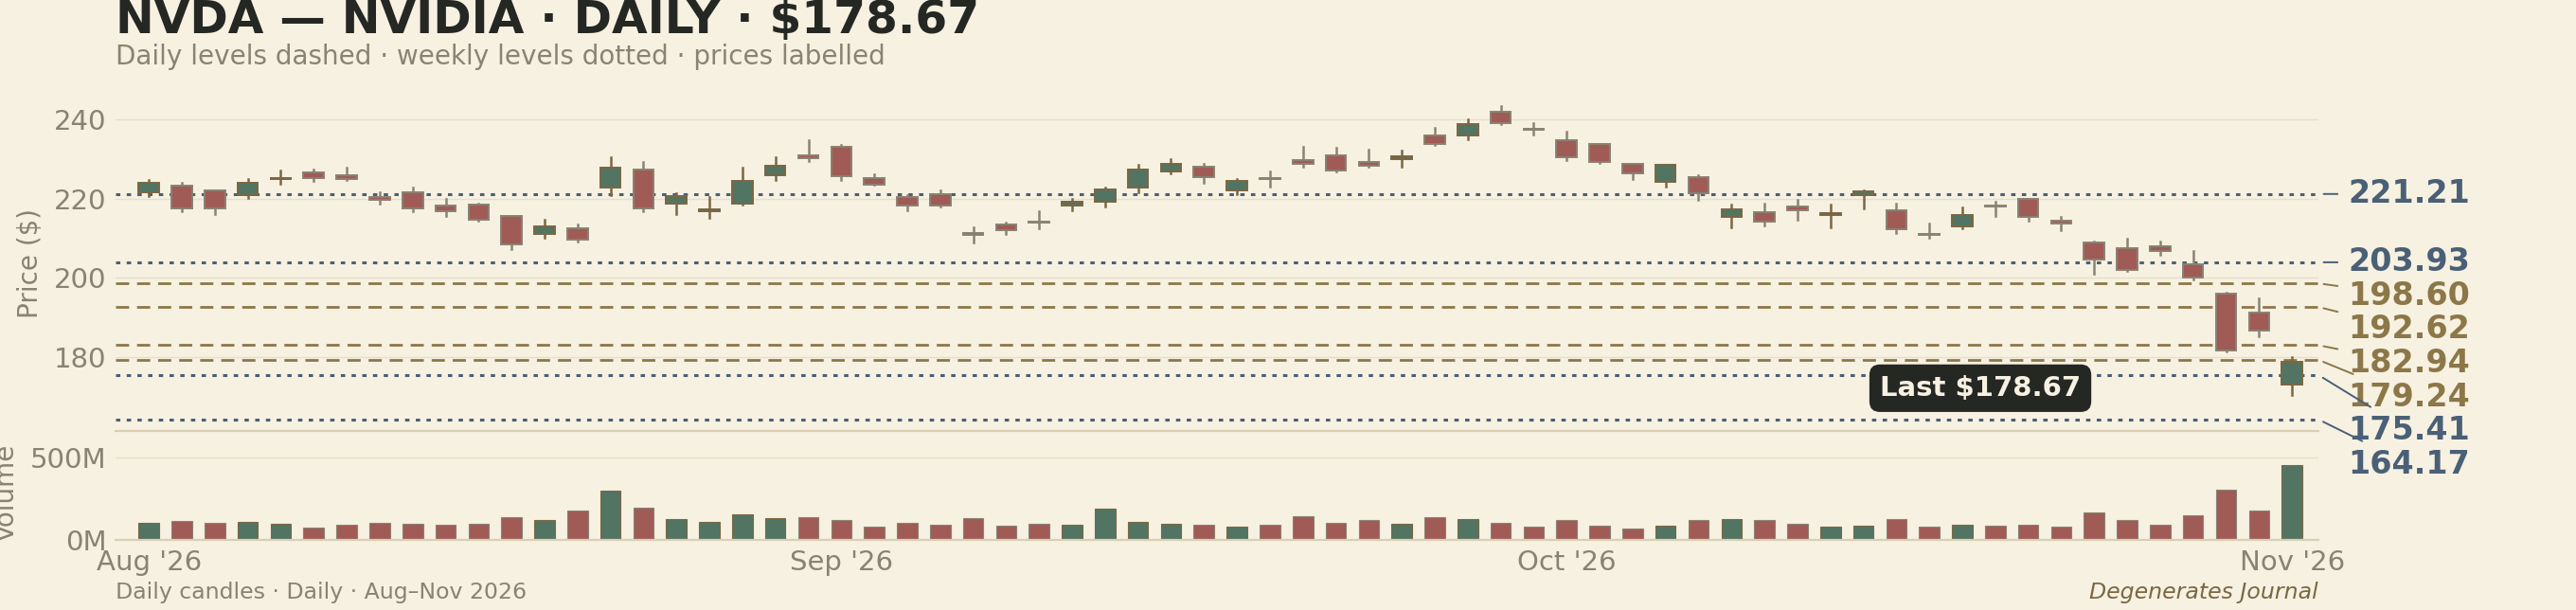
Daily bars through the Mon Nov 9, 2026 close.
Scores out of 100, from this morning's Lens board (scored on Friday's settled closes); LEAPS carries no score on today's board — its coverage is held, so no LEAPS figure prints. The chart and the Meter run through today's close.
Why Nvidia stands out. Nvidia (NVDA) was the day's exception: it fell 4.27% to $178.67 while nearly everything else climbed. The S&P 500 added 2.35% and all eleven sector funds ended in the green; Broadcom added 8.78% and Lam Research 10.41%. It was also the most active stock in the market, with about 455 million shares changing hands, roughly 3.9 times its recent average volume. On the strongest tape since April, the market's leadership name fell, on the heaviest volume in the market: that is the standout.
Why it fell. The cause was Sunday's company news, carried into the session. Nvidia's board said Sunday it has opened an independent investigation, with outside counsel, after learning that chief executive Jensen Huang was sought out by a foreign intelligence effort aimed at extracting the company's technology secrets. The board said it has no reason to believe any secrets were compromised or that operations were affected, and Huang remains chief executive while the inquiry runs. The shares opened near the day's low, traded as low as $170.24 — the lowest intraday level since March, according to Reuters — and recovered only part of the way into the close.
The bigger picture. Monday extended a slide, it did not start one. The shares are down 11.58% over five sessions and 21.05% over twenty, and the close at $178.67 sits 18.43% below the 50-day average of $219.04. The Degen Meter, run through today's close, reads -70.2 in the Strong Bearish band, below its 200-day average, with the Washed out flag set — the same washed-out reading the morning board carried, deepened by today's fall. On the levels the morning board's Classic pack sets: the close broke under the daily second support at $179.24, while the weekly first support at $175.41 was tested intraday (the low was $170.24) and held on the close.
The business. Under the headline, the filed business is unchanged today. Over the last twelve months in the filed numbers the company grew revenue 83.4% from a year earlier, at a gross margin of 74.7% and a free-cash-flow margin of 41.9%. The next scheduled test is the earnings report a week from tomorrow, after the November 17 close, against guidance of $108.0 billion of revenue; House committee chairs have also asked the company for a briefing by November 18.
How to read it — and the outlook. The session priced the two halves of Sunday's statement separately: a real investigation, and no finding of compromise. The tape's verdict on day one was caution — the shares closed lower on a day when almost nothing else did, and on volume that says the selling was deliberate, not drift. What argues against reading it as a break in the business: the board's own statement, the partial recovery off the $170.24 low, and the weekly support that held on the close. What would change the read either way is dated: the investigation's findings, and the November 17 report. On the evidence printed in this edition, the near-term lean is bearish - cautiously so, not strongly. The close at $178.67 sits below every Classic level the board set above it, 18.43% under the 50-day average, with the Meter at -70.2 in the Strong Bearish band. Two readings argue against pressing the lean further: the close held above the weekly first support at $175.41 after testing it intraday, and the Lens Position score on this morning's board stands at 97 — the board's long-horizon read did not move with today's headline. What would change the lean: a close back above the daily levels at $179.24 and $182.94 with the Meter climbing out of the Strong Bearish band. Until then, the fall reads as a governance headline being priced into a falling tape, not a turn. A description of the printed evidence, for education only - not a recommendation.
6 · The Index Move
The Close
SPY +2.37% · S&P 500 7,549.94 · QQQ +3.54% · DIA +2.17% · IWM +3.23% · VIX -22.31% to 19.92 at the close. Percentage changes are versus Friday's close; the S&P 500 and VIX are closing levels.
| Index | Last | Change |
|---|---|---|
| S&P 500 | 7,549.94 | ▲ +173.08 (+2.35%) |
| NASDAQ | 25,253.14 | ▲ +673.72 (+2.74%) |
| DOW JONES | 52,389.75 | ▲ +1,104.02 (+2.15%) |
VIX 19.92 (-22.31%) - breadth was as broad as Friday's was narrow: all 11 sector funds closed higher, led by industrials (+3.82%), while energy lagged (+0.52%); on the Engine List all 7 names finished higher, and 4 of the 7 closed above their 50-day average.
10Y yield 4.86%, unchanged from Friday's 4.86% close · 30Y yield 5.26%, unchanged from Friday's 5.26% close · WTI crude $86.97, -4.25% vs Friday's close · Gold $4,147.50, +1.78% vs Friday's close · Bitcoin $74,878, +0.39% vs the prior close
Sectors into the close: all eleven sector funds finished higher — industrials led (+3.82%) and technology added +3.73%, while energy lagged (+0.52%) on oil's 4.25% slide. Tape as of 16:05 ET.
7 · Morning Thesis Scorecard
Morning edition (05:19 ET) graded against this afternoon's tape. Tape as of 16:05 ET.
| Morning Statement | Evidence | Verdict |
|---|---|---|
| Does the S&P 500 make it two gains in a row today after Thursday's rout — and hold the bounce into Tuesday's inflation print? | The S&P 500 closed at 7,549.94 on Monday, up 173.08 points (+2.35%) from Friday's 7,376.86 — a second straight gain, settled at today's close; whether the bounce holds into Tuesday's print is a separate, still-open leg that grades tomorrow. | Unresolved |
| Morning stance — Dow futures: Sitting on support. | Held all session: Dow futures ranged from 51,878 to 52,676 and never approached the 50,891 prior-week low, finishing the cash session near 52,492 as the cash Dow rose 2.15%. | Confirmed |
| Morning stance — S&P futures: Sitting on support. | Held all session: S&P futures ranged from 7,455.75 to 7,600.50, well above the 7,322.25 prior-week low, and finished the cash session near 7,574.75 as the cash index rose 2.35%. | Confirmed |
| Morning stance — Nasdaq futures: Sitting on support. | Held all session: Nasdaq futures ranged from 27,316.25 to 28,129.25, never testing the 26,366.50 prior-week low, and finished the cash session near 28,020.25 as the Nasdaq Composite rose 2.74%. | Confirmed |
| The S&P 500 closes today above Friday's close of 7,376.86. | The S&P 500 settled Monday at 7,549.94, above Friday's close of 7,376.86 by 173.08 points (+2.35%), on a session that ranged from 7,422.24 to 7,577.39 and never threatened the Friday line. | Confirmed |
| Nvidia closes lower today after Sunday's board announcement. | Nvidia settled Monday at $178.67, down $7.97 (-4.27%) from Friday's close of $186.64, on 455.1 million shares — about 3.9 times its recent average volume — after the board's Sunday investigation announcement. | Confirmed |
Verdicts describe what the tape did against the morning's own words. They are not calls and not advice. Five confirmed, no contradicted, one unresolved — the morning is graded in the open, line by line.
8 · Movers — Top Gainers
FRVO ▲ +26.09% · PRAX ▲ +19.94% · QXO ▲ +19.20% · CECO ▲ +18.97%
8 · Movers — Top Losers
ACAD ▼ -22.28% · IONS ▼ -21.36% · IBRX ▼ -17.66% · ARWR ▼ -15.34%
Movers as of 16:05 ET.
9 · The Engine List
Engine List Closes
Engine List closes as of 16:05 ET
| Symbol | Company | Last | Change |
|---|---|---|---|
| MU | Micron Technology | $733.15 | ▲ +6.25% |
| SNDK | SanDisk | $886.51 | ▲ +6.16% |
| UBER | Uber Technologies | $71.17 | ▲ +3.76% |
| MSFT | Microsoft | $545.18 | ▲ +2.75% |
| AMZN | Amazon | $266.93 | ▲ +2.94% |
| AAPL | Apple | $350.69 | ▲ +2.43% |
| ENB | Enbridge | $47.40 | ▲ +1.09% |
Under their 50-day average at the close: MU, SNDK, ENB.
10 · Engine List Scorecard
How this morning's Engine List names traded against their levels of record - the board's daily and weekly Classic levels off Friday's session:
MU: 12.5% broke, 87.5% not reached. · SNDK: 0.0% broke, 12.5% held, 87.5% not reached. · UBER: 25.0% broke, 75.0% not reached. · MSFT: 25.0% broke, 75.0% not reached. · AMZN: 25.0% broke, 12.5% held, 62.5% not reached. · AAPL: 25.0% broke, 75.0% not reached. · ENB: 0.0% broke, 12.5% held, 87.5% not reached.
11 · Where the Day's Moves Came From
Sectors, Levels & Breadth
The day's sector funds, Monday's close versus Friday's:
| Sector Fund | Today |
|---|---|
| Industrials (XLI) | ▲ +3.82% |
| Technology (XLK) | ▲ +3.73% |
| Consumer discretionary (XLY) | ▲ +2.92% |
| Communication services (XLC) | ▲ +2.45% |
| Health care (XLV) | ▲ +1.91% |
| Materials (XLB) | ▲ +1.91% |
| Utilities (XLU) | ▲ +1.53% |
| Real estate (XLRE) | ▲ +1.45% |
| Financials (XLF) | ▲ +1.45% |
| Consumer staples (XLP) | ▲ +0.90% |
| Energy (XLE) | ▲ +0.52% |
All 11 of the 11 sector funds closed higher. Monday's rally ran through the whole market — industrials and technology did the lifting, and even the laggard, energy, finished higher on a day its commodity fell 4.25%.
12 · Levels Scoreboard. Across 7 names and 56 graded morning levels: 16.1% broke, 5.4% held and 78.6% were not reached. The day's broad rally carried most names up through their first daily resistance: Micron broke one of its eight levels (its first daily resistance) and Uber, Microsoft, Amazon and Apple each broke two, while SanDisk's first daily resistance at $892.63 was tested (the high was $904.00) and held on the close at $886.51.
13 · Breadth and Volume. On the Engine List, 7 of 7 names closed higher and 0 closed lower, and 4 of 7 closed above their 50-day average. Regular-session index volume: SPY 1.05 times, QQQ 1.22 times, DIA 0.92 times, IWM 1.11 times their prior 30-session average.
14 · After-Hours Earnings. After the close today — a heavy calendar, and no major print had landed by the time this edition was built (16:30 ET): Occidental Petroleum (expected EPS $1.47), Rocket Lab, AST SpaceMobile, The Trade Desk, Take-Two Interactive, Hims & Hers Health, Skydance, Credicorp, Equinox Gold, Onto Innovation, Zeta Global and Lineage are all due tonight. Three of the day's biggest regular-session movers were names reporting tonight: Rocket Lab closed +10.91%, AST SpaceMobile +14.10% and The Trade Desk +15.47% — moves made before their prints, not on them.
15 · Setup for Tomorrow. Tuesday: the October consumer price report at 08:30 ET — headline expected up 0.3% in the month and core up 0.2%, with no year-over-year figure published; it is the last inflation reading before the Fed's December 8-9 meeting. Thursday: Cisco and Applied Materials report after the close. Friday: producer prices (Oct) at 08:30 ET. Tuesday Nov 17: Nvidia reports after the close, against $108.0B revenue guidance, with the House briefing request due November 18.
The Final Word
Monday answered Friday's question with the market's best day since April. The S&P 500 rose 2.35% to 7,549.94 and the Nasdaq Composite 2.74%, the Dow added 1,104.02 points, and the VIX fell 22.31% to 19.92 — fear back under 20 for the first time since the selloff — as oil's 4.25% slide took the edge off the inflation fear that Thursday's rout and Friday's jobs beat had built.
The breadth is the story underneath. All eleven sector funds closed higher, industrials leading at +3.82%; all seven Engine List names closed higher, Micron leading at +6.25% to $733.15; and the morning's three futures stances — each sitting on support — all graded Confirmed as support held everywhere. Against that tape, Nvidia's 4.27% fall to $178.67, on the market's heaviest volume, stands out as a company story being priced inside a market rally, not a market turn.
The morning's question stays open on the record: the two-gains-in-a-row leg settled Confirmed at today's close, and the hold-into-Tuesday leg grades tomorrow, so November's record stands at 7 confirmed, 0 contradicted and 1 unresolved across 3 graded sessions. Tomorrow's 08:30 ET consumer price report is now the meeting's last word — a hot print meets an index that has just rallied 2.35% back toward its averages, and a cold one meets a tape that has already spent some of its relief.
What remains unresolved. 1. Does the bounce hold into Tuesday's inflation print?
The Journal Pages
Recent Final Hour Editions
Every Basic edition is free to read — this Final Hour is the page you are on
Advertisement
Education builds conviction
Everything the Journal makes — the free editions, the Pro shelf, the podcast, and the company we keep — gathered on one page. The Pro shelf is the members' shelf on calculateddegens.com — the home of Pro Degenerate at $7.99 a month: the latest edition, the board, the library, scorecards.
The full Pro editions — every weekday morning and the Sunday Pro edition; a full page for every name: charts, levels and the complete read; Fundy's Pick with the full valuation case; Degen Lens scores and LEAPS; delivered on the Pro shelf.
Everything in Pro Degenerate, plus the Discord community — Discord is an Ultimate Degen benefit, not part of Pro — and every edition, complete, as it publishes.
The GEX LEVELS linked from this journal's Lens plates come from FlowState's Trade Desk — the gamma exposure levels behind the names and the index, published by FlowStateOfMind at flowstateofmind.io.
Inside the Pro Edition
Charts, key levels, and fundamentals on every Engine List name, plus the Company Research Comparison names we keep an eye on. PRO DEGENERATE, $7.99/month. New to these terms? Learn the market, plain English.
15 · LEAPS — Pro-Degenerate Only
The LEAPS read rides in the Pro edition. This Final Hour also prints as a PDF — the full edition, page for page. Read the PDF →
The Degenerates Journal is published for research and education purposes only — not financial advice.
In this edition
- The Daily Question, Answered
- The Story
- Data Check
- What Changed Since the Morning
- Today's Standout
- The Index Move
- Morning Thesis Scorecard
- The Engine List
- Engine List Scorecard
- Where the Day's Moves Came From
- Levels Scoreboard
- Breadth and Volume
- After-Hours Earnings
- Setup for Tomorrow
- What Remains Unresolved
- LEAPS
- Education builds conviction — membership