Morning Market Briefing · Basic Edition · Tuesday, November 10, 2026 · South Florida · Filed 05:02 ET
“Bull markets are born on pessimism, grow on skepticism, mature on optimism and die on euphoria.” — John Templeton
- Oil's slide powered the best day since April
- Nvidia fell alone — then the President weighed in
- China's exports surged 35.2% — the AI hardware number
The Degenerates Journal is published for research and education purposes only — not financial advice.
Futures
Futures as of 05:02 ET · VIX early · 10-year at Monday's close · risk 83, Transition regime
The Story
Monday took back the rout in a single session — and did it without its leader. The S&P 500 rose 2.35% to 7,549.94, its best day since April, the Nasdaq Composite rose 2.74% to 25,253.14 and the Dow rose 2.15% to 52,389.75, with all eleven sectors higher and the fear gauge down 22.3% to 19.92. The fuel was oil: WTI crude settled at $86.85, down 4.4%, after President Trump said fresh strikes on Iran were unlikely if negotiations progress — cheaper energy read as cheaper inflation, one day before the October consumer price report. The chip index rose 6.9% as the names Thursday hit hardest led — AMD +13.26%, Lam Research +10.41%, KLA +9.31% — while Nvidia fell 4.27% to $178.67 on its board's investigation, the index's only decliner. The index still closed 1.6% under its 50-day average at 7,676.21, and the risk meter eased only to 83, Transition, because the credit leg is still hot. Futures start Tuesday nearly flat — S&P +0.13%, Nasdaq −0.06%, Dow +0.40% — with the 08:30 ET inflation print holding the day's verdict.
Both sides of Monday — the rally, and the ceiling over it
Monday printed both sides of it. The rally was real: the S&P 500 rose 2.35% in its best session since April, all eleven sectors rose, and the fear gauge fell back under 20. The ceiling is just as real: the index closed at 7,549.94, still 1.6% under its 50-day average at 7,676.21, only three of the nine Engine List names sit above their own 50-day lines, and the risk meter reads 83 in Transition with the credit leg still hot. The print expected at 08:30 ET — headline +0.3%, core +0.2% — is the last inflation reading before the December meeting; a hot core hands the day to the rates leg, a soft one lets the oil-led relief run.
Pre-Market / Overnight Standout
NVDA — NVIDIA +2.1% · The investigation's second day — and the shares take back part of the fall.
Nvidia trades about 2% higher ahead of the bell, near $182.51 against Monday's $178.67 close — a partial retracement of Monday's 4.27% fall, the session's lone decline in a chip index that rose 6.9% on the market's best day since April. Monday's session was the story in full: down 8% at the intraday low on the board's independent investigation into reports that chief executive Jensen Huang was the target of a foreign intelligence effort, then bought back half the fall into the close.
What changed overnight is the weather around the story, not the story. The board said it has no reason to believe any secrets were compromised and expressed confidence in Huang's leadership; President Trump said Monday that Huang should not worry about the FBI looking into his affair with a woman alleged to be a Chinese government agent; China said the espionage allegations are baseless; and at least one analyst desk described the selloff perhaps an overreaction. None of that closes the investigation — the House briefing request is due November 18 and the company's reply is due November 11 — but it reprices the headline from an open-ended governance risk to a dated, answerable one.
The read into the open: Nvidia reports a week from today, after the November 17 close, against guidance of $108.0B of revenue — the print that will decide whether this week was a detour or a derating. Monday's $178.67 close is the line the rebound has to hold; Friday's $186.64 close, the level the shares left when the board spoke, is the reclaim that would say the market has taken the board at its word.
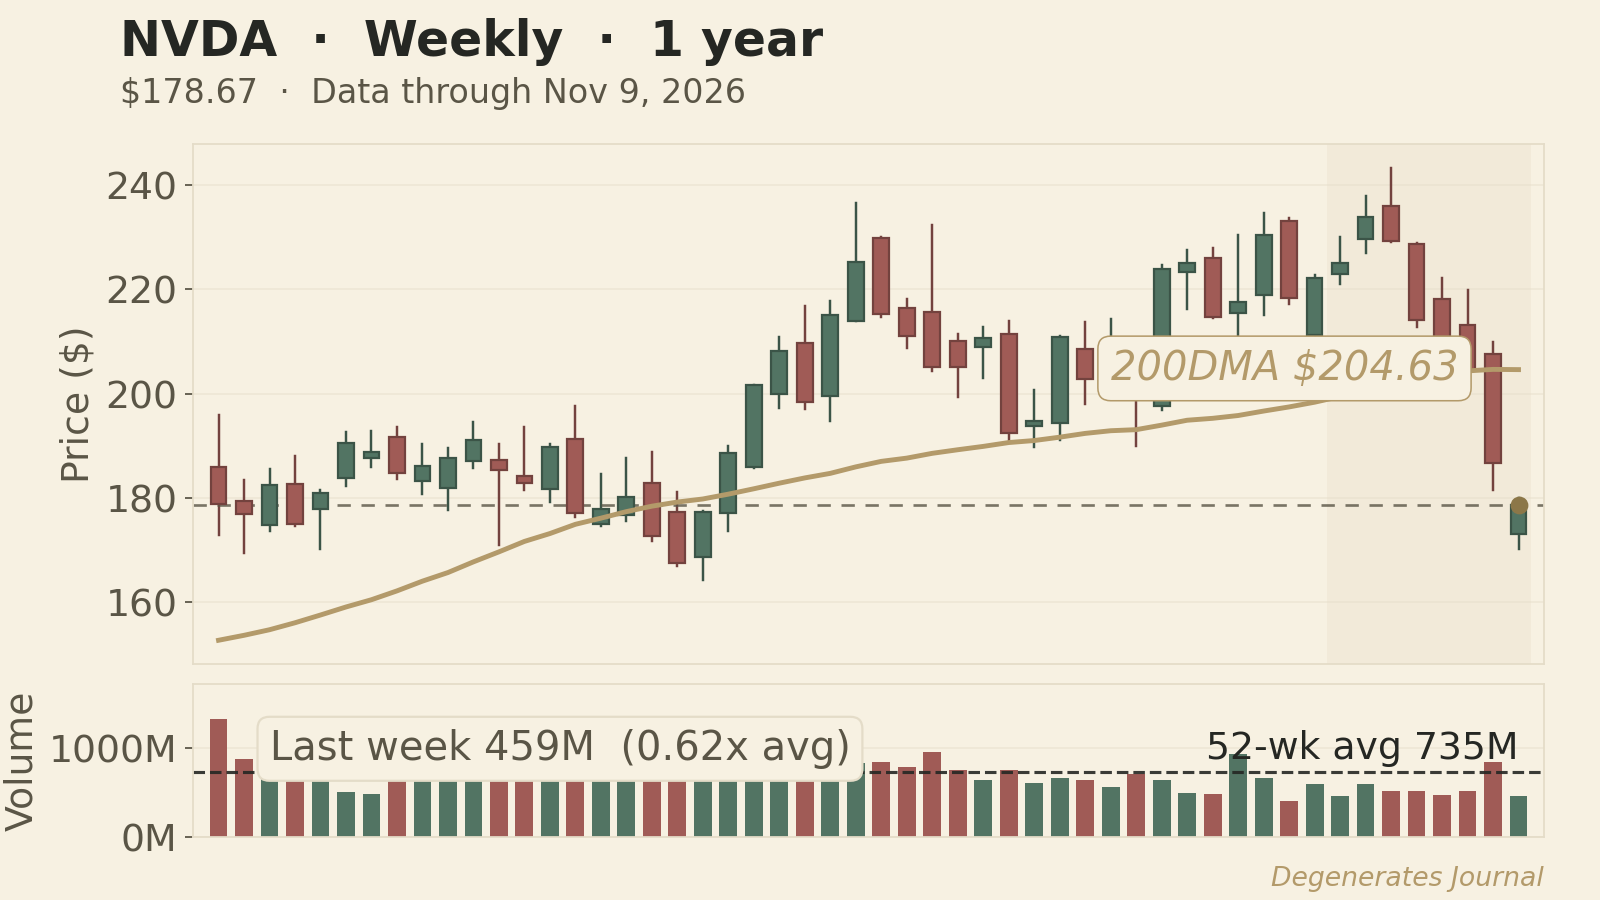
FIG. 1 — NVDA · Weekly candles with the key levels · Data through Monday’s close.
The Engine List
Today's Engine List — the nine names the desk's screens carried into Tuesday, ranked lowest to highest by forward multiple where a multiple is on file, with Monday's closes. The full board, the levels and the Lens reads are Pro.
| Symbol | Company | Last | Change | The take |
|---|---|---|---|---|
| SNDK | SanDisk | $886.51 | +6.2% | SanDisk closed Monday at $886.51 (+6.2%), 40.6% below its 50−day average at 5.2x forward earnings. |
| NVDA | NVIDIA | $178.67 | −4.3% | NVIDIA closed Monday at $178.67 (−4.3%), 18.4% below its 50−day average at 13.0x forward earnings. |
| UBER | Uber Technologies | $71.17 | +3.8% | Uber Technologies closed Monday at $71.17 (+3.8%), 1.7% above its 50−day average at 15.1x forward earnings. |
| LRCX | Lam Research | $221.31 | +10.4% | Lam Research closed Monday at $221.31 (+10.4%), 21.7% below its 50−day average at 21.5x forward earnings. |
| AMD | Advanced Micro Devices | $508.58 | +13.3% | Advanced Micro Devices closed Monday at $508.58 (+13.3%), 7.1% below its 50−day average. |
| KLAC | KLA Corporation | $151.38 | +9.3% | KLA Corporation closed Monday at $151.38 (+9.3%), 13.2% below its 50−day average. |
| NET | Cloudflare | $293.75 | +9.3% | Cloudflare closed Monday at $293.75 (+9.3%), 7.7% below its 50−day average. |
| TXN | Texas Instruments | $295.73 | +6.6% | Texas Instruments closed Monday at $295.73 (+6.6%), 5.7% above its 50−day average. |
| APP | AppLovin | $410.00 | +4.8% | AppLovin closed Monday at $410.00 (+4.8%), 38.9% above its 50−day average. |
Market Health
Degen Risk 83 of 100, Transition regime — computed on Monday's close from the v2 meter: the stress leg cooled hard (the fear gauge at 19.92 against a three-month at 20.85 — the curve back to normal, and the index 1.6% under its 50-day average at 7,676.21), but the credit leg still carries a 4.5% high-yield drawdown from its 252-session high, which is what keeps the score at 83. The score fell from Friday's 96; the regime stepped down from Risk-Off to Transition.
Breadth — how much of the board the rally actually repaired
Breadth on the Engine List: 3 of the 9 Engine List names closed Monday above their own 50-day averages — Texas Instruments, Uber and AppLovin — while the chip rebound's biggest gainers (AMD, Lam Research, KLA) all rose from below their lines. Monday was broad across sectors and narrow across trends: the rally repaired prices faster than it repaired the board's trend base.
Futures Levels
YM — Pressing the week-of-Jul 6 weekly swing high at 53,656 (1.8% away).
ES — Pressing the week-of-Jul 13 weekly swing high at 7,632 (0.6% away).
NQ — Sitting on the week-of-Jul 27 weekly swing low at 27,202 (2.9% away).
The Look Ahead
Today 08:30 ET — Consumer prices (Oct) — The week's key print and the last inflation reading before the December Fed meeting: headline is expected up 0.3% in the month (September: +0.6%) and core up 0.2% (September: +0.3%), Dow Jones consensus. No year-over-year figure will be published — last October's prices were never collected during the government shutdown.
The rest of the week — after-the-bell reports, Thursday's pair, Friday's producer prices and next week's Nvidia print
Today, after the closing bell — CoreWeave reports — The neocloud at the centre of the AI buildout's debt debate reports its third quarter after today's closing bell; analysts expect revenue near $3.54B. Petrobras, the week's largest reporter by market value, also prints after the bell.
Thu, after the closing bell — Cisco and Applied Materials report — Both print after Thursday's close — the chip-equipment read (Applied Materials) lands two sessions after Lam Research's +10.41% Monday.
Fri 08:30 ET — Producer prices (Oct) — The wholesale leg of the inflation pair closes the week's data; the Fed's October meeting minutes follow on November 18 and the PCE report on November 25.
Tue Nov 17, after the closing bell — Nvidia reports — Nvidia's third quarter lands a week from today, against $108.0B of revenue guidance; the House briefing request on the Huang matter is due November 18, with the company's reply due November 11.
Earnings Today
Before the open
- TransDigm Group (TDG)
- Sea Limited (SE)
- Honda Motor (HMC)
- Vodafone Group (VOD)
- Venture Global (VG)
- On Holding (ONON)
- D-Wave Quantum (QBTS)
After the close
- Petrobras (PBR)
- CoreWeave (CRWV)
- Rigetti Computing (RGTI)
- Firefly Aerospace (FLY)
- Grocery Outlet (GO)
- Resideo Technologies (REZI)
Recent Basic Editions
Education builds conviction
Pro Degenerate — $7.99/mo, no free trial: every edition complete as it publishes, the Pro shelf with the Lens board, the Engine List dossiers and the scorecards. Ultimate Degen — $14.99/mo: everything in Pro, plus Discord — Discord is an Ultimate Degen benefit, not part of Pro.
The GEX LEVELS linked from this journal's Lens plates come from FlowState's Trade Desk — the gamma exposure levels behind the names and the index, published by FlowStateOfMind at flowstateofmind.io.
The Degenerates Journal is published for research and education purposes only — not financial advice.
In this edition
- Decision Block
- Yesterday's Tape
- Market Movers
- While You Slept
- Pre-Market / Overnight Standout
- Premarket Movers
- Asset Snapshot
- Market Health
- Economic Calendar
- Earnings Today
- The Engine List
- News That May Affect the Market
- The Strongest Average of the Day
- The Question into the Close
- Education builds conviction — membership