THE DEGENERATES JOURNAL
Friday, November 6 settled closes — the S&P 500 fell 2.68% on the week, from 7,580.07 at the October 30 close, after Thursday's 4.36% rout, the market's worst session since April 2025
Headlines
Jobs beat by 100,000 — October payrolls rose 165K against about 65K expected, and the jobless rate eased to 4.1%
Thursday's 4.36% rout — the worst session since April 2025 — left the S&P 500 down 2.68% for the week at 7,376.86
Friday's bounce only steadied the week — the S&P 500 rose 0.31%, Shopify and the chip names finished higher, and the fear gauge eased to 25.49
May contain typos. Prices may be delayed depending on when the data was collected.
Futures reopened 6:00 PM ET · pulled ~7:12 PM ET · all three flat against Friday's close
01 · The Week in Review
The Week That Was
A free Sunday edition for the Degenerates Journal community.
The week told two stories at once: the sharpest selloff since April on Thursday, then a Friday jobs report firm enough to steady the tape without erasing the loss.
Hiring ran well ahead of the year behind it — a three-month pace near 137,000 a month against 48,000 — and August and September were revised up by 84,000 between them.
Households grew more hopeful, too: sentiment climbed to 51.0 and expected inflation eased to 4.3%, leaving Tuesday's CPI as the last word before the December 8–9 Fed meeting.
The Week at a Glance — Friday's closes
| S&P 500 | 7,376.86 | +0.31% |
| NASDAQ | 24,579.42 | +1.09% |
| DOW JONES | 51,285.73 | -0.46% |
| VIX | 25.49 | -9.55% |
02 · The Data
Econ Addendum
Week ending Nov 6 · Econ data for the week ending November 6, compiled Saturday, November 7.
| Release | Actual | Expected | 2-mo trend | Fundamental read |
|---|---|---|---|---|
| Nonfarm Payrolls (Oct) | +165K | ~+65K | Aug +186K Sep +60K Oct +165K | Hiring re-accelerated: the three-month average runs near +137K against +48K a month over the prior year, and August and September were revised up a combined 84K. |
| Unemployment Rate (Oct) | 4.1% | — | Sep 4.2% Oct 4.1% | The jobless rate eased a tenth in the same report that beat on hiring — demand firmed without the rate rising. |
| Average Hourly Earnings (Oct) | +0.4% m/m | — | Oct +3.1% y/y | Pay growth held at a 3.1% annual pace — firm, and not re-accelerating. |
| Consumer Sentiment, prelim (Nov) | 51.0 | — | Oct 48.0 Nov 51.0 | Households felt better in early November, and year-ahead inflation expectations eased to 4.3% from 4.7%. |
| December Fed Pricing | ~80% for a hike | ~75% before the jobs report | Before the report ~75% After the report ~80% | The strong jobs print moved futures traders toward the December 8-9 hike the committee has been signalling. |
03 · Market Health
Market Health — The Week
Market health as of Friday's close, November 6
| Volatility | The VIX jumped 69.66% to 28.18 in Thursday's rout and eased to 25.49 by Friday's close — still in the twenties, so the fear bid stepped back rather than leaving. |
| Breadth | Narrow all week. Only 12.7% of covered names ended Thursday above their 50-day average, and Friday's bounce stayed concentrated: just 3 of 11 sector funds closed higher, technology led at +1.45% — and the gains sat with Shopify and the position book's chip names. |
| Trend — the Meter | The Degen Meter splits the board into two tapes: Apple, Amazon and Microsoft still read Strong Bullish above their 200-day averages, Shopify reads Mixed at 13, and the other eleven names sit in bearish readings — eight of the fifteen carry washed-out flags after Thursday. |
| The record | November's graded questions stand at 2 Confirmed, 0 Contradicted, 0 Unresolved. Wednesday's question confirmed when the S&P 500 rose 1.58% to 7,688.62, and Friday's — whether the index would finish higher than Thursday — confirmed at 7,376.86 against Thursday's 7,353.73. |
04 · The Record
The Week's Record
Every morning the journal asks one question and grades it against the close. November's graded questions, to date: 2 graded — 2 Confirmed, 0 Contradicted, 0 Unresolved.
Wednesday, November 4 — “Does the S&P 500 close higher today than it did on Tuesday?” Confirmed: the index rose 1.58% to 7,688.62, above Tuesday's close of 7,568.92.
Friday, November 6 — “Does the S&P 500 finish Friday higher than Thursday?” Confirmed: the index closed at 7,376.86, above Thursday's 7,353.73.
05 · Look Ahead
Look Ahead
Calendar compiled Saturday, November 7 from the week's schedule of record.
| Day | Release | Time (ET) |
|---|---|---|
| Mon Nov 9 | No major releases — a light start to the week's data calendarA quiet data day — the week's first report card comes after the close, when Occidental Petroleum reports, and until then the market trades on Friday's bounce. | — |
| Tue Nov 10 | CPI (October) — headline + core, the last inflation print before the Fed's December 8-9 meetingThe week's main event: the last inflation print before the Fed's December 8–9 meeting, with a December hike priced near 80% — a hot number hardens that bet, a cool one reopens the argument. | 8:30 AM |
| Wed Nov 11 | Veterans Day — stock market open, bond market closedVeterans Day thins the session — stocks trade, bonds do not — so Tuesday's inflation print keeps setting the tone for a second day. | — |
| Thu Nov 12 | No major releases — the day belongs to earningsNo major data — the day belongs to earnings. Cisco and Applied Materials report after the close: the week's clearest read on technology spending. | — |
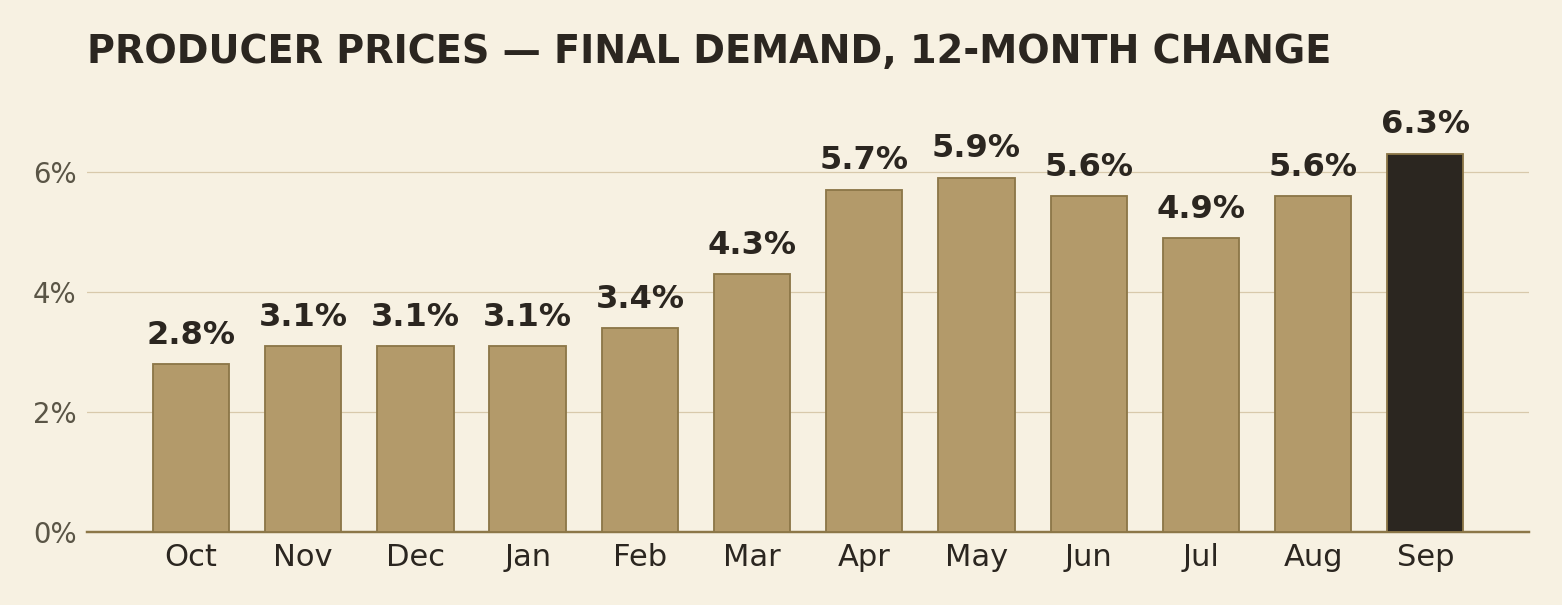
| Fri Nov 13 | PPI (October) — producer pricesProducer prices — what businesses pay for goods before those costs reach the shelf. The week's second inflation read, and its last word before the weekend. | 8:30 AM |
| Symbol | Company | Reports | Timing |
|---|---|---|---|
| OXY | Occidental Petroleum | Mon Nov 9 | After close |
| CSCO | Cisco | Thu Nov 12 | After close |
| AMAT | Applied Materials | Thu Nov 12 | After close |
06 · Standout
The Week's Standout
SHOP — Shopify ▲ +3.59%
Friday close $148.91 · Thursday -6.06% — the list's steepest Thursday drop · the only name on the week's screen to finish Friday higher
Why Shopify stood out On the hardest week the tape has printed since April, Shopify was the screen's only Friday gainer — up 3.59% to $148.91 while the S&P 500 closed the week down 2.68%. Friday's bounce only steadied the week for the index; for SHOP it was the list's single green finish, printed one day after the name took the list's steepest Thursday drop, down 6.06% in the rout.
What the week proved The two-sided week is the read. Thursday's 6.06% fall says the name still trades with the market's fear; Friday's 3.59% recovery — on a day when only three of the eleven sector funds finished higher — says buyers stepped in anyway. The Degen Meter still reads just 13, Mixed, above its 200-day average with the regime flagged extended: on Friday the price improved faster than the trend gauges did.
The business in plain words Shopify sells the storefront and the checkout: the software merchants run their shops on, paid for by subscription and by a cut of what flows through the till. A name like that trades as a high-multiple read on consumer and small-business health — which is why a payrolls report firm enough to steady the whole index, 165,000 jobs against about 65,000 expected, mattered to it directly.
The two sides For: the only green finish on the list, a recovery printed while the bounce stayed narrow, and a Meter regime still above the 200-day average. Against: the board holds the name's value — the settled close sits far beyond the band the model can support, so no base value prints — the Swing and LEAPS lenses score it 39 and 43, and Thursday showed how fast it falls when the tape turns.
What to watch Tuesday's October CPI, at 8:30 AM ET, is the print the December 8–9 Fed meeting turns on, and high-multiple names like SHOP carry the most rate risk into it. The name's own next earnings land in early February, about 89 days out, so into year-end the chart and the tape — not a company print — carry it.
| The week in figures | |
|---|---|
| Friday close | $148.91 |
| Friday's session | +3.59% |
| Thursday's session | -6.06% — the list's steepest Thursday drop |
| The week around it | S&P 500 -2.68% on the week; Thursday's rout was the worst session since April 2025 |
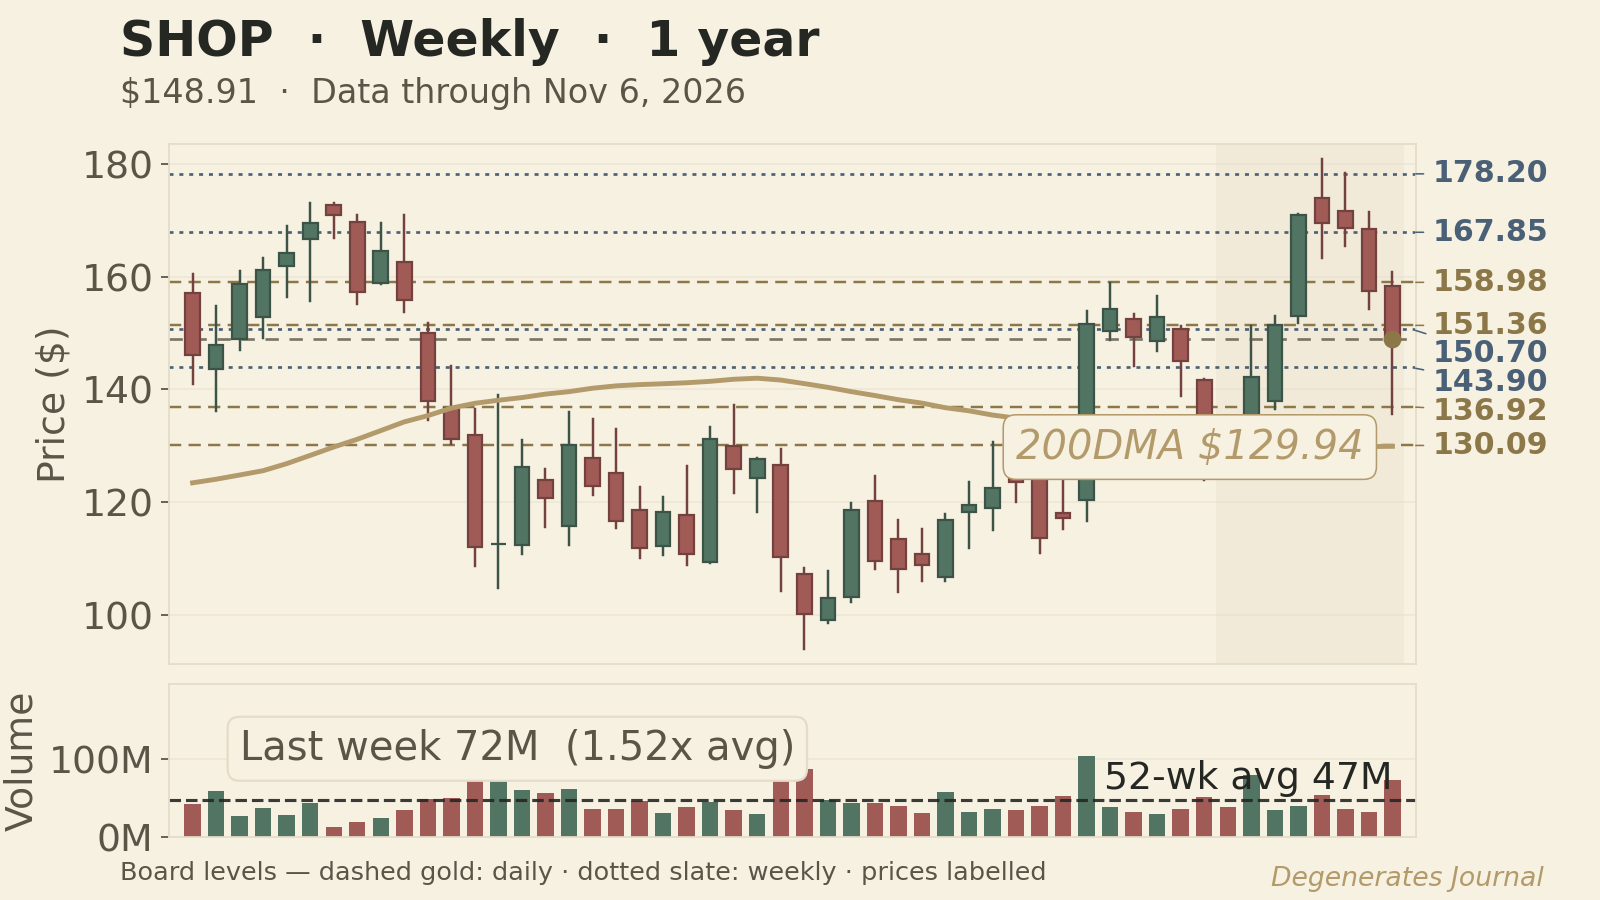
Degen Lens
DEGEN METER — Score 13.0 of ±100 · Mixed
Above its 200-day average · Stretch flag Regime extended
Daily bars through the Fri Nov 6, 2026 close.
Scores out of 100, from the Lens board of record (published Friday, November 6, 14:13 ET, scored on Thursday's settled closes); the chart and the Meter run through Friday's close.
Valuation: Value held by the guard: the settled close sits far beyond the band the model can support, so no value prints.
07 · At Home
What It Means at Home
Work. Employers added 165,000 jobs in October — far more than the roughly 65,000 expected — and the share of people without work eased to 4.1%. More paychecks are being written than the forecasts feared.
The rate behind a mortgage. A new home loan costs about 4.86%. That rate moves with the same December interest-rate decision the market is watching — traders now price a hike at the December 8–9 meeting near 80%, and a hike is the outcome that keeps borrowing dear.
Money in the market. The stock market fell 2.68% on the week, ending at 7,376.86. Most of the damage came in Thursday's 4.36% drop — the worst single day since April 2025 — and Friday's small rise only steadied it.
Nerves. The market's fear gauge closed at 25.49 — calmer than Thursday's spike, but still high enough to say investors are jumpy, not settled.
Prices at the store. Wholesale prices rose 6.3% over the 12 months through September — the largest rise since December 2022. Tuesday's consumer price report shows what is reaching the shelf, and it is the last inflation reading before the December 8–9 Fed meeting — the same decision behind the mortgage rate above.
Going deeper: the Degen Take, Under the Microscope, and The constructive and cautious cases are in the Pro Sunday edition — the full week, analyzed. $7.99/month.
The weekday journal returns Monday at 5:00 AM ET — futures and the tape, fresh every morning.
New to these terms? Learn the market, plain English.
08 · Degen Lens
Degen Lens Ranking
The week's names scored three ways — Swing, LEAPS, and Position — in the Degen Lens Ranking. A score, not a call. The scores live in PRO — $7.99/month, cancel anytime.
Swing reads the week's trend, LEAPS the longer arc, and Position where a name sits against its own range — each scored on settled closes, so the board describes the week that was. A snapshot, not a forecast.
09 · The Journal Pages
Recent Basic Editions
Every Basic edition is free to read — Sunday's is the page you are on
- Morning BasicMon, Nov 9, 2026
- Morning BasicFri, Nov 6, 2026
- Morning BasicThu, Nov 5, 2026
- Morning BasicWed, Nov 4, 2026
- Sunday BasicSun, Nov 1, 2026
- Morning BasicFri, Oct 30, 2026
- Morning BasicWed, Oct 28, 2026
- Morning BasicTue, Oct 27, 2026
- Morning BasicMon, Oct 26, 2026
- Morning BasicFri, Oct 23, 2026
- Morning BasicThu, Oct 22, 2026
- Morning BasicWed, Oct 21, 2026
- The full archive — every edition→
Advertisement
Education builds conviction
The Sunday Basic is free every week — and the weekday Basic edition is free, every morning at 5:00 AM ET. No membership needed. Pro lives on the Pro shelf at calculateddegens.com: the latest edition, the board, the library, scorecards.
The full Pro editions, every weekday morning and Sunday; a full page for every name; Fundy's Pick with the full valuation case; Degen Lens scores and LEAPS.
Everything in Pro Degenerate, plus the Discord community (an Ultimate benefit, not part of Pro), and every edition, complete, as it publishes.
The GEX LEVELS linked from this journal's Lens plates come from FlowState's Trade Desk — the gamma exposure levels behind the names and the index, published by FlowStateOfMind at flowstateofmind.io.
The Podcast
The Degenerates Journal podcast — the Journal in audio: the editions and the deep dives, on Spotify.
The Print Edition
Sunday's Basic also prints as a PDF — the full edition, page for page. Read the PDF →
The Degenerates Journal is published for research and education purposes only — not financial advice.
In this edition
- The Week That Was
- The Week at a Glance
- Econ Addendum — week ending Nov 6
- Market Health — the week
- The Week's Record
- Look Ahead
- What It Means at Home
- Degen Lens Ranking
- Education builds conviction — membership