THE DEGENERATES JOURNAL
Empire State index falls to 7.8 — orders collapse, hiring jumps
Engine List SNDK, NVDA, AVGO, AMD, ANET, DELL
Headlines
S&P 500 -1.92% to 7,416.59 — unwind's third day.
SanDisk -8.58% — Engine List all lower again.
Empire State 7.8 — orders fell, hiring jumped.
VIX 22.91 — fear gauge up 18.7% into the print.
May contain typos. Prices may be delayed depending on when the data was collected.
© 2026 The Degenerates Journal. All rights reserved.
Degen Risk 89/100 · Transition · this morning's reading — as filed in this morning's Basic: basis November 13 equity and credit closes, live volatility at 05:04 ET · Tape as of 16:05 ET · Futures strip as of 16:37 ET: ES 7,442.25 -140.75 (-1.86%) · NQ 27,297.50 -737.25 (-2.63%) · YM 51,689.00 -729.00 (-1.39%)
1 · The Daily Question, Answered
The Daily Question, Answered
“Does Monday hold the complex together into Nvidia's print — the premarket slide stabilising as Empire State and Chair Warsh's remarks land — or does Asia's rout extend the unwind into a third session?”
Into the close — The second leg, in full — and the session's shape is the answer. The complex did not hold together: Asia's rout extended the unwind into a third session, with all six Engine List names lower (SanDisk -8.58%, Dell -6.96%, Advanced Micro Devices -5.58%, Arista Networks -5.21%, Nvidia -4.12% to $156.14, Broadcom -3.92%), the semiconductor fund down 5.41% and the S&P 500 down 1.92% to 7,416.59. The premarket slide never stabilised: the Empire State print missed at 7.8 against a 16.7 consensus, removing the activity offset, and Chair Warsh's remarks addressed artificial intelligence and offered no policy signal. Because the hold failed outright and the extension arrived with its stated cause, the question grades Contradicted — and the complex goes into Tuesday's print having priced three sessions of doubt against it.
2 · The Story
Manufacturing activity in New York State expanded at a much slower pace in November: the Federal Reserve Bank of New York's Empire State headline index fell 18 points to 7.8, from October's 25.5, a multiyear high, against a Wall Street Journal poll consensus of 16.7, Dow Jones reported. The split inside the print ran both ways at once — the new orders index fell to 3.0 from 23.2 and shipments eased to 8.8, while the employment index jumped to 18.1, its highest since June 2022, and the prices paid index fell about 14 points to 45.9. Activity is still expanding — the index holds above zero — but the demand leg of the survey gave back October's surge in one month.
Source: Dow Jones
The chip unwind runs a third session into Nvidia's print. The S&P 500 and the Nasdaq slid more than 1% by midday on an extended selloff in AI-linked stocks, ahead of Nvidia's earnings on Tuesday and Anthropic's expected market debut later in the week, Reuters reported, with sentiment still fragile after founder Jensen Huang's exit last week. The close kept the shape: the semiconductor fund fell 5.41%, memory names led the complex lower — SanDisk fell 8.58% and Micron fell 7.62% — and Nvidia fell a third straight day, down 4.12% to $156.14, closing under its first daily support at $157.49 a day before it reports against $108.0 billion of guided revenue.
Source: Reuters
Warsh talks AI at length — and says nothing about rates. Federal Reserve Chair Kevin Warsh told a one-day conference on AI and productivity at the Fed's San Francisco branch that widespread adoption of the technology will have important implications for monetary policy down the road — and said nothing about the Fed's next steps on interest rates, and nothing about the recent data showing inflation accelerated last month, Fast Company reported. Colleagues have blamed the data-centre build-out for accelerating price increases; the chair did not take up the argument. With December's hike still priced, the session got no offset from the one scheduled Fed voice of the day.
Source: Fast Company
Tyson jumps 8.72% on a beat — and Intel falls 7.02% on a lawsuit. Tyson Foods closed up 8.72% at $63.95 after its fiscal fourth-quarter results, reported before the open, beat Wall Street expectations on both sales and profit, with the company forecasting improvement in its beef business even as it guided fiscal 2027 sales down 3.5% to 5.5%, Investing.com reported. Intel fell the other way, down 7.02% to $55.47, after shareholders filed a proposed class-action lawsuit on Friday accusing the company of misleading investors about weak PC demand and excess inventory, on top of the complex-wide chip selloff. On a day when two of eleven sector funds finished higher, the day's clean winner sold food and its clean loser sold chips.
Source: Investing.com
Tomorrow: retail sales and Home Depot in the morning, Nvidia's print after the close — the interim chief executive's first — with the minutes of the Fed's October meeting on Wednesday.
After the close today — PagSeguro Digital, AECOM and Powell Industries were the evening's scheduled reporters; no after-close print had been verified in full as this edition was built (16:40 ET).
3 · Data Check — November Empire State — the demand leg gives back October's surge
| Year ago | Prior | Expected | Printed | |
|---|---|---|---|---|
| Headline index | — | 25.5 | 16.7 | 7.8 |
| New orders | — | 23.2 | — | 3.0 |
| Shipments | — | 13.1 | — | 8.8 |
| Number of employees | — | 10.3 | — | 18.1 |
| Prices paid | — | 59.5 | — | 45.9 |
| Future business conditions | — | 20.9 | — | 28.9 |
Empire State Manufacturing Survey for November 2026, reported Monday, November 16 at 08:30 ET by the Federal Reserve Bank of New York (responses collected November 2–9). Expected is the Wall Street Journal poll consensus (16.7); the survey consensus this morning's edition carried was 17.6 — the print missed both. October's headline 25.5 was a multiyear high. The future-conditions prior (20.9) is the October reading implied by the release's reported eight-point rise to 28.9.
Degenerates Journal's take. The print splits the same way Friday's producer prices did — the headline and the internals point in different directions, and the edition prints both. On demand, the survey gave back October's surge in one month: the headline fell 18 points to 7.8, new orders fell 20 points to 3.0, barely above zero, and shipments eased to 8.8. On the ground, firms kept hiring: the employment index jumped to 18.1, its highest since June 2022, the average workweek rose, and input-price pressure moderated, with prices paid down about 14 points to 45.9. Firms also looked through the soft month — the future-conditions index rose eight points to 28.9, with close to half expecting conditions to improve. The honest read is a demand air pocket inside an expansion, not a contraction: the index holds above zero, and the hiring and outlook legs argue October was the outlier, not November. What the print did do was remove the morning's activity-resilience support on the one day the tape needed it — and the yield curve did not take the session in its place: the 10-year eased to 5.12% while the VIX rose 18.7%. Monday belonged to the complex, not the curve.
4 · What Changed Since the Morning
| Market | The Turn |
|---|---|
| S&P 500 (SPY) | Futures pointed -0.37% lower at 05:04 ET on Asia's rout; the fund fell -1.91% as the Empire State miss removed the morning's offset and the chip unwind ran a third session |
| Nasdaq-100 (QQQ) | The morning's weakest future (-1.02%) stayed the weakest leg by a wide margin: the fund fell -2.67% as the semiconductor complex sold off in formation into Tuesday's print |
| Dow (DIA) | The morning's only higher future (+0.02%) did not hold: the fund fell -1.43% and the cash Dow fell with the board, though it remained the least-bad major on the day |
| VIX | Priced 20.10 early, the fear gauge rose to 22.91 (+18.70%) — its highest close of this sequence, and the one line that says the third session was not routine |
Friday's defensive rotation gave way to a broad lower close: two of eleven sector funds higher, none of the six Engine List names higher, and the red centred where the week's news is — the AI complex on the eve of its deciding print.
5 · Today's Standout
The Day's Standout and Why
NVDA
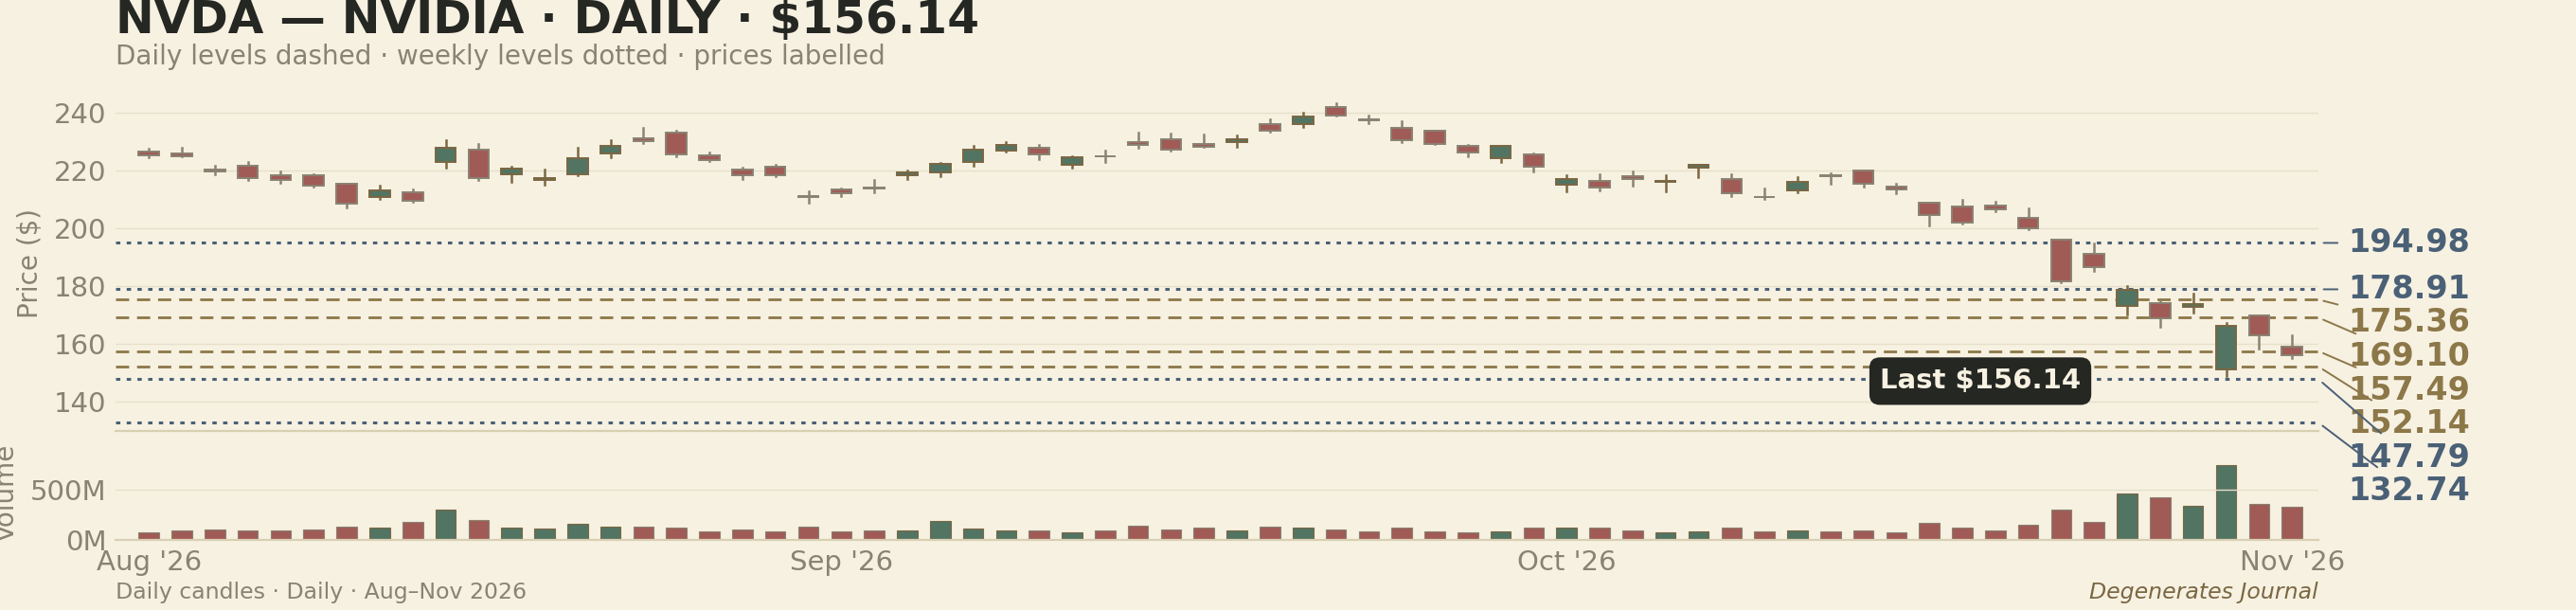
Nvidia (NVDA) - the eve of the print: 4.12% lower on Monday, a third straight down session
$156.14 ▼ -4.12%
Degen Lens Alpha
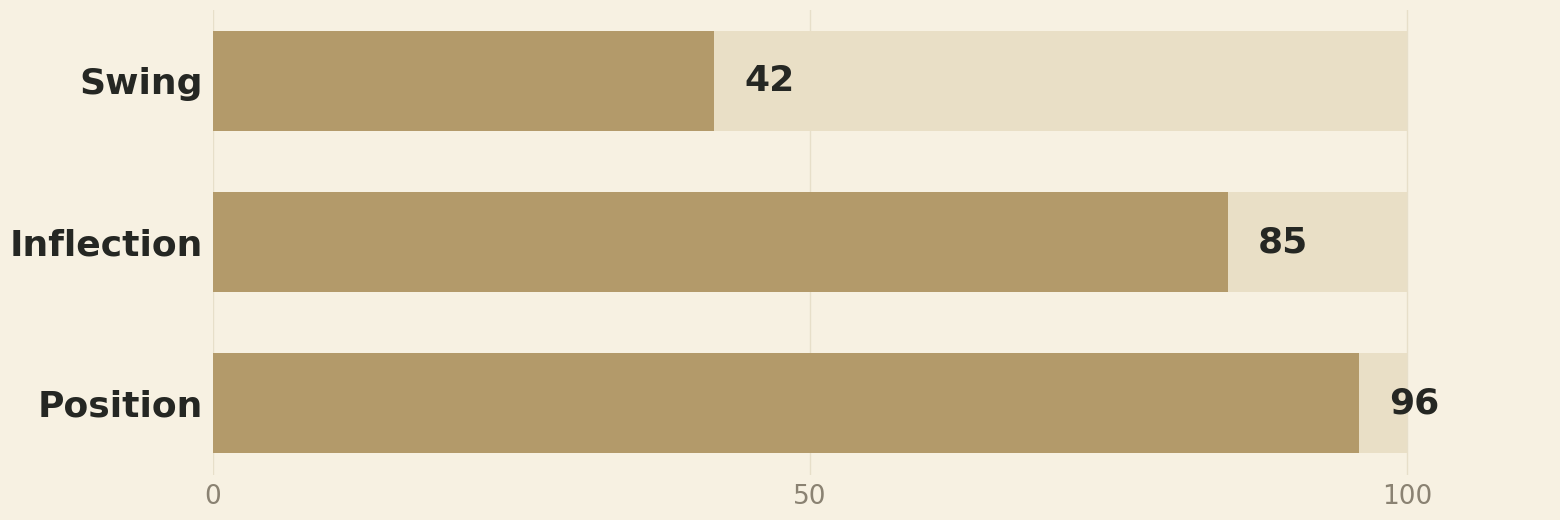
Swing 42 · Inflection 85 · Position 96
Degen Meter
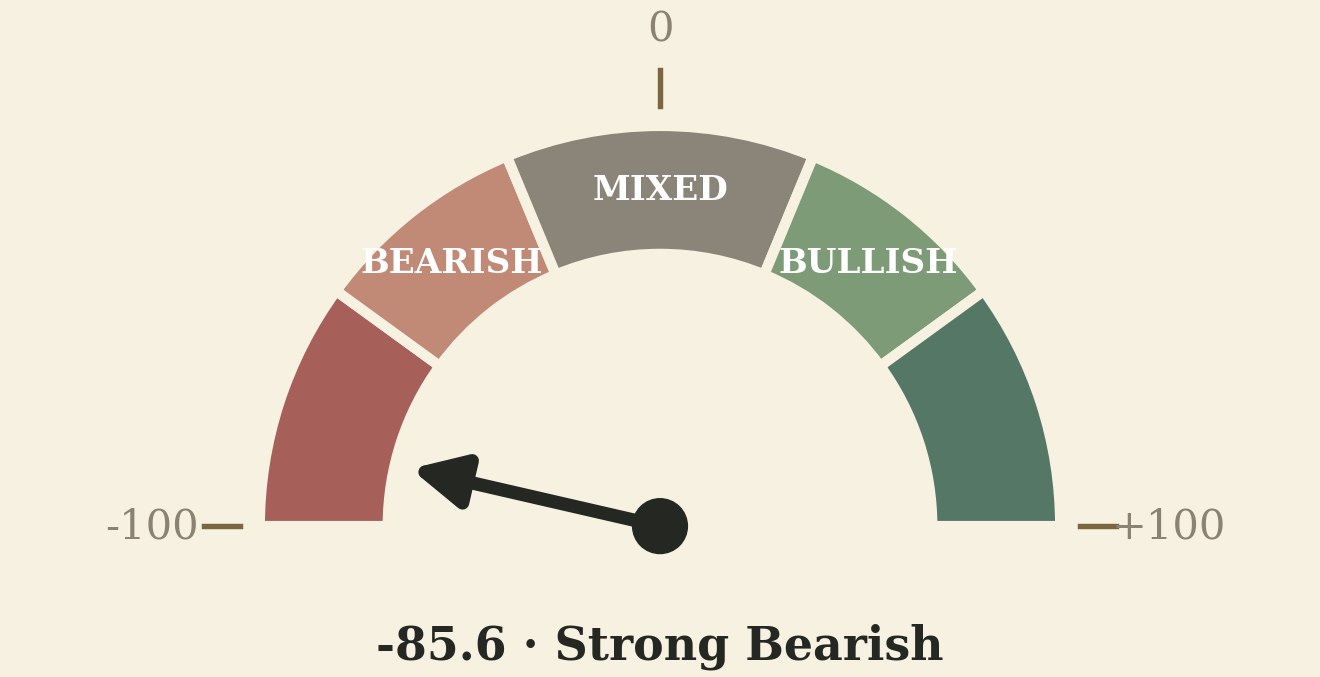
Score -85.6 of ±100 · Label Strong Bearish
Regime: Below its 200-day average · Stretch flag: Washed out
Daily bars through the Mon Nov 16, 2026 close.
Lens scores are the board of record (engine 0.3), scored on the Fri Nov 13 session: Swing 42, Inflection 85 and Position 96 print — a trio average of 74.3, first of sixteen on the board. The LEAPS module prints 96. The chart and the Meter run through today's close.
Why Nvidia stands out. Nvidia (NVDA) fell 4.12% to $156.14 on Monday — its third straight lower close under an interim chief executive, on 326.6 million shares, about 1.9 times its recent average volume — and it did so on the eve of the print the whole complex is priced on. The close broke the first daily support at $157.49 on the board's Classic levels, and the day's $155.01 low held above the second support at $152.14. Monday alone would make it a mover; the calendar makes it the standout: tomorrow after the close, the company reports the first quarter of the post-Huang era against $108.0 billion of guided revenue, and every name in its complex spent Monday positioning for that print by selling.
What happened. The session never had a bid to lose. Asia had already priced the weekend's public succession fight — Taiwan's Taiex closed 6.03% lower with TSMC down 5.7%, South Korea's Kospi fell 3.6% and Japan's Nikkei fell 2.42% — and New York opened where Asia left it: Nvidia opened at $159.00, traded as high as $163.00 in the early going, and slid for the rest of the session to a $155.01 low before closing at $156.14. The complex fell in formation around it — SanDisk −8.58% to $809.11, Dell −6.96% to $320.55, Advanced Micro Devices −5.58% to $504.28, Arista Networks −5.21% to $187.02 and Broadcom −3.92% to $333.40 — while the semiconductor fund lost 5.41%. The morning's two scheduled offsets did not offset: the Empire State manufacturing index printed 7.8 against a 16.7 consensus, and Chair Warsh's remarks at the San Francisco Fed's AI and productivity conference addressed the technology at length and monetary policy not at all. UBS and Mizuho both trimmed their Nvidia price targets in the morning (Benzinga).
The bigger picture. The chart's verdict deepened without changing shape: the close at $156.14 is down 12.61% over five sessions and 28.08% over twenty, and sits 26.75% below the 50-day average of $213.16 and 23.47% below the 200-day average of $204.02. The Degen Meter, run through today's close, reads -85.6 in the Strong Bearish band, below its 200-day average, with the Washed out flag set — deeper than Friday's -81.7. On the Classic levels off Friday's session, the close finished below the daily pivot at $163.75 and under the first daily support at $157.49, with the day's low holding the second support at $152.14; on the weekly levels off the week of Nov 9, the first support at $147.79 — just under Thursday's $148.80 low — is the line the print now trades against.
The business. Nothing in Monday's tape was a verdict on the demand for what Nvidia sells, and last week's evidence still stands in parallel: CoreWeave's backlog above $132 billion, Nebius's 571% revenue growth and Cisco's record quarter all verified the build-out in the same week the shares lost their founder. The board's Lens record for the name, scored on Friday's session under engine 0.3, prints the same split the price keeps widening: Position 96 and Inflection 85 — the long-horizon and expectations reads — against a Swing of 42 and a Meter at -85.6. The business of record and the price of record point opposite ways, and tomorrow's print — delivered by interim chief executive Colette Kress, against $108.0 billion of guided revenue, with a return campaign, a Treasury deadline and a board search all running beside it — is the first evidence that can move both at once.
How to read it — and the outlook. Read Monday as positioning, not verdict. A third straight down session into a known print, on 1.9 times average volume, with the fear gauge up 18.7% and the complex down in formation, is a market paying to reduce exposure before an event — the same market that paid up for the rivals on Thursday and charged them back on Friday. The one constructive fact in the name is where the selling stopped: the $155.01 low held the second daily support, and the close held above it. The unconstructive facts are the trend lines: three lower closes, a close under the first daily support, and a Meter deeper in the Strong Bearish band than at any point in this sequence. On the evidence printed in this edition, the near-term lean on the name stays cautious — the same lean the Meter and the level structure have carried since Thursday, now with a third lower close and a broken first support on top of it. What would change the lean: tomorrow's print itself — the quarter against the $108.0 billion guide, the next quarter's guide, and the China wording under the Treasury's ten-day clock — followed by a close back above the first daily support at $157.49 and then the daily pivot at $163.75, held with the Meter climbing out of the Strong Bearish band. Until then, the name reads as a founder's exit still being priced into the one print that can reprice it back. A description of the printed evidence, for education only - not a recommendation.
6 · The Index Move
The Close
SPY -1.91% · S&P 500 7,416.59 · QQQ -2.67% · DIA -1.43% · IWM -1.66% · VIX +18.70% to 22.91 at the close. Percentage changes are versus Friday's close; the S&P 500 and VIX are closing levels.
| Index | Last | Change |
|---|---|---|
| S&P 500 | 7,416.59 | ▼ -145.08 (-1.92%) |
| NASDAQ | 24,509.76 | ▼ -626.51 (-2.49%) |
| DOW JONES | 51,608.17 | ▼ -739.38 (-1.41%) |
VIX 22.91 (+18.70%) - breadth broke lower: 2 of 11 sector funds closed higher, led by consumer staples (+0.27%), while technology was the weakest fund (-3.24%); on the Engine List none of 6 names finished higher, and none of the 6 closed above its 50-day average.
10Y yield 5.12%, -3.3 bp vs Friday's close — back under Friday's 5.15% print · 30Y yield 5.47%, -1.4 bp vs Friday's close · WTI crude $85.22, -3.77% vs Friday's close · Gold $3,855.90, -0.78% vs Friday's close · Bitcoin $65,191, -0.18% vs the prior completed bar (Nov 14)
Sectors into the close: two of the eleven sector funds finished higher — consumer staples led, up 0.27% — while technology fell 3.24% at the back of a board that sold the complex in formation. Tape as of 16:05 ET.
7 · Morning Thesis Scorecard
Morning edition (05:04 ET) graded against this afternoon's tape. Tape as of 16:05 ET.
| Morning Statement | Evidence | Verdict |
|---|---|---|
| Does Monday hold the complex together into Nvidia's print — the premarket slide stabilising as Empire State and Chair Warsh's remarks land — or does Asia's rout extend the unwind into a third session? | The complex did not hold, and the extension leg completed with its stated cause. Asia's Monday rout — Taiwan's Taiex -6.03%, South Korea's Kospi -3.6%, Japan's Nikkei -2.42% — ran straight through the New York session: all six Engine List names closed lower for a third straight session (SanDisk -8.58%, Dell -6.96%, Advanced Micro Devices -5.58%, Arista Networks -5.21%, Nvidia -4.12%, Broadcom -3.92%), the semiconductor fund fell 5.41%, and the S&P 500 fell 1.92% to 7,416.59. The stabilisers the first leg needed never arrived: the Empire State index missed at 7.8 against a 16.7 consensus, and Chair Warsh's noon remarks offered no policy offset. The hold failed outright, so the question grades Contradicted. | Contradicted |
| Morning stance — Dow futures: Sitting on support. | Tested, pierced and recovered: Dow futures ranged 51,574 to 52,419 in the cash session — the low 56 points under the 51,630 weekly swing low of the week of Jul 27 — and finished near 51,667, back above the support, as the cash Dow fell 1.41%. | Confirmed |
| Morning stance — S&P futures: Sitting on support. | Tested, pierced and lost: S&P futures fell to 7,420.25 in the cash session — 89.00 points under the 7,509.25 weekly swing low of the week of Sep 14 — and finished near 7,439.50, below the support, as the cash index fell 1.92% to 7,416.59. | Contradicted |
| Morning stance — Nasdaq futures: Sitting on support. | Never tested: Nasdaq futures ranged 27,234.75 to 27,716.25 in the cash session — the low still 33.25 points above the 27,201.50 weekly swing low of the week of Jul 27 — and finished near 27,309.25 as the Nasdaq Composite fell 2.49%. | Confirmed |
| The S&P 500 closes today above Friday's close of 7,561.67. | The S&P 500 settled Monday at 7,416.59, below Friday's close of 7,561.67 by 145.08 points (-1.92%), on a session that ranged from 7,400.15 to 7,515.60 and closed near the low. | Contradicted |
| Nvidia closes today above Friday's close of $162.85. | Nvidia settled Monday at $156.14, down $6.71 (-4.12%) from Friday's close of $162.85, on 326.6 million shares — about 1.9 times its recent average volume — after opening at $159.00, trading as high as $163.00 and as low as $155.01 in its third session under an interim chief executive. | Contradicted |
Verdicts describe what the tape did against the morning's own words. They are not calls and not advice. Two confirmed, four contradicted, no unresolved — the morning is graded in the open, line by line.
8 · Movers — Top Gainers
CGON ▲ +13.95% · TU ▲ +12.19% · MOH ▲ +11.27% · HTHT ▲ +8.91%
8 · Movers — Top Losers
SMMT ▼ -16.47% · GDS ▼ -14.69% · USAR ▼ -12.62% · ASTS ▼ -12.33%
Movers as of 16:05 ET.
9 · The Engine List
Engine List Closes
Engine List closes as of 16:05 ET
| Symbol | Company | Last | Change |
|---|---|---|---|
| SNDK | SanDisk | $809.11 | ▼ -8.58% |
| NVDA | NVIDIA | $156.14 | ▼ -4.12% |
| AVGO | Broadcom | $333.40 | ▼ -3.92% |
| AMD | Advanced Micro Devices | $504.28 | ▼ -5.58% |
| ANET | Arista Networks | $187.02 | ▼ -5.21% |
| DELL | Dell Technologies | $320.55 | ▼ -6.96% |
All six Engine List names closed under their 50-day average — Broadcom, the last name above its line on Friday, lost its 50-day average today.
10 · Engine List Scorecard
How this morning's Engine List names traded against their levels of record - the board's daily and weekly swing levels printed in this morning's Pro:
SNDK: 0.0% broke, 33.3% held, 66.7% not reached. · NVDA: 0.0% broke, 100.0% not reached. · AVGO: 50.0% broke, 50.0% not reached. · AMD: 0.0% broke, 25.0% held, 75.0% not reached. · ANET: 0.0% broke, 25.0% held, 75.0% not reached. · DELL: 33.3% broke, 66.7% not reached.
11 · Where the Day's Moves Came From
Sectors, Levels & Breadth
The day's sector funds, Monday's close versus Friday's:
| Sector Fund | Today |
|---|---|
| Consumer staples (XLP) | ▲ +0.27% |
| Utilities (XLU) | ▲ +0.18% |
| Real estate (XLRE) | ▼ -0.27% |
| Health care (XLV) | ▼ -0.51% |
| Financials (XLF) | ▼ -0.85% |
| Materials (XLB) | ▼ -1.46% |
| Consumer discretionary (XLY) | ▼ -1.53% |
| Communication services (XLC) | ▼ -1.72% |
| Industrials (XLI) | ▼ -1.85% |
| Energy (XLE) | ▼ -1.96% |
| Technology (XLK) | ▼ -3.24% |
2 of the 11 sector funds closed higher. Monday unwound Friday's defensive shape: the selling centred on the complex carrying the week's news — technology fell 3.24%, the weakest fund, with energy down 1.96% beside it — while only the two classic defensives, consumer staples (+0.27%) and utilities (+0.18%), finished higher, and the Dow, the least technology-heavy major, fell least of the three majors.
12 · Levels Scoreboard. Across 6 names and 20 graded morning levels: 15.0% broke, 15.0% held and 70.0% were not reached. Broadcom broke both of its levels below — the weekly swing low at $335.81 and the daily swing low at $343.29 — and closed at $333.40. Dell broke its daily swing low at $321.25 to close at $320.55. Three touches held on the close: SanDisk tested its daily swing low at $803.97 and closed at $809.11, Advanced Micro Devices tested its daily swing low at $502.60 and closed at $504.28, and Arista Networks tested its daily swing low at $186.11 and closed at $187.02.
13 · Breadth and Volume. On the Engine List, 0 of 6 names closed higher, and 0 of 6 closed above their 50-day average — Broadcom, the last name above its line on Friday, closed under it on Monday. Regular-session index volume: SPY 1.48 times, QQQ 0.92 times, DIA 0.93 times, IWM 1.03 times their prior 30-session average — a heavy session in the names carrying the week's news, led by Nvidia's 326.6 million shares.
14 · After-Hours Earnings. After the close today — PagSeguro Digital, AECOM and Powell Industries were the evening's scheduled reporters from this morning's calendar. As this edition was built (16:40 ET), early after-hours prints showed AECOM at $77.00 (16:39 ET) against a $72.50 regular close, Powell Industries at $152.00 against a $151.20 close and PagSeguro Digital at $8.07 against a $7.99 close — price prints only; no after-close earnings figure is printed here until the release itself is verified. The day's verified earnings news had landed in daylight: Tyson Foods rose 8.72% on its before-open beat.
15 · Setup for Tomorrow. SETUP FOR TOMORROW — Tuesday, November 17 is the week's hinge: retail sales for October print at 08:30 ET (the consensus split this morning's edition printed — +0.2% and 0.0% by carrier — not a blend), Home Depot reports before the open, and after the close Nvidia reports its fiscal third quarter against $108.0 billion of guided revenue — the first print of the post-Huang company, presented by interim chief executive Colette Kress (Nvidia company releases; this morning's calendar). Wednesday, November 18: the Federal Reserve publishes the minutes of its October 27–28 meeting at 14:00 ET (Federal Reserve), with housing starts the same morning. Thursday, November 19: Walmart reports before the open (company announcement), weekly jobless claims and the Philadelphia Fed survey print in the morning, and Anthropic is expected to begin trading on the Nasdaq after a Wednesday pricing (Barron's, via this morning's edition). The December Fed meeting sits on December 8–9 (Federal Reserve).
The Final Word
The week opened the way the weekend said it would. Friday's question was whether the complex could price Nvidia without its founder; the weekend made the founder's return a public campaign at the same moment the Treasury demanded the opposite, and Asia's Monday verdict — Taiwan down 6.03%, Korea down 3.6%, Japan down 2.42% — turned out to be New York's verdict too. Three sessions into the interim regime, the complex has now fallen in formation three times: Thursday's redistribution, Friday's hand-back, and Monday's extension, each one broader than the last — Friday left seven sector funds higher, Monday left two.
The day's evidence split the way this month's evidence keeps splitting. The demand record did not break on Monday — nothing in the Empire State's hiring leg (18.1, a four-year high), in last week's CoreWeave, Nebius and Cisco prints, or in Tyson's beat says the build-out or the consumer rolled over. What broke was the price of exposure to the complex into its deciding event: the VIX at 22.91, the semiconductor fund down 5.41%, every Engine List name under its 50-day average for the first time in this sequence, and the morning's graded record taking four contradicted lines against two confirmed — November stands at 18 confirmed, 16 contradicted and 4 unresolved across 8 graded sessions.
Everything that matters next is dated inside the next three sessions, and it all runs through one interim chief executive. Retail sales and Home Depot grade the consumer on Tuesday morning; on Tuesday evening Nvidia reports the quarter the whole complex is priced on — $108.0 billion of guided revenue — with Colette Kress presenting it; the Fed's October minutes land Wednesday; Walmart and Anthropic's debut close the week on Thursday. Three sessions of selling have now been charged against a print that has not happened yet. What the week is repricing — in the shares, in the fear gauge, and in the chair at the top of its most important company — is who the market is being asked to trust to deliver it, and Tuesday's print is the first answer that comes with numbers attached.
What remains unresolved. 1. Does the give-back become a full hand-back — or does Monday's rally stand into the December meeting?
The Journal Pages
Recent Final Hour Editions
Every Basic edition is free to read — this Final Hour is the page you are on
Advertisement
Education builds conviction
Everything the Journal makes — the free editions, the Pro shelf, the podcast, and the company we keep — gathered on one page. The Pro shelf is the members' shelf on calculateddegens.com — the home of Pro Degenerate at $7.99 a month: the latest edition, the board, the library, scorecards.
The full Pro editions — every weekday morning and the Sunday Pro edition; a full page for every name: charts, levels and the complete read; Fundy's Pick with the full valuation case; Degen Lens scores and LEAPS; delivered on the Pro shelf.
Everything in Pro Degenerate, plus the Discord community — Discord is an Ultimate Degen benefit, not part of Pro — and every edition, complete, as it publishes.
The GEX LEVELS linked from this journal's Lens plates come from FlowState's Trade Desk — the gamma exposure levels behind the names and the index, published by FlowStateOfMind at flowstateofmind.io.
Inside the Pro Edition
Charts, key levels, and fundamentals on every Engine List name, plus the Company Research Comparison names we keep an eye on. PRO DEGENERATE, $7.99/month. New to these terms? Learn the market, plain English.
15 · LEAPS — Pro-Degenerate Only
The LEAPS read rides in the Pro edition. This Final Hour also prints as a PDF — the full edition, page for page. Read the PDF →
The Degenerates Journal is published for research and education purposes only — not financial advice.
In this edition
- The Daily Question, Answered
- The Story
- Data Check
- What Changed Since the Morning
- Today's Standout
- The Index Move
- Morning Thesis Scorecard
- Engine List Scorecard
- Where the Day's Moves Came From
- Levels Scoreboard
- Breadth and Volume
- After-Hours Earnings
- Setup for Tomorrow
- The Final Word
- What Remains Unresolved
- LEAPS
- Education builds conviction — membership