Morning Market Briefing · Basic Edition · Monday, November 16, 2026 · South Florida · Filed 05:04 ET
“Take a simple idea and take it seriously.” — Charlie Munger
- Asia's chip rout opens the week as Nvidia's print looms
- Bessent demands a “dramatic shakeup” at Nvidia, an outside chief executive
- The Huang return campaign: a petition past 168,000 and an FT report
The Degenerates Journal is published for research and education purposes only — not financial advice.
Futures
Futures as of 05:04 ET · VIX early · 10-year at Friday's 5.15% close · risk 89, Transition regime · Lens board as of Friday's close.
The Story
The succession fight went public over the weekend, and Asia priced it before New York woke. The Financial Times reported Sunday that Jensen Huang has discussed returning as Nvidia's chief executive with allies organising to press the board, while Treasury Secretary Scott Bessent demanded an outside chief executive, a “dramatic shakeup” and compliance answers within ten days. Sunday futures rose on the first report and faded on the second; on Monday Taiwan's Taiex closed 6.03% lower, South Korea's Kospi 3.6% lower and Japan's Nikkei 2.42% lower, with TSMC down 5.7% and SK Hynix down 7.9%. Friday had already reversed the rotation in full — Advanced Micro Devices −8.75%, Dell −7.18%, SanDisk −5.59%, Broadcom −4.76% and Arista Networks −4.52%, Nvidia fell a second day to $162.85, and the semiconductor index dropped 3.43% — yet the S&P 500 still closed the week up 2.51% at 7,561.67, its best week since early August. Nvidia trades near $159.43 ahead of the bell, down about 2.1%, and reports tomorrow following the closing bell against $108.0 billion of guided revenue — the first print of the post-Huang company, now with a campaign to undo the post-Huang part running alongside it.
What matters most today — a public succession fight at Nvidia, an Empire State print at 08:30 ET and Chair Warsh at noon
Friday printed the reversal in full: the semiconductor index down 3.43%, the reclaim names down 4.5% to 8.8%, Nvidia down a second day to $162.85, and the index still up 2.51% on the week. The weekend then made the leadership fight public in both directions — a reported return campaign and a Treasury demand for an outsider — and Asia answered with its worst chip session of the season: Taiwan −6.03%, Korea −3.6%, Japan −2.42%. Nvidia trades about 2.1% lower premarket near $159.43 and the Engine List complex is down 3.3% to 5.4%. A session that stabilises here is a market waiting for Tuesday's numbers; a session that extends the slide is a market pricing the institution before the numbers arrive.
Pre-Market / Overnight Standout
NVDA — NVIDIA −2.1% · The fight for Nvidia went public — a return campaign, a Treasury deadline, and Asia's verdict first.
Nvidia trades about 2.1% lower ahead of the bell, near $159.43 against Friday's $162.85 close, after a weekend that turned its succession into a public contest. The Financial Times reported Sunday that Jensen Huang has discussed returning as chief executive with confidants, with allies organising to press the board; a petition to bring him back reached 168,000 signatures by Monday, including more than 8,000 current employees. Treasury Secretary Scott Bessent told Fox News the board should go outside the company, deliver a “dramatic shakeup” and answer questions about export-control compliance within ten days. Neither campaign is a decision: no return has been announced, Colette Kress remains interim chief executive, and Reuters notes the board has separately approached Arm chief executive Rene Haas as a potential successor — a third name in a contest that, as of this morning, has a campaign, a deadline and a candidate but no decision.
Asia priced the fight before New York could. Taiwan's Taiex closed 6.03% lower on Monday with TSMC down 5.7%; South Korea's Kospi fell 3.6% with SK Hynix down 7.9% and Samsung Electronics down 4.5%; Japan's Nikkei fell 2.42% with Tokyo Electron down 7.1%. Sunday futures traced the same argument in miniature — higher on the return report in the evening, lower after Bessent, and lower still into Monday's premarket, with Nasdaq futures down about 1.0% at 05:04 ET. The weekend's two headlines pointed in opposite directions; three Asian markets read them the same way. Bitcoin printed the same risk-off signature in the one market that never closes: it fell to $62,006 on Saturday evening, its lowest since July, before recovering to a $65,351 weekly close on Sunday — a break and a recovery that left the weekend's equity argument exactly where Asia found it on Monday.
The argument gets its first numbers tomorrow. Nvidia reports its fiscal third quarter following Tuesday's closing bell against revenue guidance of $108.0 billion plus or minus 2% at a 74.0% gross margin, with no China Data Center compute revenue assumed; consensus sits at $108.84 billion and $2.47 a share, with the revenue estimates running from $107.86 billion to $112.35 billion — a range wide enough that the guide itself, not the quarter, is the number the print will be graded against — and Reuters reports options imply about a 7% move on the print. It is the first report of the post-Huang company — delivered by the interim chief executive both campaigns are arguing over — and the next quarter's guide, the China wording under a ten-day Treasury clock, and any word on the permanent search will decide more than the quarter itself.
The map from here runs through Friday's levels. The close at $162.85 sits between daily support at $157.49 and daily resistance at $169.10 on the board's record, with weekly support at $147.79 — near Thursday's $148.80 low — and weekly resistance at $178.91 below Monday of last week's close. The Lens still ranks the name first of sixteen at a 74.3 trio average — Inflection 85 and Position 96 against a Swing score of 42 — while the per-name Meter reads −81.7, Strong Bearish and washed out. The business of record and the price of record point opposite ways into the print, and the weekend added a third line to the chart: who runs the company is now a public question with a Treasury deadline attached.
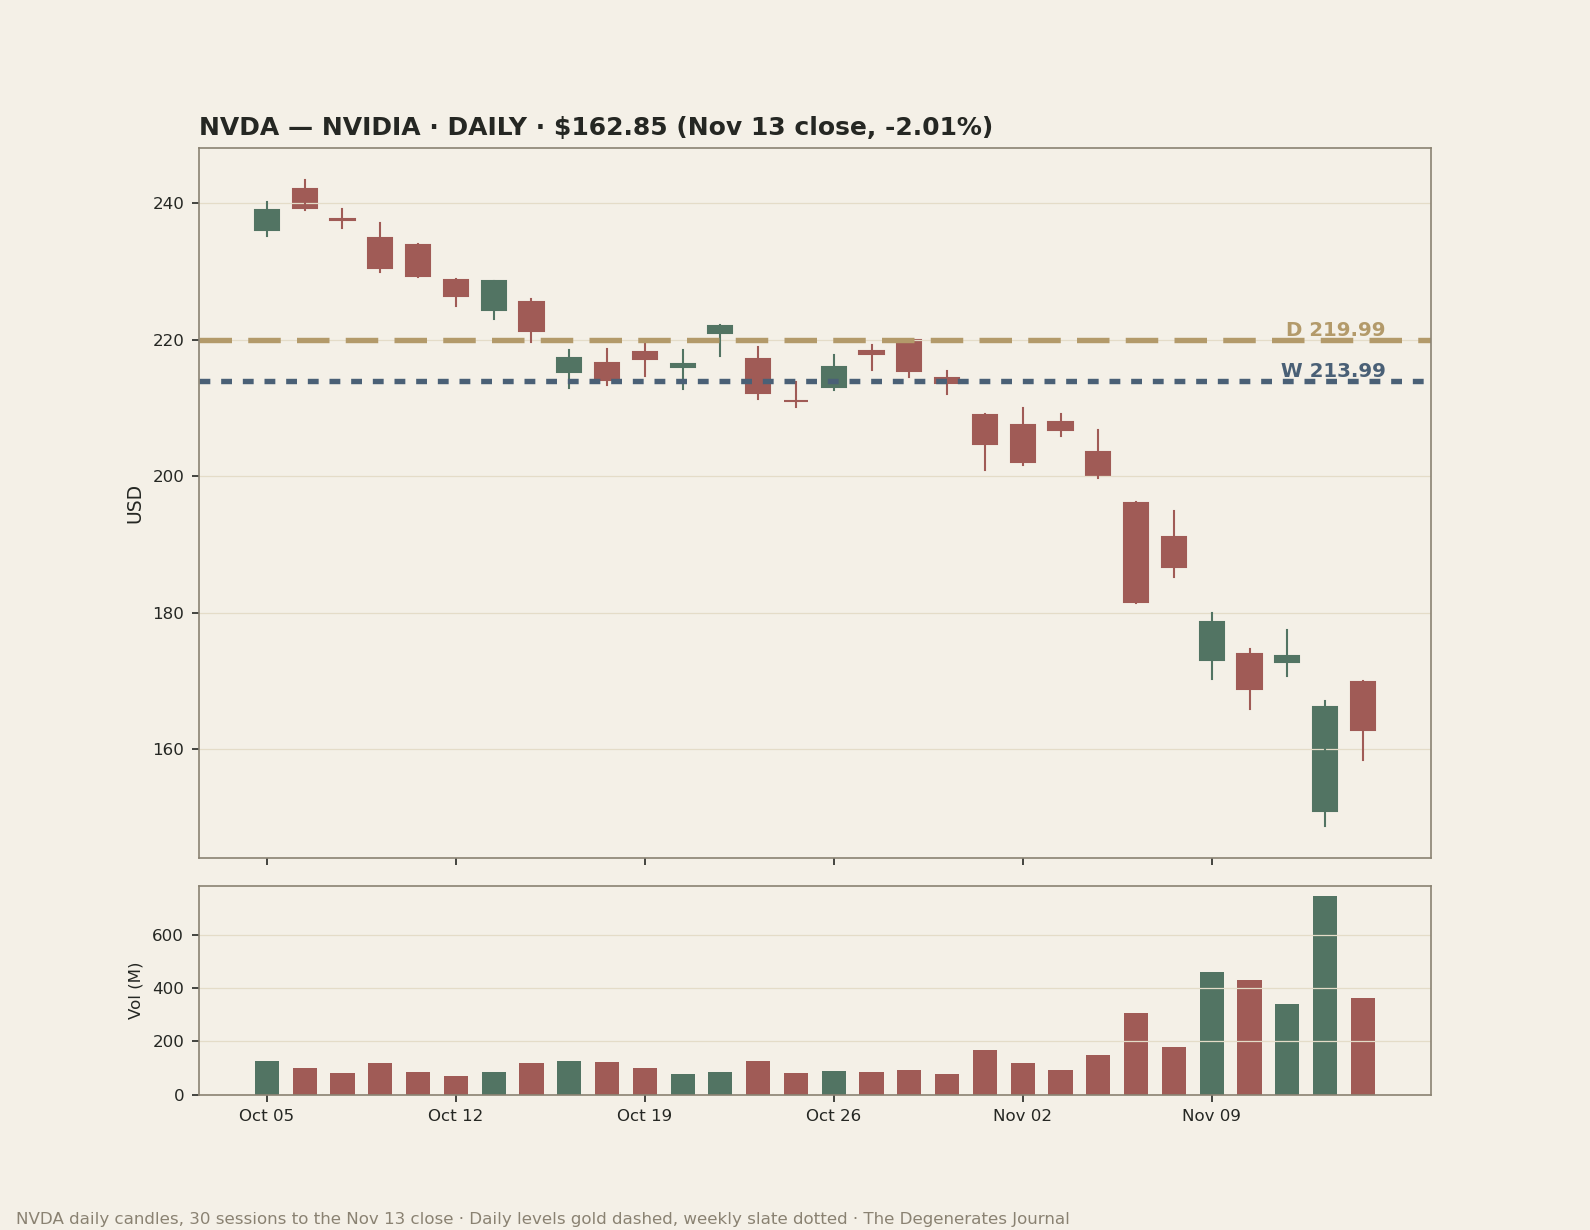
FIG. 1 — NVDA · Daily candles with the key levels · Data through Friday’s close.
The Engine List
Today's Engine List — six names the desk's screens carried into Monday, ranked lowest to highest by forward multiple where a multiple is on file, with Friday's closes. The full board, the levels and the Lens reads are Pro.
| Symbol | Company | Last | Change | The take |
|---|---|---|---|---|
| SNDK | SanDisk | $885.01 | −5.6% | SanDisk closed Friday at $885.01 (−5.6%), 38.6% below its 50−day average at 5.2x forward earnings. |
| NVDA | NVIDIA | $162.85 | −2.0% | NVIDIA closed Friday at $162.85 (−2.0%), 24.1% below its 50−day average at 11.9x forward earnings. |
| AVGO | Broadcom | $347.01 | −4.8% | Broadcom closed Friday at $347.01 (−4.8%), 0.5% above its 50−day average at 20.0x forward earnings. |
| AMD | Advanced Micro Devices | $534.06 | −8.8% | Advanced Micro Devices closed Friday at $534.06 (−8.8%), 3.7% below its 50−day average. |
| DELL | Dell Technologies | $344.53 | −7.2% | Dell Technologies closed Friday at $344.53 (−7.2%), 30.2% below its 50−day average. |
| ANET | Arista Networks | $197.29 | −4.5% | Arista Networks closed Friday at $197.29 (−4.5%), 2.3% above its 50−day average. |
Market Health
Degen Risk 89 of 100, Transition regime — computed on Friday's close from the v2 meter, up 2 points from Thursday's 87: the fear gauge rose to 19.30, the index closed further under its 50-day average (7,561.67 against a 7,667.46 average), and the credit leg has still not cooled — high-yield sits about 5.2% below its 252-session high. The meter's rise was modest because Friday's stress, like Thursday's, was concentrated: one complex unwinding its own rotation while five of eight non-chip sectors rose and the Dow closed green.
Breadth and the day's shape — three of six Engine List names above their 50-day averages; Friday's unwinding was complex-wide while the index held its week
Breadth on the Engine List: 1 of the 6 Engine List names closed Friday above its own 50-day average — Broadcom, by 0.5% — while Nvidia closed 24.1% below its average, SanDisk 38.6% below and Dell deep below its line after the week's round trip. Friday's tape was the mirror of Thursday's: the value that left the centre on Thursday left the rivals on Friday, and the week's net was an index up 2.51% with its leadership less settled than it was on Monday.
The weekend added a second axis to the week. Friday's question was whether the complex could price Nvidia without its founder; the weekend's reporting made the founder's return a live campaign at the same moment the Treasury Secretary demanded the opposite — an outside chief executive and compliance answers within ten days. Asia's Monday closes (Taiwan −6.03%, Korea −3.6%, Japan −2.42%) are the first full-session verdict on that fight, and they were not ambiguous.
Futures Levels
YM — Sitting on the week-of-Jul 27 weekly swing low at 51,630 (1.5% away).
ES — Sitting on the week-of-Sep 14 weekly swing low at 7,509 (0.6% away).
NQ — Sitting on the week-of-Jul 27 weekly swing low at 27,202 (2.0% away).
The Look Ahead
Today 08:30 ET — Empire State manufacturing (Nov) — The week's first U.S. print: consensus 17.6 against October's 25.5, a near-five-year high (New York Fed schedule; survey consensus). Chair Warsh gives opening remarks at 12:00 ET and New York's Williams speaks this morning — the voices around the number matter as much as the number with December's size still formally open.
The rest of the week — retail sales and Nvidia's print Tuesday, Fed meeting minutes Wednesday, claims and Walmart Thursday, and the December Fed meeting
Tue Nov 17, after the closing bell — Nvidia reports, and retail sales print — Nvidia's quarter lands tomorrow against $108.0B of revenue guidance — the first print of the post-Huang company, delivered by interim chief executive Colette Kress, with a return campaign and a Treasury deadline now running beside it. October retail sales (consensus splits +0.2% and 0.0% by carrier — the edition prints the split, not a blend) and Home Depot's report land the same day.
Wed Nov 18 — Fed meeting minutes, housing data, the testimony question — The October Fed meeting minutes publish at 14:00 ET — the meeting that held at 3.75–4.00% by 10–2 with dissents for a hike — with housing starts and pending home sales the same day, and the briefing date the House committee chairs requested arriving with attendance by Huang still unconfirmed.
Thu Nov 19 — claims, Philadelphia Fed, Walmart — Weekly claims (consensus 199,000) and the Philadelphia Fed survey (consensus 19.2) print Thursday morning, with Walmart reporting ahead of the session — its earnings consensus of $0.64 sits at the top of the company's own $0.62–$0.64 guide.
Tue–Wed Dec 8–9 — the December Fed meeting — The meeting December pricing treats as a certain hike of an open size: decision Wednesday December 9 at 14:00 ET with the dot plot (Federal Reserve calendar). The next producer print lands December 15 — after the meeting — so October's split verdict is the last wholesale read the committee gets.
Earnings Today
Before the open
- PDD Holdings (PDD)
- Baidu (BIDU)
- XPeng (XPEV)
- Tyson Foods (TSN)
- Aramark (ARMK)
- KE Holdings (BEKE)
After the close
- PagSeguro Digital (PAGS)
- Aecom (ACM)
- Powell Industries (POWL)
Recent Basic Editions
Education builds conviction
Pro Degenerate — $7.99/mo, no free trial: every edition complete as it publishes, the Pro shelf with the Lens board, the Engine List dossiers and the scorecards. Ultimate Degen — $14.99/mo: everything in Pro, plus Discord — Discord is an Ultimate Degen benefit, not part of Pro.
The GEX LEVELS linked from this journal's Lens plates come from FlowState's Trade Desk — the gamma exposure levels behind the names and the index, published by FlowStateOfMind at flowstateofmind.io.
The Degenerates Journal is published for research and education purposes only — not financial advice.
In this edition
- Yesterday's Tape
- Market Movers
- While You Slept
- Pre-Market / Overnight Standout
- Futures Read
- Market Health
- Economic Calendar
- Earnings Today
- The Engine List
- Market News
- The Question into the Close
- Education builds conviction — membership