THE DEGENERATES JOURNAL
Friday, November 13 settled closes — the S&P 500 rose 2.51% on the week, from 7,376.86 at the November 6 close, after Monday's 2.35% rally, the market's best session since April
Headlines
Nvidia lost its founder on Thursday — Jensen Huang resigned effective immediately — and the shares fell 8.85% on the week to $162.85
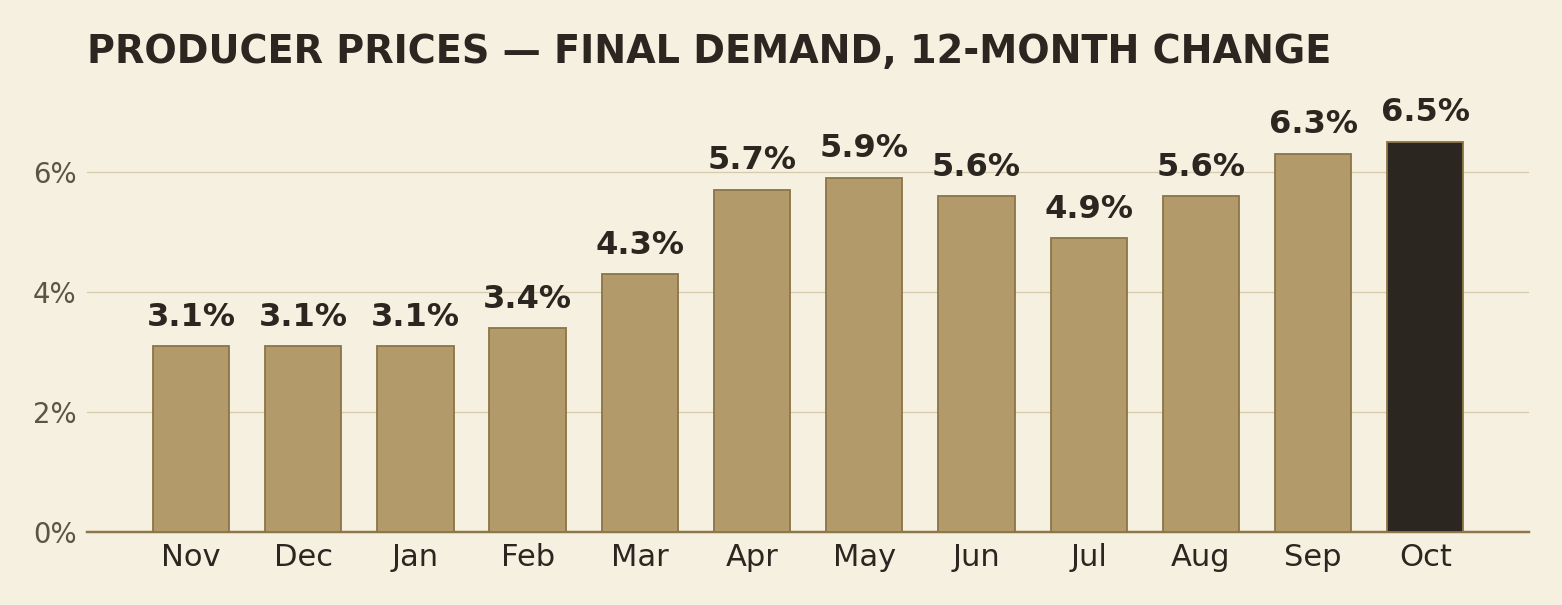
Inflation printed hot twice — consumer prices rose 0.4% in October and producer prices rose 6.5% on the year, the fastest since November 2022
The index finished higher anyway — the S&P 500 gained 2.51% on the week to 7,561.67, carried by Monday's 2.35% rally, its best day since April
May contain typos. Prices may be delayed depending on when the data was collected.
A free Sunday edition for the Degenerates Journal community.
01 · The Week in Review
The Week That Was
The week told two stories at once: a governance shock at the centre of the AI trade — the founder of its most important company gone in a morning — and an index that absorbed it, finishing the week 2.51% higher at 7,561.67.
The week in full — the rally, the two hot inflation prints and the founder story, day by day
Inflation supplied the pressure underneath. October consumer prices rose 0.4% with core up 0.3% for a third straight month, producer prices rose 6.5% on the year, and the 10-year Treasury yield climbed from 4.86% to 5.15%. A December rate hike became the priced outcome — the week's quiet verdict under the noise.
What the week left open is concentrated in one name and one meeting: Nvidia reports Tuesday after the close, the first print of the post-Huang company, and the Fed's October minutes land Wednesday, ahead of the December 8-9 meeting.
The Week at a Glance
02 · The Data
Econ Addendum
Week ending Nov 13 · Econ data for the week ending November 13, compiled Sunday, November 15.
| Release | Actual | Expected | 2-mo trend | Fundamental read |
|---|---|---|---|---|
| Consumer Prices (Oct) | +0.4% m/m | +0.3% m/m | Sep — Oct +0.4% m/m | Headline consumer prices came in a tenth hot — the print that repriced December on Tuesday morning. |
| Core Consumer Prices (Oct) | +0.3% m/m | +0.2% m/m | Aug +0.3% m/m Sep +0.3% m/m Oct +0.3% m/m | Core prices rose 0.3% for a third straight month — the persistence, not the level, is what the Fed has to answer. |
| Producer Prices (Oct) | +0.3% m/m | +0.4% m/m | Oct +0.3% m/m | Producer prices cooled against forecast in the month — Friday's one soft number — and the session went to the yield curve anyway. |
| Producer Prices, 12-month (Oct) | +6.5% y/y | — | Sep +6.3% y/y Oct +6.5% y/y | The 12-month producer rate hit 6.5%, the fastest since November 2022 — the year's pipeline pressure is still building, not fading. |
| 10-Year Treasury Yield (Fri close) | 5.15% | — | Mon 4.86% Tue 4.98% Thu 5.10% Fri 5.15% | The 10-year yield climbed every rung of the week and closed above 5% on back-to-back sessions — the week's real verdict on the inflation prints. |
03 · Market Health
Market Health — The Week
Market health as of Friday's close, November 13
| Volatility | The VIX opened the week at 25.08, fell back under 20 in Monday's 2.35% rally, and closed Friday at 19.30 — up 3.21% on the day as the week's last session rotated defensive. The fear gauge ended the week calmer than it began, and still near 20. |
| Breadth | Split by the day. Thursday's redistribution put 3 of the 6 names on the week's screen above their 50-day averages — the three reclaim names, all up more than 5% — and Friday took it back: 7 of 11 sector funds closed higher, led by consumer staples at +1.42%, while technology was the weakest fund at -2.01% and none of the six names on the week's screen finished higher. |
| Trend — the Meter | The board splits clean in two. Three names still read Strong Bullish — Apple at 98.7, Amazon at 91.87 and Microsoft at 66.97 — with Tesla Bullish at 48.3; against them, seven names read Strong Bearish, the week's defining name, Nvidia, among them at -81.7. The Degen Risk gauge closed the week at 89, Transition, up from 77 on Wednesday. |
| The record | November's graded record stands at 16 Confirmed, 12 Contradicted, 4 Unresolved across seven graded sessions. Of this week's five morning questions, only Wednesday's confirmed — the CoreWeave-led bounce more than survived its session — while Monday's, Tuesday's, Thursday's and Friday's each carried an open leg and graded Unresolved. |
04 · The Record
The Week's Record
Every morning the journal asks one question and grades it against the close. November's graded record, to date: 7 graded sessions — 16 Confirmed, 12 Contradicted, 4 Unresolved.
The record in full — every morning's question and its grade, day by day
Monday, November 9 — “Does the S&P 500 make it two gains in a row today after Thursday's rout — and hold the bounce into Tuesday's inflation print?” Unresolved: the index rose 173.08 points (+2.35%) to 7,549.94 — a second straight gain — but the hold into Tuesday's print graded as a separate, still-open leg.
Tuesday, November 10 — “Does October's inflation print at 08:30 ET let Monday's oil-led rally stand — or does a hot core reading hand the day back?” Unresolved: the print came in hot — core up 0.3% for a third straight month against +0.2% expected — and the index fell 0.38% to 7,520.93, yet kept most of Monday's gain, so the question stays open on the record.
Wednesday, November 11 — “Does the CoreWeave-led relief bounce survive a full session with no bond market to answer Tuesday's 5% yield — or was the premarket move the whole of it?” Confirmed: the index rose 1.31% to 7,619.38, the week's highest close, and CoreWeave closed up 24.71% at $60.77 — the premarket move was the start of the move, not the whole of it.
Thursday, November 12 — “Does the AI complex hold a session whose centre — Nvidia's chief executive — is reportedly on his way out, or does Wednesday's rebound unwind in full by the close?” Unresolved: neither leg completed — the index fell 0.35% to 7,592.40, Nvidia recovered from a $148.80 low to close down 4.34% at $166.19, and the flow rotated inside the complex, AMD up 5.86% and Broadcom up 5.54%.
Friday, November 13 — “Does Friday hold the redistribution — the rivals keeping Thursday's gains while Nvidia stabilises under an interim chief executive — or does producer prices at 08:30 ET hand the session back to the yield curve?” Unresolved: the redistribution failed outright — AMD fell 8.75%, Broadcom 4.76%, Arista Networks 4.52% — and the session went to the yield curve without its stated trigger, producer prices rising 0.3% against a 0.4% forecast while the 10-year yield rose to 5.15%.
05 · Look Ahead
Look Ahead
Calendar compiled Sunday, November 15 from the week's schedule of record.
| Day | Release | Time (ET) |
|---|---|---|
| Mon Nov 16 | No major releases — the week's calendar closes emptyA quiet data day — the week's first report card comes Tuesday, and until then the market trades on Friday's defensive close and the 5.15% 10-year yield. | — |
| Tue Nov 17 | Retail Sales (October) — consensus +0.2% in the monthThe week's hinge: October retail sales at 08:30, Home Depot and Walt Disney before the open, and after the close the first Nvidia print of the post-Huang company, against $108.0 billion of guided revenue. | 08:30 |
| Wed Nov 18 | Fed meeting minutes — the October 27-28 meetingThe week's Fed document: the minutes of the October 27-28 meeting, read for how close the committee sat to the December hike the market now prices. Housing starts print at 08:30; Target and TJX report before the open, and Lowe's is expected the same morning on a date the company still marks tentative. | 14:00 |
| Thu Nov 19 | Weekly Jobless ClaimsWalmart before the open is the week's consumer read at the value end; Ross Stores reports after the close, and Anthropic is expected to begin trading on the Nasdaq under the ticker ANT after a Wednesday pricing. | 08:30 |
| Fri Nov 20 | No major releases on the week's schedule of recordThe week's calendar empties out — Friday trades on the aftermath of the minutes and the second read of Tuesday's Nvidia print, with positioning into the December 8-9 meeting the only scheduled story. | — |
| Symbol | Company | Reports | Timing |
|---|---|---|---|
| HD | Home Depot | Tue Nov 17 | Before open |
| DIS | Walt Disney | Tue Nov 17 | Before open |
| NVDA | Nvidia | Tue Nov 17 | After close |
| TGT | Target | Wed Nov 18 | Before open |
| TJX | TJX Companies | Wed Nov 18 | Before open |
| LOW | Lowe's | Wed Nov 18 | Before open |
| WMT | Walmart | Thu Nov 19 | Before open |
| ROST | Ross Stores | Thu Nov 19 | After close |
06 · Standout
The Week's Standout
Nvidia (NVDA) — the week it lost its founder: down 2.01% on Friday, down 8.85% on the week
Why Nvidia stood out On Thursday morning Nvidia announced that Jensen Huang — its founder and the centre of the AI trade — had resigned effective immediately. The shares opened about 14% lower, touched $148.80, and recovered to close down 4.34% at $166.19; on Friday they fell a second day, down 2.01% to $162.85 under interim chief executive Colette Kress. The week carried the name from $178.67 at Monday's close to $162.85 — down 8.85% while the S&P 500 rose 2.51%. No other name on the week's screen carries a story, a fall and a board ranking all at once.
What the week proved The demand leg held everywhere except at the centre. CoreWeave rose 24.71% on Wednesday on its print; Cisco and Applied Materials both beat and raised after Thursday's close; the rivals took Thursday's flow — and then handed it back in full on Friday, AMD down 8.75%, Broadcom down 4.76%, Arista Networks down 4.52%. The Lens still ranks Nvidia first of sixteen at a 74.3 average — Inflection 85 and Position 96 say the business scores did not break — while the Meter reads -81.7, Strong Bearish and washed out. The week's cleanest split is that one: the business of record and the price of record pointing opposite ways into the print.
The business in plain words Nvidia designs the accelerators — the specialised chips — that the world's AI models are trained and run on. The scale, from the board's own fundamentals line: revenue of $303.0 billion over the last twelve months, up 104.0% on a year earlier, at a gross margin of 74.7%, with net cash of $36.0 billion. That is the machine the founder built; the week's question is not what it earns this quarter — guidance is $108.0 billion for Tuesday's print — but who runs it now, and whether the premium the shares carried for his hand on it survives him.
The two sides For: the board's first-ranked trio, the demand leg verified three times in a week by its own customers and rivals, and a model base value of $215.79 that sits above the close — the board's only valued name whose settled close sits below its base value, a 24.5% gap. Against: the founder is gone, a House committee wants his testimony before Thanksgiving with a December 1 closed-door interview proposed, the Meter is washed out below every average that matters, and the first print of the new regime lands in four days with the whole complex priced off it.
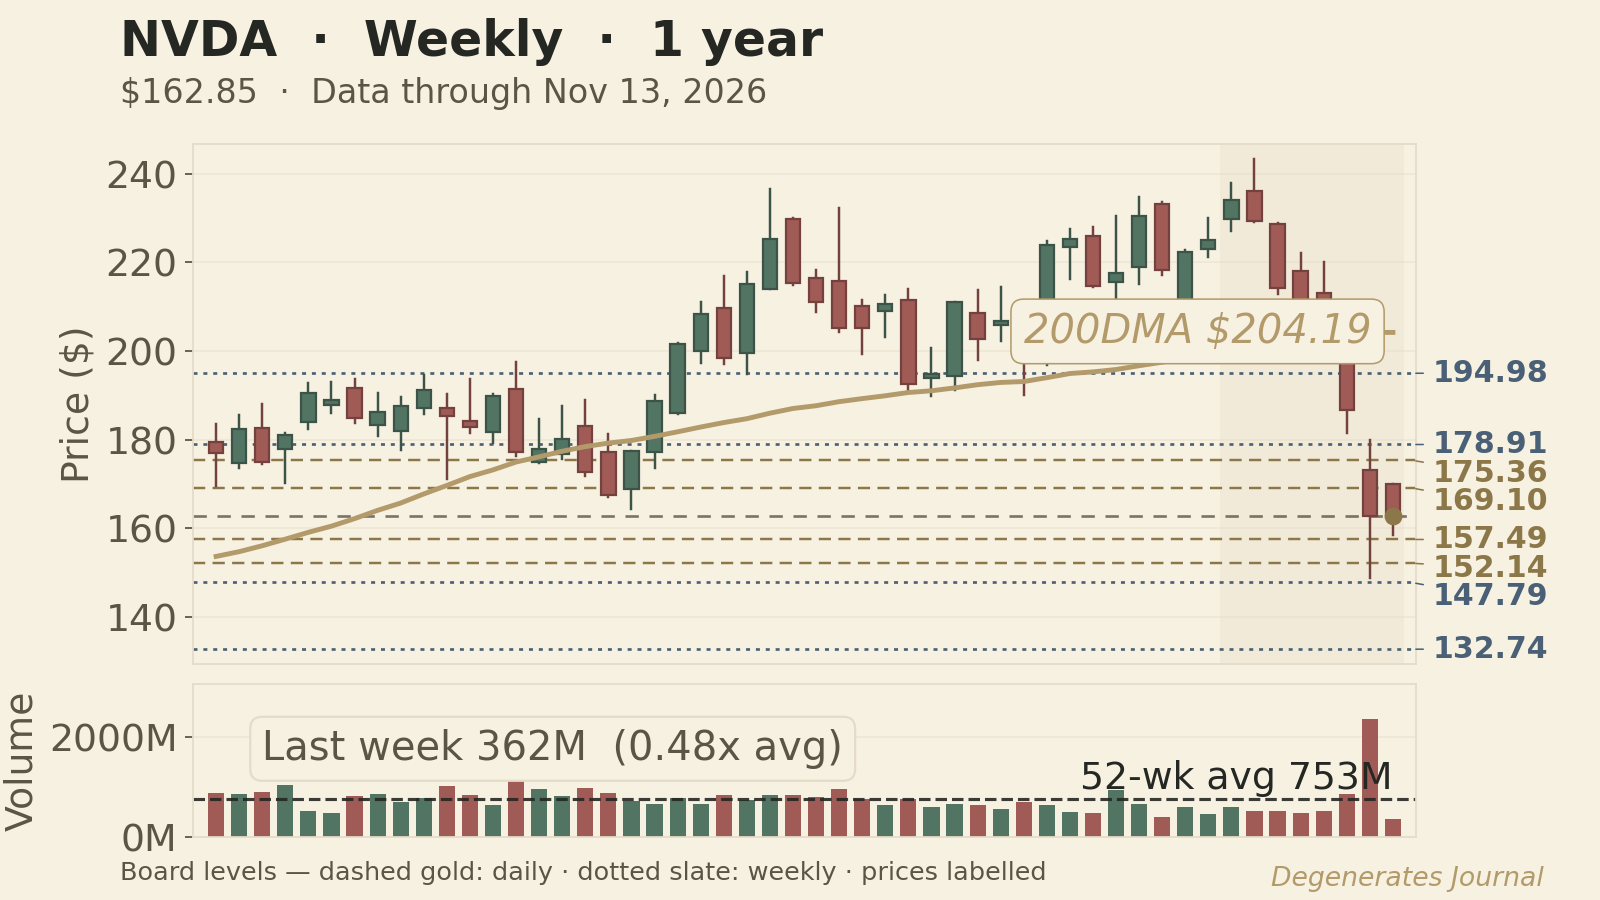
What to watch Tuesday after the close: the quarter, against $108.0 billion of guided revenue, presented by interim chief executive Colette Kress — the first public account of the post-Huang company. Into it, the levels from the board's record: weekly support at $147.79, near Thursday's $148.80 low, and weekly resistance at $178.91, above Monday's close. After the print, the governance clock runs — testimony before Thanksgiving, or the December 1 closed-door interview the committee chairs have proposed.
| The week in figures | |
|---|---|
| Friday close | $162.85 |
| Friday's session | -2.01% — a second straight lower close under the interim chief executive |
| The week | -8.85% — from $178.67 at Monday's close, against an index up 2.51% |
| The board | First of 16 — a 74.3 trio average on the settled board of record |
| The print ahead | Earnings Tuesday, November 17 after the close — guided revenue $108.0 billion |
Degen Lens
DEGEN METER — Score -81.7 of ±100 · Strong Bearish
Below its 200-day average · Stretch flag Washed out
Daily bars through the Fri Nov 13, 2026 close.
Scores out of 100, from the Lens board of record (settled Friday, November 13, engine 0.3): Swing 42, Inflection 85, Position 96 — a trio average of 74.3, first on the board. The LEAPS options module scores 96 on the Dec 17, 2027 contract struck at $165, 399 days to expiry. The chart and the Meter run through Friday's close.
Valuation:
07 · At Home
What It Means at Home
Prices at the store. Consumer prices rose 0.4% in October, and the core measure — without food and fuel — rose 0.3% for a third straight month. Both came in a tenth hotter than forecast, which is why the week's talk kept returning to interest rates.
The rest of the week at home — work, prices, borrowing and the week that was, in full
The rate behind a mortgage. The 10-year Treasury yield — the rate home loans follow — climbed from 4.86% on Monday to 5.15% on Friday, closing above 5% two days running. Traders now treat a December rate hike as the likely outcome, and a hike is what keeps borrowing dear.
Money in the market. The stock market rose 2.51% on the week to 7,561.67, even after Friday's 0.40% fall. Monday did the work: a 2.35% rise, the market's best day since April.
Nerves. The market's fear gauge began the week at 25.08 and closed it at 19.30 — calmer, but not settled. Investors ended the week watchful, not relaxed.
The boss who left. Nvidia — the company at the centre of the AI boom — lost its founder on Thursday, when Jensen Huang resigned effective immediately. The shares fell 8.85% on the week. The company reports its earnings on Tuesday, and what it says will reach every retirement account that owns an index fund.
Going deeper: the Degen Take, Under the Microscope, and The constructive and cautious cases are in the Pro Sunday edition — the full week, analyzed. $7.99/month.
The weekday journal returns Monday at 05:00 ET — futures and the tape, fresh every morning.
New to these terms? Learn the market, plain English.
08 · Degen Lens
Degen Lens Ranking
The week's names scored three ways — Swing, Inflection, and Position — in the Degen Lens Ranking. A score, not a call. The scores live in PRO — $7.99/month, cancel anytime.
Swing reads the week's trend, Inflection the turn in the outlook, and Position where a name sits against its own range — each scored on settled closes, so the board describes the week that was. A snapshot, not a forecast.
09 · The Journal Pages
Recent Basic Editions
Every Basic edition is free to read — Sunday's is the page you are on
Advertisement
Education builds conviction
Everything the Journal makes — the free editions, the Pro shelf, the podcast, and the company we keep — gathered on one page.
The Pro Shelf · calculateddegens.com
Where Pro lives: the Pro shelf. The Pro shelf is the members' shelf on calculateddegens.com — the home of Pro Degenerate at $7.99 a month. One shelf, four parts:
Membership — the two tiers, explained
- The full Pro editions — every weekday morning and the Sunday Pro edition
- A full page for every name: charts, levels and the complete read
- Fundy's Pick with the full valuation case
- Degen Lens scores and the LEAPS options module
- Delivered on the Pro shelf — latest edition, the board, the library, scorecards
- Everything in PRO DEGENERATE
- The Discord community — Discord is an Ultimate Degen benefit, not part of Pro
- Every edition, complete, as it publishes
Advertisement
The GEX LEVELS linked from this journal's Lens plates come from FlowState's Trade Desk — the gamma exposure levels behind the names and the index, published by FlowStateOfMind at flowstateofmind.io.
The Podcast
The Degenerates Journal podcast — the Journal in audio: the editions and the deep dives, on Spotify.
The Free Journal
The weekday Basic edition is free, every morning at 05:00 ET — and the Sunday Basic is free every week. No membership needed.
In this edition
- Headlines
- The Week That Was
- Econ Addendum
- Market Health — The Week
- The Week's Record
- Look Ahead
- The Week's Standout
- What It Means at Home
- Degen Lens Ranking
- Education builds conviction — membership