Home / Research / Company deep dive
Company deep dive · The financing is the story
Broadcom × Anthropic: the loop
Broadcom's growth engine and its largest credit exposure are now the same company. Anthropic is Broadcom's anchor chip customer — and also its tenant, its potential borrower, its guaranteed counterparty, and, at next week's IPO, its investment. Seller, lessor, guarantor, lender, shareholder: five hats, one counterparty.
Position disclosure — November 11, 2026: this piece covers Broadcom ($AVGO), which sits in the desk's current position book (NVDA · SNDK · MU · QCOM · AVGO · TSLA · SPCX) — the book prints in the open in the current editions of The Degenerates Journal.
Fact checked — every figure verified against Anthropic's S-1/A (November 10, 2026) and Broadcom's Form 10-Q and 8-K filings · November 11, 2026.
Section 01The verdict
The conclusion: Broadcom's growth engine and its largest credit exposure are now the same company. Anthropic is Broadcom's anchor chip customer — and also its tenant, its potential borrower, its guaranteed counterparty, and, at next week's IPO, its investment. The filings (Anthropic's S-1/A of Nov 10, Broadcom's 10-Q and 8-Ks) show a loop in which Broadcom sells the racks, guarantees the loans that buy them, may lend Anthropic the money to pay the rent on them, and buys a billion dollars of the renter's stock. None of this makes the growth fake — Anthropic can fund the next year three times over — but it means an $AVGO holder no longer owns a chip story with a financing footnote. The financing is the story, and at ~$345 the share price already pays for the version where it all works. Here's why:
Section 02The loop, in plain words
- Google co-designs the TPUs with Broadcom (agreement through 2031). Anthropic has committed at least $121.3B to Google Cloud running through 2033.
- Banks and Blackstone lend a financing vehicle $63B (first lien: BofA, Citi, Morgan Stanley; second lien: Blackstone). The vehicle buys Broadcom racks with the borrowed money.
- Anthropic leases the racks for five years: about $161.2B of rent, non-cancelable except on default. The 2026 lease alone carries $125.2B of rent.
- Broadcom guarantees the lenders' downside: backstops with stated maximums of about $29B (June tranche) and about $43B (the October vehicle) — roughly $72B of contingent cover.
- Broadcom may also lend Anthropic up to $42B in notes — which S-1 reporting describes as financing the quarterly rent itself, at 9% interest added to the debt, rising to 13% if revenue conditions are missed. None had been issued as of Aug 2.
- Broadcom is buying about $1.0B of Anthropic stock in the IPO private placement (13.5M shares at $74).
Seller, lessor, guarantor, lender, shareholder: five hats, one counterparty.
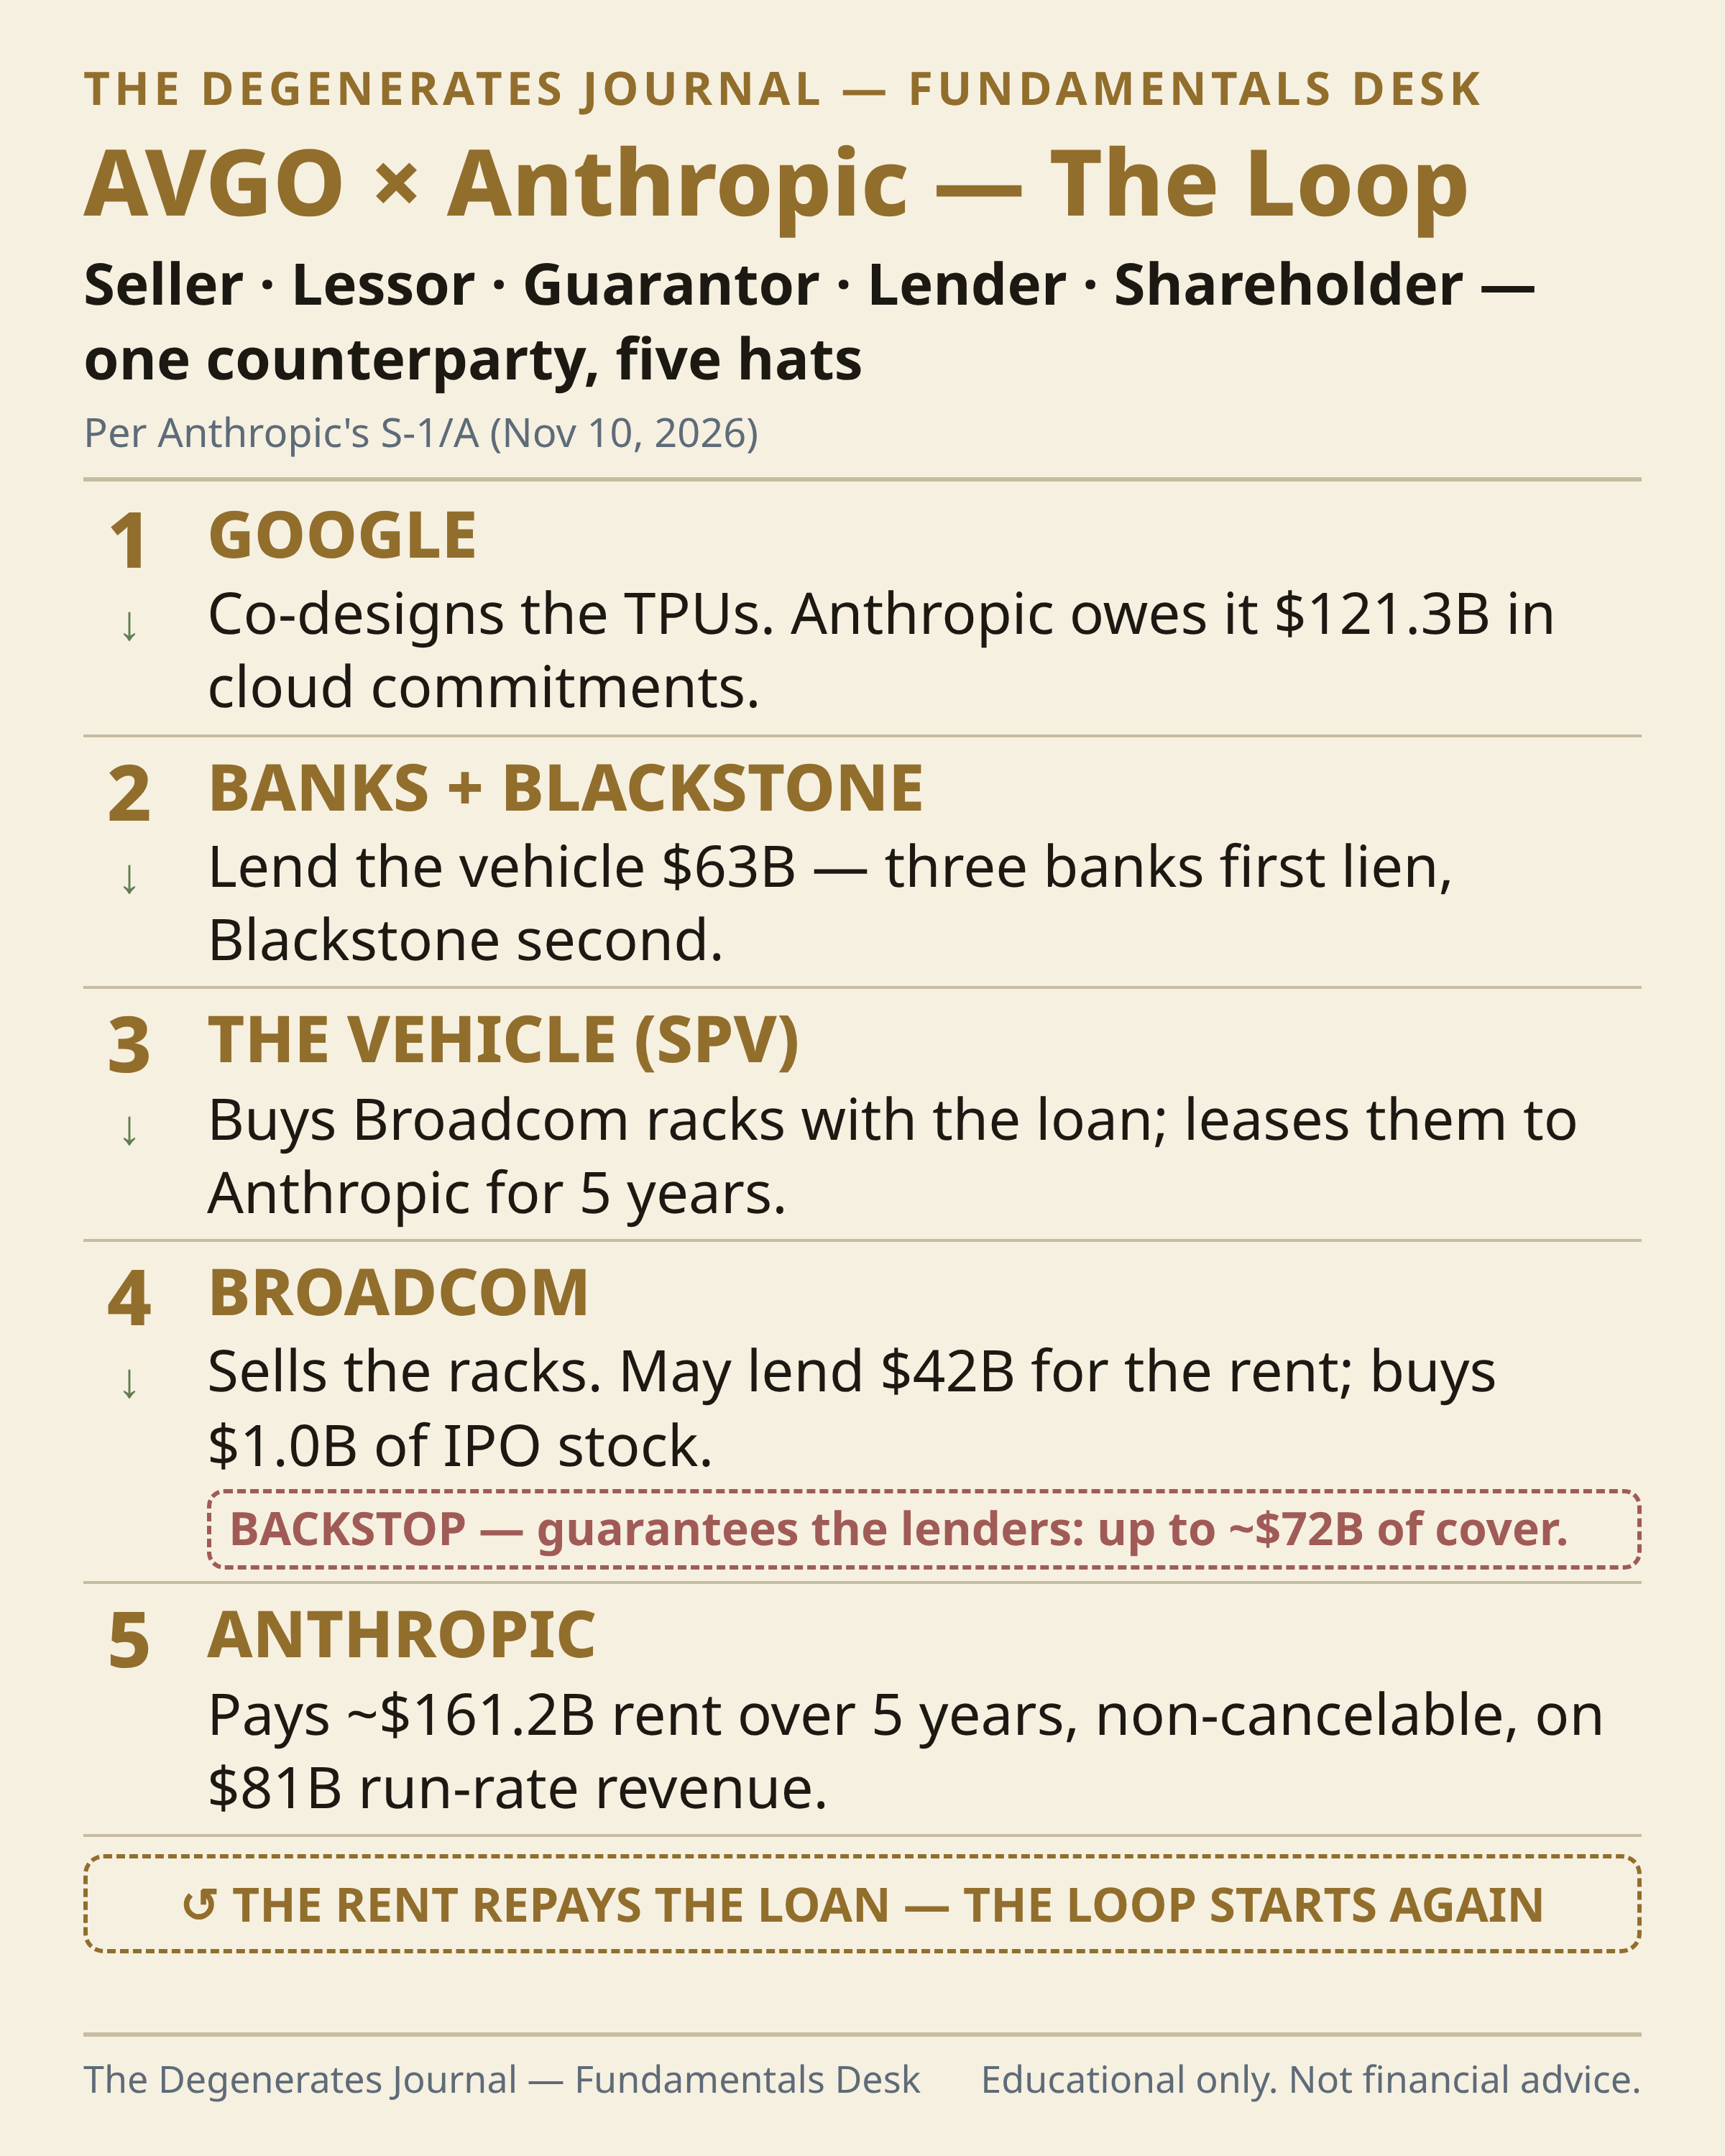
The money in a circle: the vehicle borrows $63B to buy Broadcom racks, Anthropic's rent repays the loan, and Broadcom stands behind the lenders for up to about $72B of cover. Source: Anthropic S-1/A, November 10, 2026.
Section 03Can Anthropic pay?
- Run-rate revenue: $81B at Oct 31, up $10B in a month; revenue for the first nine months of 2026 was $33.2B
- Cash and short-term investments: $131.9B, plus a $14.8B undrawn facility, plus about $84.6B of net IPO and placement proceeds at $74 — roughly $216B of liquidity before burn
- Against that: $900.9B of total commitments, with $70.7B due in the next 12 months — 87% of the run-rate
- Broadcom's rent alone runs about $32.2B a year, 40% of the run-rate; compute and infrastructure already consumed 58% of revenue in Q3
- The caution inside the growth: quarter-on-quarter revenue growth slowed from 144% to 47%
- Coverage of the next 12 months: about 3.1×. The next year is funded. Paying through 2030, where $451.6B of the commitments sit, depends on growth not stalling
Section 04What the price already assumes
- $AVGO: $345.47 pre-market today (closed $331.98 Monday); forward P/E about 17.9
- A reverse DCF on filed inputs (trailing FCF $39.4B, net debt $35.4B) needs roughly 30% annual FCF growth for five years to justify the price — approximately what delivering the FY27 AI guide (~$115B) and FY28 (~$230B) produces, followed by about 2% growth after. Delivery is the priced-in case; slippage is not priced at all
- Management's own guide discounts the headline gigawatts: 30 GW at Broadcom's $20–30B per GW is $600–900B of content, but FY27 + FY28 AI guidance totals $345B — the guide assumes only about 11.5–17 GW reaches revenue in the window, because land, power and shells bind
- The margin tell: non-GAAP gross margin is guided down to about 73% for Q4 (from 75.0% in Q3) as rack and system sales mix in pass-through memory. The growth is real, and it is lower-margin than the chip growth it replaces
Section 05Who carries the risk (the order losses run)
- Anthropic's shareholders first — Google, Amazon, Nvidia, Microsoft, AMD, Micron, TSMC, and Broadcom itself through the $26B placement
- The racks' resale value — the vehicle can resell them or sell them back at set prices in some cases
- Broadcom's backstop — any shortfall between rack proceeds and 72.5% (October vehicle) or 85% (June tranche) of the outstanding lease
- Second-lien money (Blackstone) beyond Broadcom's cover
- Separately, Google ($121.3B), Amazon ($110B) and Microsoft ($44.9B) hold non-cancelable commitments from Anthropic and are creditors in their own right
The single variable that decides whether the backstop stays theoretical: what a used TPU rack is worth when the next generation lands. No filing discloses a residual-value curve.
Section 06The window (next 30 days)
- Nov 17: $NVDA reports
- Nov 18: Anthropic's IPO is reported to price ($70–$78 range; trading Nov 19) — the loop gets a public price
- Dec 8–9: FOMC; Dec 9 after the close: Broadcom's Q4 (AI revenue guide $21.7B; the ~73% gross-margin guide is the tell)
- Dec 10: November CPI
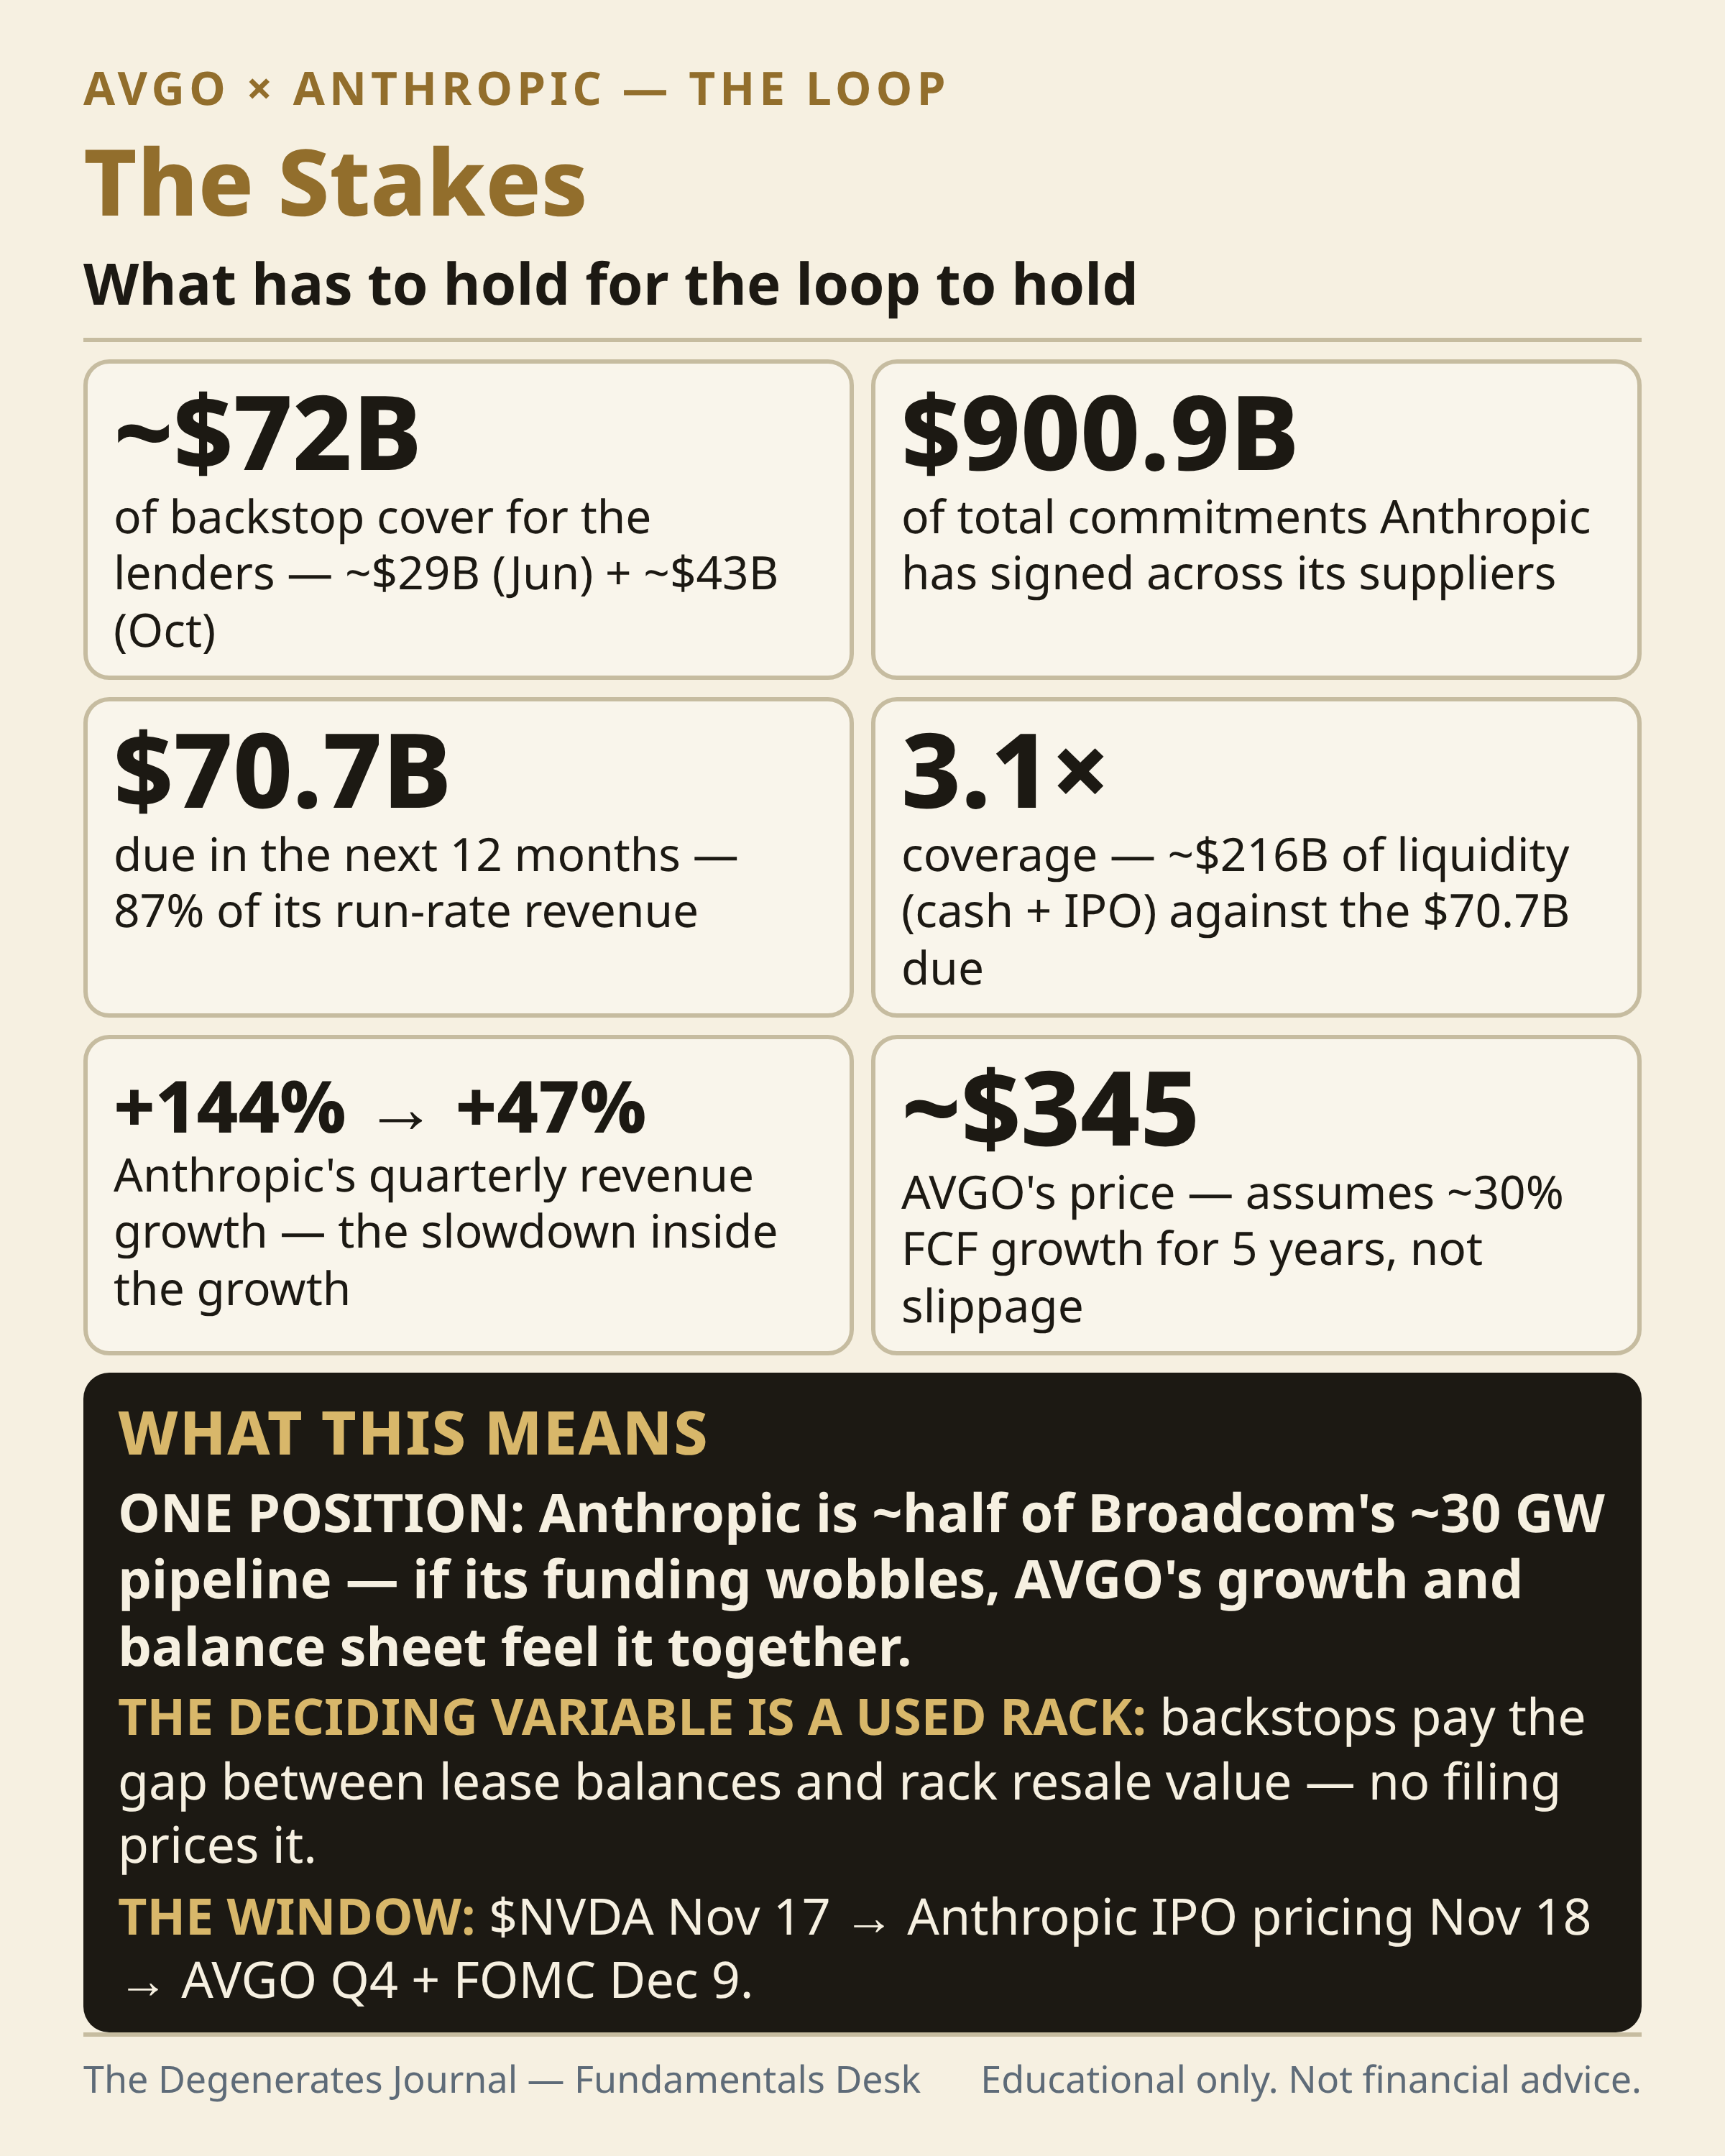
The numbers that decide it: $900.9B of commitments against about $216B of liquidity, one position linking Broadcom's growth to Anthropic's funding — and a share price that already assumes delivery. Source: Anthropic S-1/A, November 10, 2026; Broadcom filings.
Section 07The conservative take
This is vendor financing with better paperwork. In 2000, Lucent and Nortel lent billions to carriers whose purchases were the vendors' revenue; when the carriers failed, a third to four-fifths of some loan books vanished, because the collateral — telecom gear — lost value with every new generation. The differences here are real: Anthropic earns a 12% adjusted operating margin, holds $131.9B of cash and is raising $84.6B more, where the 2000 borrowers were pre-revenue. But the dependence has the same shape: the vendor's growth now requires one customer's continued access to capital, the collateral depreciates by generation, and Broadcom's own maximum cover is about $72B against its customer's $900.9B of promises. Broadcom calls the backstops low-probability and not material at fair value. Maximums are not probabilities — and Dec 9 is when the market next gets to ask.
Section 08The cyclical take
Or this is simply what winning the post-GPU buildout costs. Anthropic's commitments are the strongest demand evidence in the AI trade — $900.9B of signed obligations, 87% of next year's already covered more than three times by liquidity. Broadcom's exposure is contingent, sits behind the racks' resale value, and shrinks as the leases amortize; its AI revenue grew 221% last quarter to $16.7B, its networking attaches to nearly every rack whoever designs the chip, and at about 18 times forward earnings it is the cheapest large-cap way to own the custom-silicon shift. If Anthropic's growth holds two more years, the loop reads in hindsight not as circular financing but as a supplier financing its own category's creation — the way infrastructure has always been built when the customer outgrows the vendor's balance sheet.
Section 09What would change this read
- The IPO prices below $70 or is pulled: the funding leg wobbles. At or above the range with the placement filled, the loop is financed for now
- Any payment under a backstop, or a new backstop filing: contingent becomes real, and the read flips
- Dec 9: Q4 AI revenue against the $21.7B guide; the FY27 guide held at ~$115B; a Q1 gross-margin guide below 73% confirms the margin path
- Anthropic's first public report: run-rate still climbing against the $70.7B due in 12 months, and compute's share of revenue versus Q3's 58%
- The 2027 gigawatt gap resolved: the April 8-K says ~3.5 GW through Broadcom; the calls say 5 GW — a $30–45B difference in content, still unexplained
Educational only. Not financial advice.
$AVGO $GOOGL $SPY $QQQ
Sources — Anthropic S-1/A (November 10, 2026): the commitments, the leases, the notes facility and the IPO placement figures. Broadcom Form 10-Q and 8-K filings, including the April 8-K: the rack agreements, the backstops, the gigawatt figures and guidance. First published by the Fundamentals Desk of The Degenerates Journal, November 11, 2026. The reverse DCF is the author's analysis on filed inputs, not a forecast. No price target is offered.