Pages
In this edition
- The week line and Friday's tape
- The week's news, with our read
- Market health and breadth
- Scoring the week
- Next week's calendar and earnings
- Engine List and the names we watch
- Education desk
- Question for the Week
Download this edition as a PDF
THE CLOSE · Saturday edition
· Basic edition
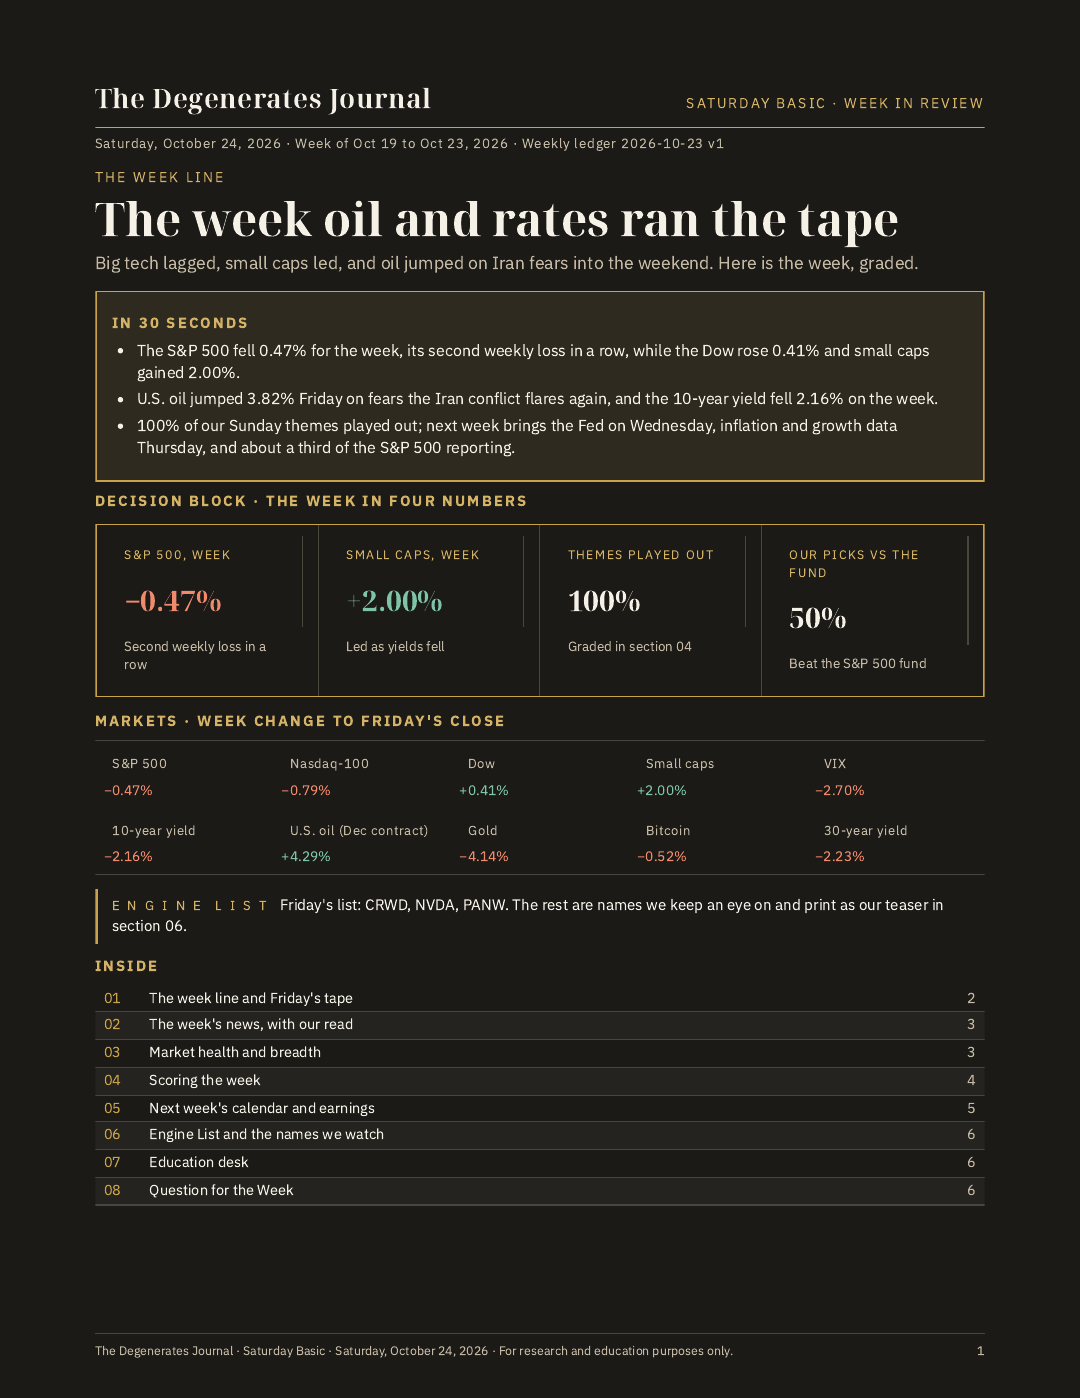
THE CLOSE — the week of October 19–23, graded: the S&P 500 fell 0.47% for the week, its second weekly loss in a row, while small caps gained 2.00% and U.S. oil jumped 3.82% Friday on Iran fears. 100% of our Sunday themes played out; 50% of our picks beat the S&P 500 fund. Every receipt is graded inside.
The full text of this Basic edition, for readers and search engines — the paged edition above stays the canonical visual.
01
The week line and Friday's tape
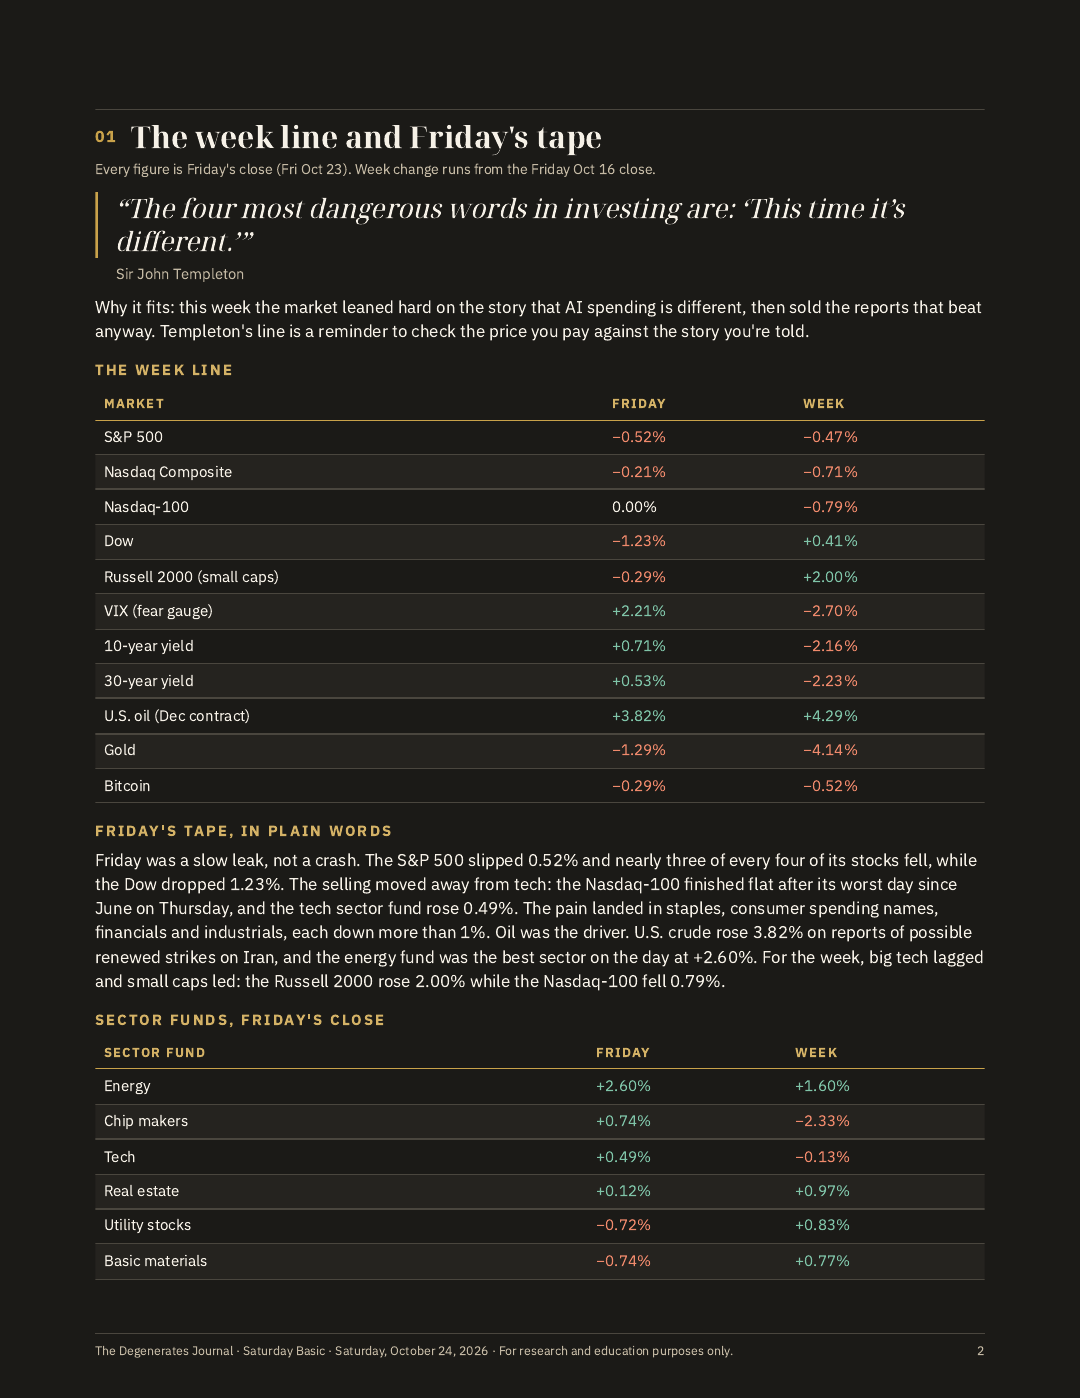
Every figure is Friday's close (Fri Oct 23). Week change runs from the Friday Oct 16 close.
“The four most dangerous words in investing are: ‘This time it’s different.’” Sir John Templeton
Why it fits: this week the market leaned hard on the story that AI spending is different, then sold the reports that beat anyway. Templeton's line is a reminder to check the price you pay against the story you're told.
S&P 500
−0.52%
−0.47%
Nasdaq Composite
−0.21%
−0.71%
Nasdaq-100
0.00%
−0.79%
Dow
−1.23%
+0.41%
Russell 2000 (small caps)
−0.29%
+2.00%
VIX (fear gauge)
+2.21%
−2.70%
10-year yield
+0.71%
−2.16%
30-year yield
+0.53%
−2.23%
U.S. oil (Dec contract)
+3.82%
+4.29%
Gold
−1.29%
−4.14%
Bitcoin
−0.29%
−0.52%
Friday was a slow leak, not a crash. The S&P 500 slipped 0.52% and nearly three of every four of its stocks fell, while the Dow dropped 1.23%. The selling moved away from tech: the Nasdaq-100 finished flat after its worst day since June on Thursday, and the tech sector fund rose 0.49%. The pain landed in staples, consumer spending names, financials and industrials, each down more than 1%. Oil was the driver. U.S. crude rose 3.82% on reports of possible renewed strikes on Iran, and the energy fund was the best sector on the day at +2.60%. For the week, big tech lagged and small caps led: the Russell 2000 rose 2.00% while the Nasdaq-100 fell 0.79%.
Energy
+2.60%
+1.60%
Chip makers
+0.74%
−2.33%
Tech
+0.49%
−0.13%
Real estate
+0.12%
+0.97%
Utility stocks
−0.72%
+0.83%
Basic materials
−0.74%
+0.77%
The Degenerates Journal · Saturday Basic · Saturday, October 24, 2026 · For research and education purposes only.
Health care
−1.11%
+1.45%
Industrial stocks
−1.27%
−1.87%
Banks and finance
−1.32%
+0.68%
Consumer discretionary
−1.66%
+0.57%
Media and telecom
−1.78%
−4.36%
Consumer staples
−1.92%
+0.73%
02
The week's news, with our read
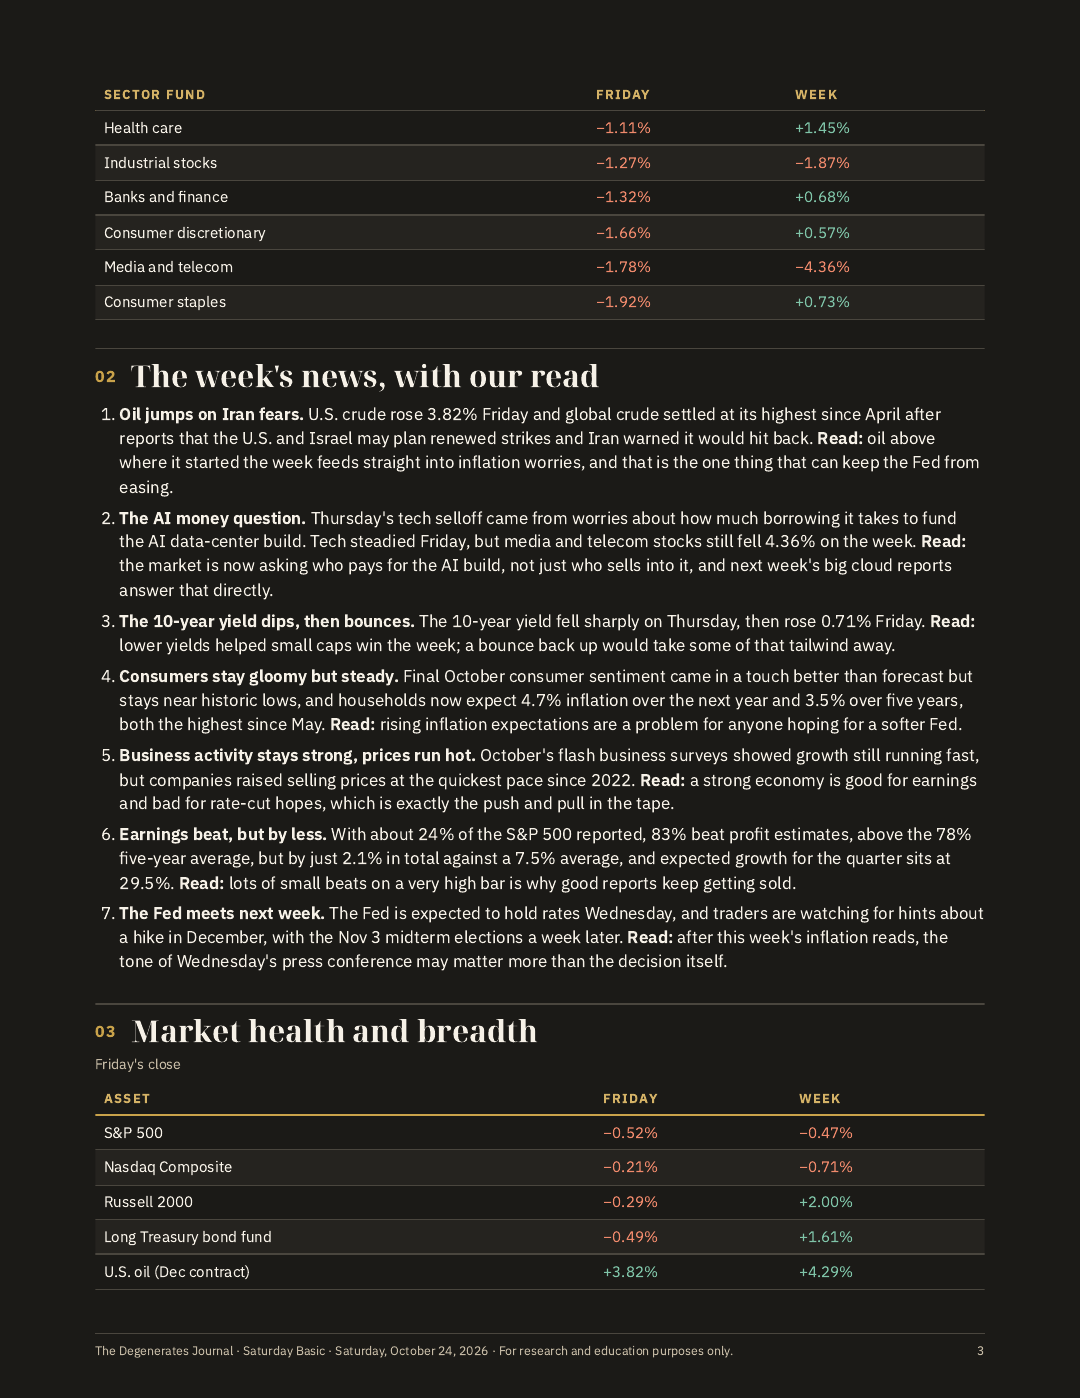
1. Oil jumps on Iran fears. U.S. crude rose 3.82% Friday and global crude settled at its highest since April after reports that the U.S. and Israel may plan renewed strikes and Iran warned it would hit back. Read: oil above where it started the week feeds straight into inflation worries, and that is the one thing that can keep the Fed from easing. 2. The AI money question. Thursday's tech selloff came from worries about how much borrowing it takes to fund the AI data-center build. Tech steadied Friday, but media and telecom stocks still fell 4.36% on the week. Read: the market is now asking who pays for the AI build, not just who sells into it, and next week's big cloud reports answer that directly. 3. The 10-year yield dips, then bounces. The 10-year yield fell sharply on Thursday, then rose 0.71% Friday. Read: lower yields helped small caps win the week; a bounce back up would take some of that tailwind away. 4. Consumers stay gloomy but steady. Final October consumer sentiment came in a touch better than forecast but stays near historic lows, and households now expect 4.7% inflation over the next year and 3.5% over five years, both the highest since May. Read: rising inflation expectations are a problem for anyone hoping for a softer Fed. 5. Business activity stays strong, prices run hot. October's flash business surveys showed growth still running fast, but companies raised selling prices at the quickest pace since 2022. Read: a strong economy is good for earnings and bad for rate-cut hopes, which is exactly the push and pull in the tape. 6. Earnings beat, but by less. With about 24% of the S&P 500 reported, 83% beat profit estimates, above the 78% five-year average, but by just 2.1% in total against a 7.5% average, and expected growth for the quarter sits at 29.5%. Read: lots of small beats on a very high bar is why good reports keep getting sold. 7. The Fed meets next week. The Fed is expected to hold rates Wednesday, and traders are watching for hints about a hike in December, with the Nov 3 midterm elections a week later. Read: after this week's inflation reads, the tone of Wednesday's press conference may matter more than the decision itself.
03
Market health and breadth
Friday's close
S&P 500
−0.52%
−0.47%
Nasdaq Composite
−0.21%
−0.71%
Russell 2000
−0.29%
+2.00%
Long Treasury bond fund
−0.49%
+1.61%
U.S. oil (Dec contract)
+3.82%
+4.29%
The Degenerates Journal · Saturday Basic · Saturday, October 24, 2026 · For research and education purposes only.
Gold
−1.29%
−4.14%
Bitcoin
−0.29%
−0.52%
S&P 500, week
−0.47%
Nasdaq-100, week
−0.79%
Russell 2000, week
+2.00%
S&P 500 stocks that fell Friday
nearly 3 in 4
Our universe above the 50-day average
46% at Friday's close, up from 42% Monday morning
Our universe up for the week
44% up, 56% down
VIX for the week
−2.70%
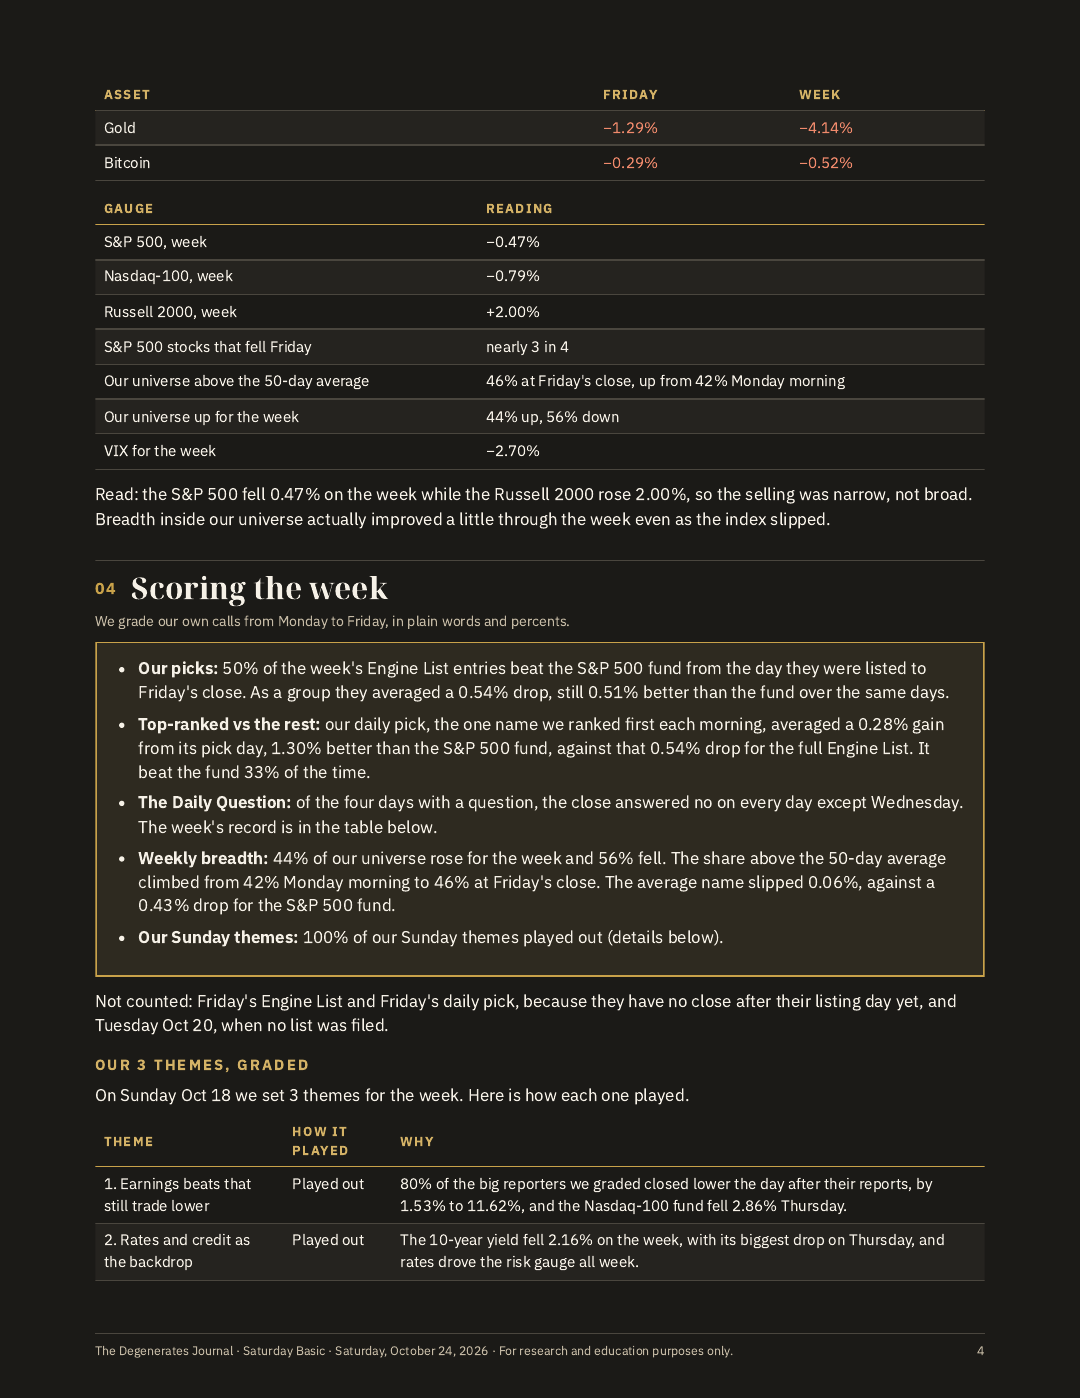
Read: the S&P 500 fell 0.47% on the week while the Russell 2000 rose 2.00%, so the selling was narrow, not broad. Breadth inside our universe actually improved a little through the week even as the index slipped.
04
Scoring the week
We grade our own calls from Monday to Friday, in plain words and percents.
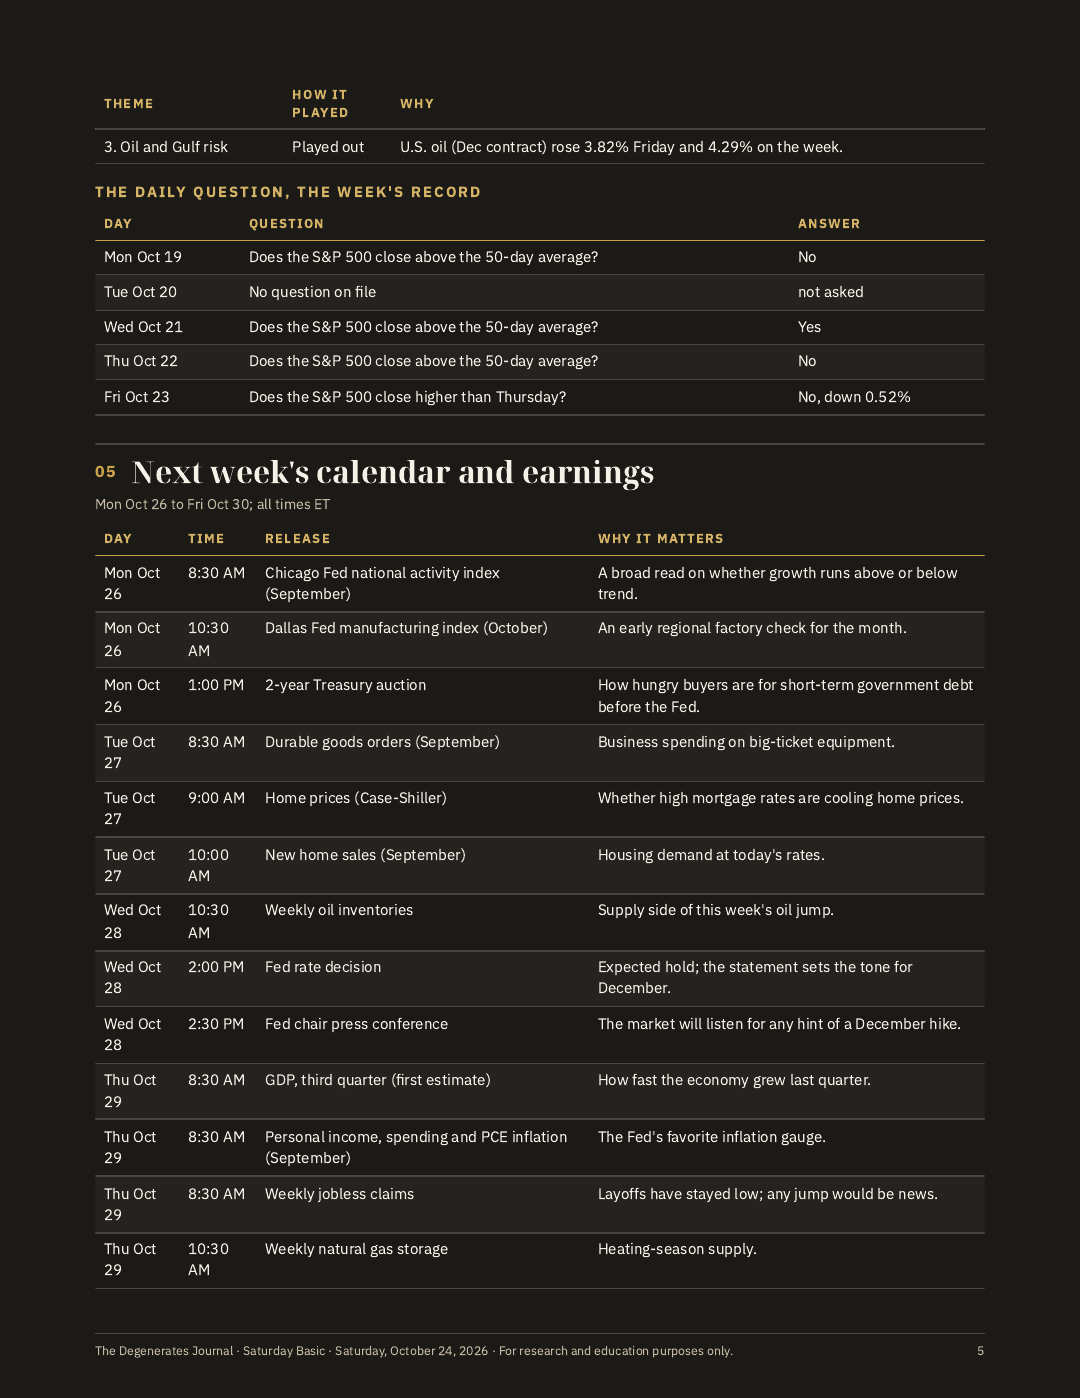
Our picks: 50% of the week's Engine List entries beat the S&P 500 fund from the day they were listed to Friday's close. As a group they averaged a 0.54% drop, still 0.51% better than the fund over the same days. Top-ranked vs the rest: our daily pick, the one name we ranked first each morning, averaged a 0.28% gain from its pick day, 1.30% better than the S&P 500 fund, against that 0.54% drop for the full Engine List. It beat the fund 33% of the time. The Daily Question: of the four days with a question, the close answered no on every day except Wednesday. The week's record is in the table below. Weekly breadth: 44% of our universe rose for the week and 56% fell. The share above the 50-day average climbed from 42% Monday morning to 46% at Friday's close. The average name slipped 0.06%, against a 0.43% drop for the S&P 500 fund. Our Sunday themes: 100% of our Sunday themes played out (details below).
Not counted: Friday's Engine List and Friday's daily pick, because they have no close after their listing day yet, and Tuesday Oct 20, when no list was filed.
On Sunday Oct 18 we set 3 themes for the week. Here is how each one played.
WHY
1. Earnings beats that still trade lower
Played out
80% of the big reporters we graded closed lower the day after their reports, by 1.53% to 11.62%, and the Nasdaq-100 fund fell 2.86% Thursday.
2. Rates and credit as
Played out
The 10-year yield fell 2.16% on the week, with its biggest drop on Thursday, and
the backdrop
rates drove the risk gauge all week.
The Degenerates Journal · Saturday Basic · Saturday, October 24, 2026 · For research and education purposes only.
3. Oil and Gulf risk
Played out
WHY
U.S. oil (Dec contract) rose 3.82% Friday and 4.29% on the week.
DAY
Mon Oct 19
Does the S&P 500 close above the 50-day average?
No
Tue Oct 20
No question on file
not asked
Wed Oct 21
Does the S&P 500 close above the 50-day average?
Yes
Thu Oct 22
Does the S&P 500 close above the 50-day average?
No
Fri Oct 23
Does the S&P 500 close higher than Thursday?
No, down 0.52%
05
Next week's calendar and earnings
Mon Oct 26 to Fri Oct 30; all times ET DAY
Mon Oct 26
8:30 AM
Chicago Fed national activity index (September)
A broad read on whether growth runs above or below trend.
Mon Oct
10:30
Dallas Fed manufacturing index (October)
An early regional factory check for the month.
26
AM
Mon Oct 26
1:00 PM
2-year Treasury auction
How hungry buyers are for short-term government debt before the Fed.
Tue Oct 27
8:30 AM
Durable goods orders (September)
Business spending on big-ticket equipment.
Tue Oct 27
9:00 AM
Home prices (Case-Shiller)
Whether high mortgage rates are cooling home prices.
Tue Oct 27
10:00 AM
New home sales (September)
Housing demand at today's rates.
Wed Oct
10:30
Weekly oil inventories
Supply side of this week's oil jump.
28
AM
Wed Oct 28
2:00 PM
Fed rate decision
Expected hold; the statement sets the tone for December.
Wed Oct 28
2:30 PM
Fed chair press conference
The market will listen for any hint of a December hike.
Thu Oct
8:30 AM
GDP, third quarter (first estimate)
How fast the economy grew last quarter.
Thu Oct 29
8:30 AM
Personal income, spending and PCE inflation (September)
The Fed's favorite inflation gauge.
Thu Oct 29
8:30 AM
Weekly jobless claims
Layoffs have stayed low; any jump would be news.
Thu Oct 29
10:30 AM
Weekly natural gas storage
Heating-season supply.
29
The Degenerates Journal · Saturday Basic · Saturday, October 24, 2026 · For research and education purposes only.
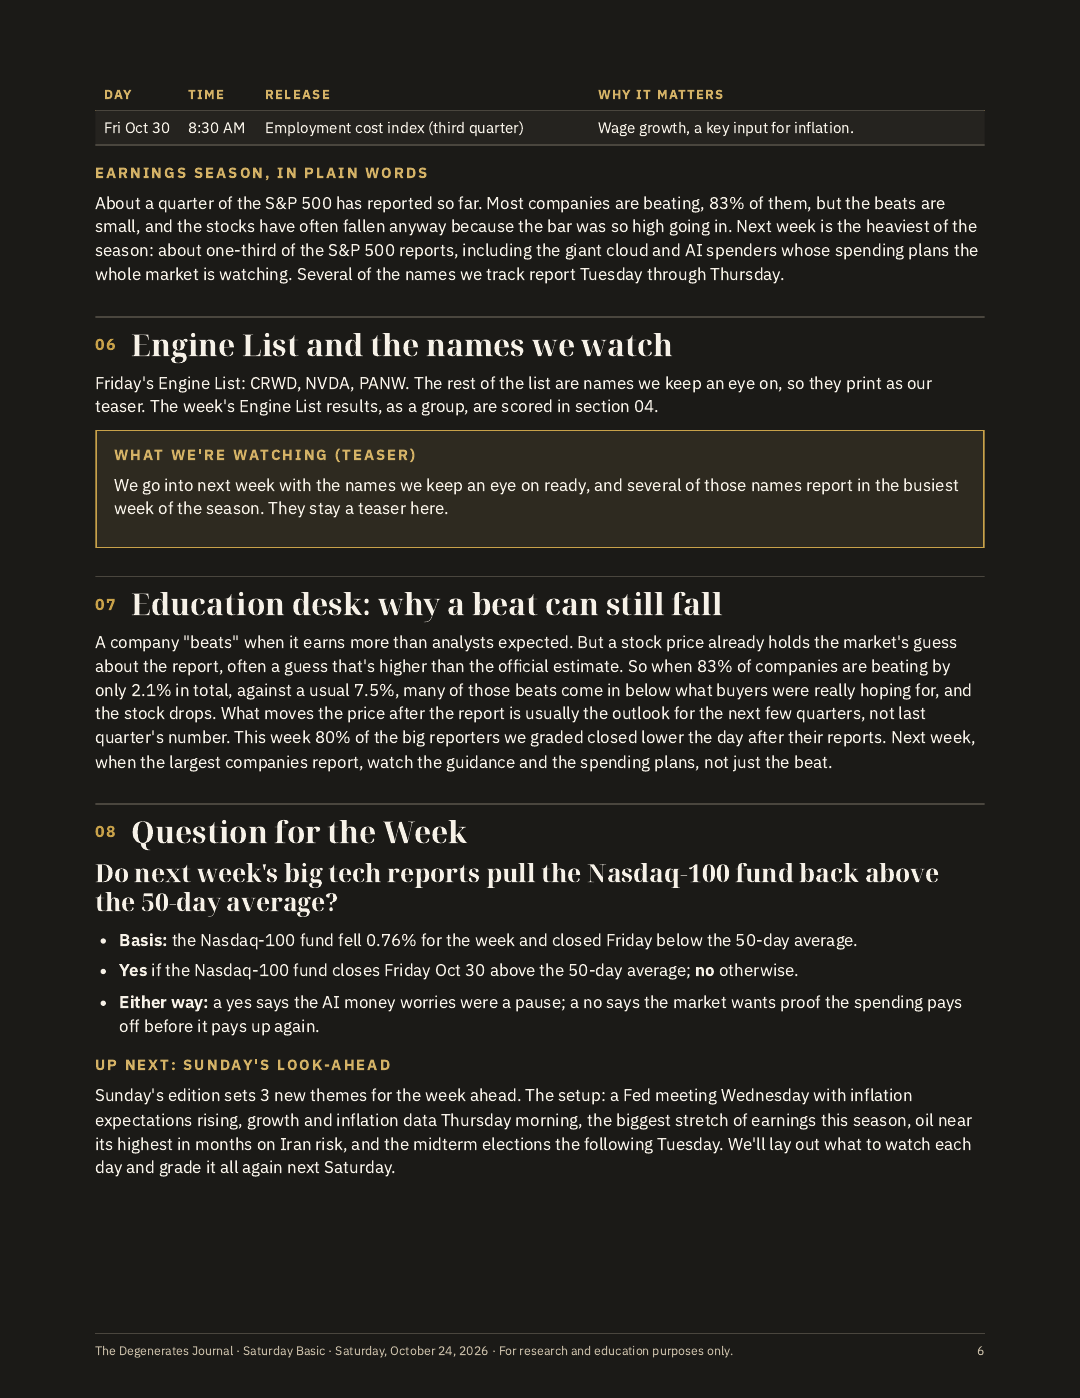
DAY
Fri Oct 30
8:30 AM
Employment cost index (third quarter)
Wage growth, a key input for inflation.
About a quarter of the S&P 500 has reported so far. Most companies are beating, 83% of them, but the beats are small, and the stocks have often fallen anyway because the bar was so high going in. Next week is the heaviest of the season: about one-third of the S&P 500 reports, including the giant cloud and AI spenders whose spending plans the whole market is watching. Several of the names we track report Tuesday through Thursday.
06
Engine List and the names we watch
Friday's Engine List: CRWD, NVDA, PANW. The rest of the list are names we keep an eye on, so they print as our teaser. The week's Engine List results, as a group, are scored in section 04.
We go into next week with the names we keep an eye on ready, and several of those names report in the busiest week of the season. They stay a teaser here.
07
Education desk: why a beat can still fall
A company "beats" when it earns more than analysts expected. But a stock price already holds the market's guess about the report, often a guess that's higher than the official estimate. So when 83% of companies are beating by only 2.1% in total, against a usual 7.5%, many of those beats come in below what buyers were really hoping for, and the stock drops. What moves the price after the report is usually the outlook for the next few quarters, not last quarter's number. This week 80% of the big reporters we graded closed lower the day after their reports. Next week, when the largest companies report, watch the guidance and the spending plans, not just the beat.
08
Question for the Week
Do next week's big tech reports pull the Nasdaq-100 fund back above the 50-day average? Basis: the Nasdaq-100 fund fell 0.76% for the week and closed Friday below the 50-day average. Yes if the Nasdaq-100 fund closes Friday Oct 30 above the 50-day average; no otherwise. Either way: a yes says the AI money worries were a pause; a no says the market wants proof the spending pays off before it pays up again.
Sunday's edition sets 3 new themes for the week ahead. The setup: a Fed meeting Wednesday with inflation expectations rising, growth and inflation data Thursday morning, the biggest stretch of earnings this season, oil near its highest in months on Iran risk, and the midterm elections the following Tuesday. We'll lay out what to watch each day and grade it all again next Saturday.
The Degenerates Journal · Saturday Basic · Saturday, October 24, 2026 · For research and education purposes only.
Want the full playbook before the bell? PRO DEGENERATE: $7.99/month. The Pro edition of the Degenerates Journal every weekday morning and Sunday night, with the full per-name research behind the names in this edition. Ultimate Degen: $14.99/month. Everything in PRO DEGENERATE, plus the Ultimate Degen Discord. Join on the Pro page. The names we keep an eye on get a page each for PRO DEGENERATE members.
For research and education purposes only. Not financial advice. May contain typos. Prices may be delayed depending on when the data was collected. © 2026 The Degenerates Journal. All rights reserved.
The Degenerates Journal · Saturday Basic · Saturday, October 24, 2026 · For research and education purposes only.
Position disclosure — checked November 8, 2026: of the names covered in this edition, the desk currently holds none. The desk’s current position book (QCOM · AVGO · TSLA · GOOGL · SNDK · MU) prints in the open in the current editions; see Methodology & Disclosures.
For research and education purposes only. Not financial advice.
Every edition of The Degenerates Journal, delivered free. No noise, no spam — unsubscribe anytime.
Loading the poll…